Editor's Note: Our colleague, the former $900 million hedge fund manager Larry Benedict, has discovered a way to make money from gold… WITHOUT buying a single ounce. Read on to learn more…
Dear Reader,
A former hedge fund manager has discovered a unique way to pull cash from the gold markets.
3 Dividend Growth Stocks That Keep Giving Investors a Raise
Posted On Oct 09, 2026 by Ian Cooper
Getting paid to own stocks is always appealing. Watching those payments grow year after year can be even better. That’s the attraction of dividend growth investing. When you buy shares in a company that can steadily increase its payouts, you have an opportunity to build a growing income stream without continually adding money to your account.
For someone planning for retirement, that kind of progress can matter. A rising income stream can help offset increasing living costs, while reinvesting dividends can purchase additional shares that generate payments of their own.
Elon is gearing up to buy a tiny, publicly traded company.
Why? Because it holds the exclusive rights to a $16 trillion MOTHERLODE of the exact materials his empire runs on... rare metals like cobalt, manganese and lithium.
On January 1st, a new Pentagon rule cuts off his Chinese supply.
Today, it's a $5 stock... but once Elon makes his move, it could soar to $50 within 6 months.
Dividend Growth Stocks: McDonald’s Continues to Look Tasty
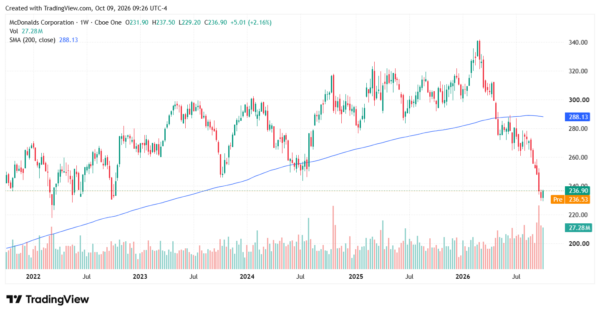
The restaurant giant increased its quarterly dividend to $1.93 from $1.86 per share. Its new annualized payout is $7.72, with the next payment scheduled for Dec. 15, 2026, for shareholders of record on Dec. 1.
This also marks its 50th consecutive year of dividend increases, qualifying McDonald’s as a Dividend King. Think about what that record represents. The company has continued raising its dividend through recessions, changing consumer habits, and periods of considerable economic uncertainty.
For an investor holding 100 shares, the new rate translates into $772 in annual dividends, compared with $744 previously. An extra $28 may not sound life-changing. But dividend growth investing is built around accumulating those increases over time. The appeal is a business that keeps finding room to pay shareholders more.
Dividend Growth Stocks: Philip Morris Shows Why It Pays to Be Defensive
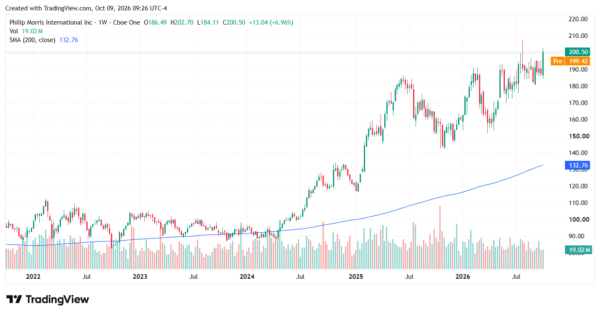
Philip Morris raised its dividend to $1.60 per share from $1.47, bringing its annualized payout to $6.40. The payment is scheduled for Oct. 26, 2026.
According to the company’s announcement, Philip Morris has increased its annual dividend every year since becoming public in 2008. Its cumulative increase of 248% demonstrates how a series of raises can substantially change the income an investment produces.
The key question for prospective buyers is whether the business can continue supporting that progress. One unusually strong increase is encouraging, but investors should avoid assuming an 8.8% growth rate will repeat indefinitely.
Dividend Growth Stocks: Altria is Dividend Royalty
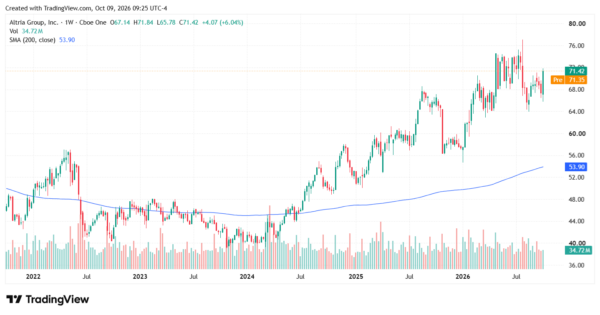
Altria raised its dividend to $1.11 per share from $1.06. That puts its annualized dividend at $4.44. The payment is scheduled for Oct. 9, 2026, for shareholders of record Sept. 15. Altria says this represents its 61st dividend increase in 57 years. It also targets annual dividend growth in the mid-single digits through 2028, although that remains a goal rather than a guarantee.
Before Buying Any Of These Stocks, Look Beyond the Announcement
Check how much of the company’s earnings and free cash flow goes toward dividends. A business needs enough cash left over to invest, service debt, and handle difficult periods. An attractive payout becomes less attractive if maintaining it strains the company’s finances.
Price matters, too. A rising yield can reflect a falling stock price, and dividend income may not offset capital losses. Likewise, even an excellent dividend grower can deliver disappointing returns if purchased at an excessive valuation.
Diversification also deserves attention. Owning both Philip Morris and Altria creates overlapping tobacco exposure; adding more tickers does not always add much variety.
Buying dividend growth stocks works best as a patient approach to business ownership. Look for sustainable payments, room for future increases, and a reasonable entry price. Over time, a collection of companies that can consistently afford to give shareholders a raise can help turn an investment portfolio into a more productive source of income.
Today’s editorial pick for you
Costco Sales Jump 13%, but Expectations Are the Real Story
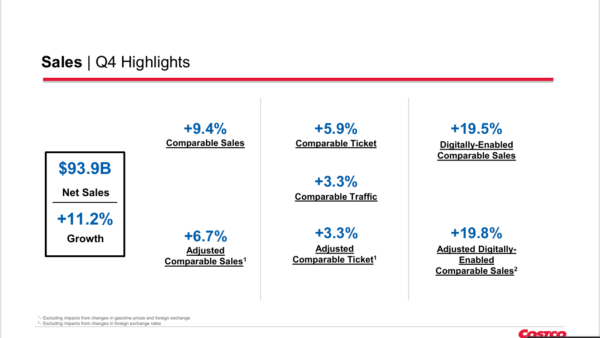
Comparable sales, excluding gasoline and currency effects, grew about 7.5% companywide. U.S. comparable sales rose 12.5%, or 8% on an adjusted basis. Digitally enabled sales jumped 19%.
The pattern looks familiar. On September 24, Costco reported fiscal fourth-quarter 2026 results. Quarterly sales climbed 11%, and full-year sales topped $297 billion. Higher gasoline prices helped then, and they helped again in September.
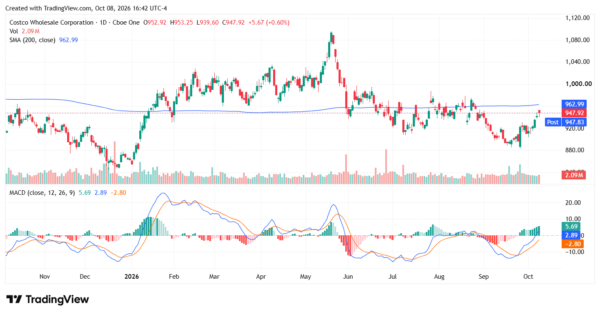
None of this is bad news. Yet COST stock closed at $947.92 on October 8. That’s still below its 200-day moving average near $963. It’s also about 14% under its May high of roughly $1,097.
So why isn’t a 13% sales gain doing more for the stock? The answer comes down to valuation and expectations. Costco has always been expensive. The question now is whether investors still believe its growth justifies the price.
Gas Is Doing the Heavy Lifting, but the Core Is Healthy
Gasoline was the biggest swing factor. Gas price inflation added about 3.8 percentage points to companywide comparable sales. The average selling price per gallon rose 32.8% from a year ago.
That flatters the headline number. But it doesn’t erase what’s underneath. Shopping frequency rose 4.7% worldwide and 4.3% in the U.S. The average transaction grew 2.8% with gas and currency stripped out.
In other words, more members are showing up, and they’re spending a bit more per trip. Nonfood sales grew by a high-single-digit percentage, led by gift cards, housewares and sporting goods. Fresh food rose by a mid- to high-single-digit percentage.
There is one caveat. A Labor Day timing shift added slightly more than half a point to September comps. October won’t have that tailwind.
But that comparison is a bit misleading. Costco’s current multiple sits about 10% below its own historical average. The stock is expensive relative to the broader market and to the retail sector. It isn’t expensive relative to itself.
Investors have always paid a premium for Costco. They pay for consistency, a loyal membership base, and a model that rarely disappoints. That premium hasn’t disappeared. It has simply shrunk.
What’s Changed Is Expectations
So what’s behind the smaller premium? In my view, it’s expectations. Investors appear to be pricing in slower growth.
Costco shoppers sit firmly on the upper leg of the K-shaped economy. Higher-income households have kept spending while others pull back. On paper, that’s a tailwind for Costco.
But there’s a wrinkle. Walmart (NASDAQ: WMT) and Dollar General (NYSE: DG) have both reported more traffic from higher-income shoppers, including for discretionary purchases. That’s spending that could otherwise land in a Costco cart.
To be clear, there’s no sign of that shift in Costco’s recent results. Member visits are still rising. But investors don’t want to be caught in a “gradually, then suddenly” trade. At 41x forward earnings, even a hint of share loss can matter.
Tariffs and the Membership Cushion
Costco is also stuck in the middle of trade policy. Tariff talks in Washington show no sign of resolving anytime soon. That leaves Costco managing cost uncertainty on imported goods. And a brand built on low prices has limited room to raise them.
The membership model softens much of this risk. Members pay an annual fee before they buy anything. Once that fee is paid, they have every reason to keep shopping there. That creates a floor under traffic that most retailers don’t have.
Costco investors know this. It’s a big reason the stock rarely trades at a discount, even in uncertain markets.
Analysts Are Bullish, but Not Chasing
Wall Street remains generally positive on COST. The consensus rating is a Moderate Buy. The average price target sits near $1,058, a little more than 10% above the October 8 close.
That’s a modest gap for a stock analysts like. And they don’t seem eager to push targets much higher. The current macro backdrop likely means interest rates stay elevated. It also leaves Costco with very little pricing flexibility. Neither condition argues for a richer multiple.
The chart tells a similar story. COST bounced from a late-September low near $885, and the MACD has crossed above its signal line. But the stock is now pressing against its 200-day moving average around $963. That line has capped most rallies since June. A decisive close above it would be a meaningful technical win.
The Wildcard: A Stock Split
One possible catalyst is a stock split. Management hasn’t signaled any plans for one. But that calculus could change if the holiday season disappoints.
There are plenty of ways that could happen. An escalation with Iran, a lame-duck Congress, or broader pressure on equities could all weigh on spending and sentiment.
Costco has split its stock several times, but not since a 2-for-1 split in January 2000. That’s more than 25 years. A split wouldn’t change the company’s value. But it would lower the price of a single share. For retail investors, that works a lot like a price cut.
Is COST Stock a Buy After Strong September Sales?
Costco’s September numbers confirm the business is healthy. Gas is inflating the headline, but traffic and core spending are growing too.
The stock’s challenge isn’t the business. It’s how much investors are willing to pay for it. Until the growth outlook clears up, COST may stay range-bound near its consensus target. A strong holiday season, or a surprise split, could change that.



Tidak ada komentar:
Posting Komentar