Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk's new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader,
In April 2026, Elon Musk announced he was partnering with Intel.
The result?
Shares took off…
And were trading 177% higher just two months later.
What Wall Street Expects From Amazon’s Q3 Earnings Report
Posted On Oct 15, 2026 by Ian Cooper
Amazon’s (NASDAQ: AMZN) upcoming earnings report will give investors a fresh look at growing demand for artificial intelligence and the cost of keeping up with it.
Wall Street expects Amazon to deliver another quarter of higher sales, although earnings forecasts vary across data providers. Right now, there are estimates of EPS of $1.96 per share on revenue of about $202.1 billion.
Management projected third-quarter revenue between $197 billion and $202 billion, or growth of 9% to 12%. It also forecast operating income between $22.5 billion and $26.5 billion, compared with $17.4 billion a year earlier.
Investors should also account for the timing of Prime Day. Amazon said that excluding the event’s impact in both years would make projected third-quarter sales growth nearly four percentage points higher. Simply comparing quarterly growth rates could therefore give an incomplete picture of demand.
AWS Has a High Bar to Clear
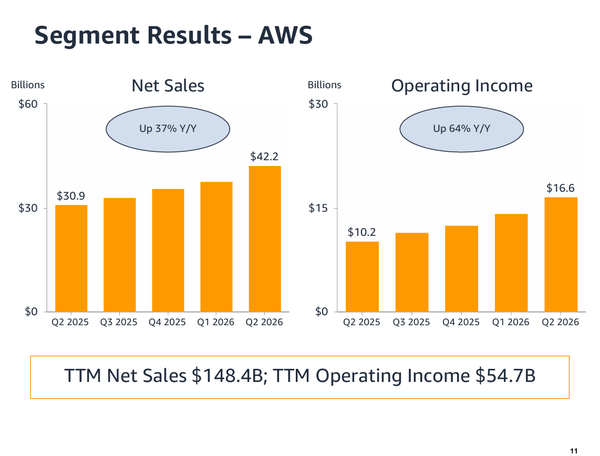
Amazon Web Services (AWS), the company’s cloud-computing division, will likely be central to the earnings reaction. In the second quarter, AWS revenue increased 37% to $42.2 billion, its fastest growth in 18 quarters. The division generated $16.6 billion in operating income, accounting for roughly 60% of Amazon’s total.
Those numbers explain why investors watch AWS so closely. Stronger cloud demand can have an outsized effect on the company’s overall profits. The question now is whether that momentum continued through September. Investors will be looking for evidence that customers are expanding their cloud workloads and spending more on AI services.
Source: Amazon
Recent Analyst Target Increases Add Optimism
Several recent analyst actions have strengthened the bullish case.
On Oct. 6, Tigress Financial raised its AMZN price target to $385 from $315 while maintaining a Buy rating. That represents a substantial increase in the firm’s valuation outlook.
Rosenblatt also raised its target, lifting it to $360 from $335 on September 30 and maintaining a Buy rating. The firm argued that concerns about AI shopping assistants disrupting the company’s advertising business were overstated. Its view is that Amazon can adapt as shopping habits evolve. Meanwhile, Goldman Sachs added Amazon to its conviction list on October 1 with a $375 price target, giving the stock another prominent endorsement.
The Spending Question Could Decide the Reaction
Amazon’s growth opportunity comes with a considerable bill.
Management’s 2026 capital-spending estimate reached approximately $220 billion, according to reporting on its second-quarter earnings call. Meanwhile, Amazon reported negative free cash flow of $7.6 billion over the twelve months through June, largely reflecting increased investment in AI infrastructure. Investors will want a clearer sense of when that investment can produce stronger cash generation.
Ultimately, Amazon needs to connect three things: healthy customer demand, profitable growth, and a credible return on spending. Strong AWS results and an encouraging holiday outlook could reinforce the recent bullish analyst calls. Another increase in spending without comparable progress could leave investors asking harder questions.
For AMZN investors, this earnings report comes down to a fairly simple question: Is all that spending starting to pay off? Higher sales would be encouraging, but stronger profits and a clearer path to generating cash would give shareholders more reason to feel confident. The recent analyst target increases suggest there’s optimism heading into the report. Now the company needs to back it up and show that it can keep growing without the bill growing faster.
Today’s editorial pick for you
Morgan Stanley’s Powerful $105 Billion Franchise Has One Big Weakness
Posted On Oct 15, 2026 by Grayson Cavern
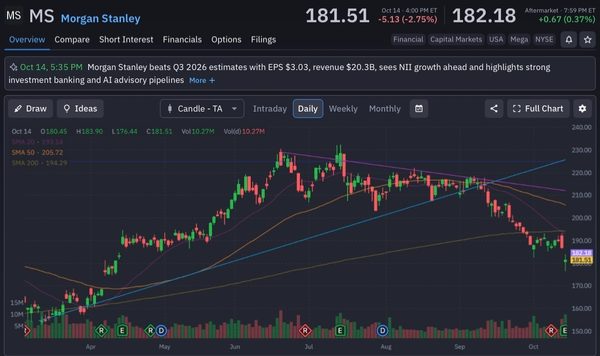
Morgan Stanley (NYSE: MS) is generating billions in profits, pulling in new client assets and producing a 22.6% return on tangible common equity. Yet the stock closed October 14 at $181.51, down sharply from its summer peak near $230. The third-quarter report gives investors a reason to stay interested in the franchise, but the numbers also expose a split between its strongest businesses and the parts losing momentum.
Table of Contents
Revenue climbed 12% year over year to $20.34 billion, while diluted EPS rose from $2.80 to $3.03. The bigger story sits inside those results: Wealth Management is expanding its recurring-fee base, while Institutional Securities is riding a powerful equities business. Investment Management, meanwhile, is dragging. That uneven performance helps explain why a strong earnings report has yet to turn the stock around.
Institutional Securities generated $10.03 billion in third-quarter revenue, up from $8.52 billion a year earlier. Equities supplied most of the lift, with revenue surging 41% to $5.80 billion on stronger client engagement across regions, particularly Asia. Investment banking revenue increased 2% to $2.16 billion, helped by higher advisory revenue from completed M&A activity in the Americas.
The weak spot was fixed income. Revenue declined 7% to $2.01 billion, reflecting lower performance in credit, securitized products, and commodities. Equity underwriting also fell from $652 million to $525 million as lower IPO and block activity outweighed higher follow-on offerings.
That mix makes the headline growth less straightforward than it first appears. Morgan Stanley has a powerful equities franchise, but a 41% jump in trading revenue can be difficult to repeat if client activity cools. Investment banking is improving, yet its growth remains modest beside equities. The next leg of institutional earnings growth needs broader participation across the segment.
Wealth Management Is Building a Larger Earnings Engine
Wealth Management delivered record revenue of $9.07 billion, up 10% year over year, and record pretax income of $2.8 billion, producing a 30.4% pretax margin. The business attracted $232.4 billion in net new assets and $80.5 billion in fee-based flows during the quarter. Fee-based client assets reached $3.16 trillion, up from $2.65 trillion a year earlier.
Those figures offer the strongest support for the long-term thesis. A growing pool of fee-generating assets can produce recurring revenue across market cycles, while the advisor-led channel keeps bringing new money onto the platform. Morgan Stanley also reported $201.1 billion in loans, compared with $173.9 billion a year earlier, as lending growth and higher average sweep deposits helped lift net interest income to $2.23 billion from $1.99 billion.
Keep in mind, just over half of the quarter’s net new assets were associated with IPO-related flows. That makes the record inflow figure less useful as a standalone measure of recurring momentum. Still, the combination of larger fee-based assets, stronger net interest income and a 30.4% pretax margin gives Wealth Management real weight in the earnings mix.
Investment Management Is the Weak Link
Investment Management generated $1.46 billion in revenue, down 12% from $1.65 billion a year earlier. Pretax income fell to $259 million from $364 million. Asset management and related fees increased to $1.57 billion, but performance-based income and other revenue swung to a $106 million loss from $117 million in positive revenue a year earlier. The company attributed the decline primarily to a reversal of accrued carried interest tied to certain private-fund investments.
That reversal helps explain why the segment’s results weakened even as assets under management rose to $2.05 trillion from $1.81 trillion. Long-term net flows were $15.8 billion, below the $17.9 billion recorded a year earlier.
The broader business is growing, but that growth is not reaching every earnings line evenly. Morgan Stanley’s consolidated revenue fell from $21.35 billion in Q2 to $20.34 billion in Q3, while EPS declined from $3.46 to $3.03. ROTCE also eased from 26.6% to 22.6%. The year-over-year trend remains positive, but the sequential pullback shows the firm has stepped down from a stronger quarter.
MS Needs to Reclaim $194
The stock is still under pressure. MS closed at $181.51, below its 20-day moving average at $193.14, its 50-day at $205.72, and its 200-day at $194.29. The rising trendline from the spring has broken, and the stock has retreated from its summer high near $230.
The first challenge is $190–$194, where the 200-day average sits near recent price action. A reclaim would be an initial sign that buyers are returning. Above that, $205–$212 is a tougher resistance zone. On the downside, the recent low around $176 is the level to watch; a break could expose the stock to another leg lower.
Morgan Stanley repurchased $1.54 billion in shares during the quarter and declared a $1.15 quarterly dividend. Its standardized Common Equity Tier 1 capital ratio stood at 14.9%. The franchise has scale, capital, and a growing wealth business. I’m sold on those fundamentals, but I would want to see MS reclaim $194 before treating the selloff as exhausted. The next bullish leg needs the chart to catch up with the business.


Tidak ada komentar:
Posting Komentar