Matt Weinschenk Publisher and Director of Research, Stansberry Research
P.S. Whitney believes what's happening today could reset the financial system after these midterm elections. If Whitney's even half-right, it's going to have a huge impact on your money and your future. Get the details here...
Today’s editorial pick for you
Biotech Blockbuster? Neurogene Could Rally 132% Says JPMorgan
Posted On Oct 08, 2026 by Ian Cooper
Neurogene (NASDAQ: NGNE) has had a difficult few months, but JPMorgan (NYSE: JPM) believes the biotechnology company could have substantial upside as it advances an experimental gene therapy for Rett syndrome.
Table of Contents
The firm just initiated coverage with an Overweight rating and a $60 price target, suggesting roughly 132% upside from Wednesday’s closing price. Analyst Priyanka Grover’s optimism centers on NGN-401, a potential one-time treatment that could become an important option for patients with the rare genetic disorder.
With shares down nearly 32% over the past three months, the call gives investors a reason to take another look. However, the investment case depends on something much more meaningful than a stock market rebound: whether Neurogene can turn encouraging clinical progress into an approved treatment.
Elon Musk has gone "all in" on Texas, home of SpaceX. But Texas just froze ALL new AI data center buildouts.
The reason? Data center demand in Texas has soared from 48 gigawatts to 474 gigawatts... since 2023, according to Reuters. But according to 60-year Wall Street legend Marc Chaikin, one company has the solution. Its "micro cluster" technology will consume an estimated 99% less electricity and water. And it'll come online as soon as Oct. 20th. When it does, it'll make current data centers obsolete when it comes to major AI breakthroughs – including Elon's Grok.
Rett syndrome primarily affects girls and can change a child’s development dramatically. After an initial period of apparently typical development, children may lose communication abilities, purposeful hand movements, and other motor skills. Walking difficulties, seizures, and breathing problems can also occur.
Nearly all cases involve mutations in the MECP2 gene, which provides instructions for making a protein important to brain development and function. When that protein is missing or does not work properly, the consequences can be severe.
For families, the impact extends into almost every part of daily life. That helps explain why researchers are pursuing treatments aimed at the underlying biology of the disorder.
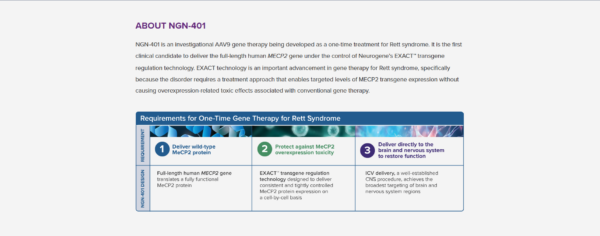
Neurogene’s NGN-401 is designed to deliver a functional copy of the MECP2 gene. The goal is to help cells produce the working protein patients need.
Neurogene’s Gene Therapy Takes a Controlled Approach
Gene therapy sounds straightforward in theory: deliver working genetic instructions to address a problem. In practice, getting the amount of protein right can be difficult. That challenge is particularly important here because producing too much MeCP2 can also be harmful.
Neurogene’s EXACT technology is designed to regulate expression of the delivered gene, limiting excessive protein production. NGN-401 is administered through an intracerebroventricular procedure, which delivers the therapy into fluid-filled spaces in the brain. It is being developed as a one-time treatment.
2027 Could Be a Make-or-Break Year for NGNE Stock
The next major chapter is expected in the second half of 2027, when Neurogene anticipates releasing topline results from its Embolden registrational trial. The company has completed dosing 25 participants in that study. A registrational trial is intended to generate evidence supporting a potential application for regulatory approval.
Earlier findings provide a reason for optimism. In its June update, Neurogene reported that all 10 participants in its Phase 1/2 analysis gained at least one developmental milestone and improved on a clinician-rated assessment. Participants gained 47 milestones collectively, with follow-up extending through 30 months.
Those results are encouraging, but a small early study cannot settle every question. Investors will want to see whether the next dataset reinforces the apparent benefits and supports a favorable balance between effectiveness and risk. That makes 2027 a potential turning point. Strong results could strengthen confidence in the program. Disappointing findings could undermine the investment case.
Neurogene Has Cash to Reach Its Next Major Catalyst
Clinical progress gets the headlines, but funding determines whether a biotechnology company can keep moving toward its goals.
Following its July financing, the company reported approximately $360.2 million in pro forma cash, cash equivalents, and short-term investments. Management expected those resources to fund planned operations into the first quarter of 2029. That projected runway extends beyond the anticipated 2027 results. It gives investors a clearer view of how the company expects to finance its next major milestone, although spending needs and timelines can change.
Can NGNE Reclaim Its 200-Day Average?
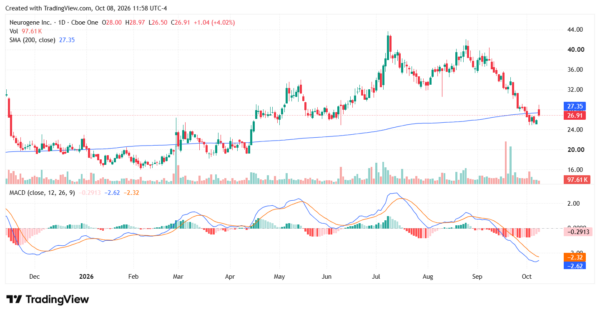
Neurogene stock remains in a technical downtrend after falling from around $40 in September to a recent low near $25. However, NGNE rebounded to $26.91 on Oct. 8, putting the stock just below its 200-day simple moving average at $27.35.
That level is now an important test: a sustained move above the 200-day average could signal that selling pressure is easing and put the $30-$32 area back in focus. A failure to reclaim the moving average would leave support around $25, followed by the low-$20s area.
The MACD remains bearish, with both the MACD and signal lines below zero, although the recent histogram suggests downside momentum may be moderating. Overall, the chart is still cautious, but a breakout above the 200-day moving average would materially improve the technical setup.
Today’s editorial pick for you
Goldman Sachs Turns Bullish on Palantir as AI Opportunities Expand
Posted On Oct 08, 2026 by Ian Cooper
Palantir Technologies (NASDAQ: PLTR) could see even more upside thanks to AI, according to Goldman Sachs (NYSE: GS). In fact, the firm just upgraded the software company to Buy from Neutral, arguing that its recent stock underperformance has created a more attractive opportunity.
Table of Contents
Analyst Gabriela Borges also increased her Palantir 12-month price target to $230, arguing that the company’s potential market could expand further. Borges framed the debate around Palantir’s nearly $8 billion annualized revenue run rate and roughly 100% growth rate, as described in her notes. Those figures help explain both the excitement surrounding the business and the questions about what comes next.
Goldman highlighted three areas that could expand Palantir’s opportunity: sovereign AI, customized applications, and a strategy focused more closely on individual industries.
Sovereign AI broadly involves countries seeking greater control over their AI capabilities, infrastructure, and data. For software providers, that can create opportunities to help organizations deploy AI while meeting their operational and security requirements.
Customized applications address another practical challenge. Businesses have different systems, responsibilities, and problems. An AI tool that works well for one organization may need substantial adjustments before it becomes useful somewhere else.
Palantir’s Engineers Give It a Competitive Edge
Another major part of Goldman’s argument involves Palantir’s forward-deployed engineers, or FDEs. These engineers work closely with customers to understand their operations and help turn software into practical solutions. That hands-on approach matters because installing technology and getting useful results from it are separate challenges.
A customer might have valuable information scattered across several systems. Employees may also have established processes that new software needs to accommodate. Helping solve those problems can make a product more useful. It can also give Palantir valuable feedback about what customers need next.
Borges believes Palantir’s close connection between customer work and product development helps address that concern. Her argument is that the company has refined parts of the process enough to automate them through AI.
Strong Earnings and Guidance Support the Bull Case
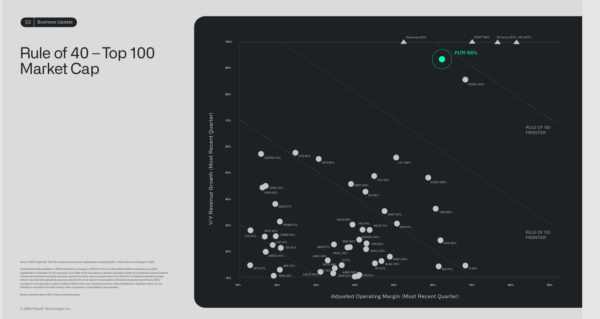
“Demand for AI sovereignty has now been unleashed. And Palantir is the only company that has demonstrated it can transform tokens into actual economic value. Our customers trust us to provide them with maximal control over their operations, data, and decisions. Their competitive advantage should never become the training data for future models. This quarter was otherworldly: our U.S. commercial revenue grew 149% year-over-year, our overall revenue grew 93% year-over-year, and our Rule of 40 score climbed to 155%. The sovereign AI revolution makes us very optimistic about the future,” added Alex Karp, Co-Founder and Chief Executive Officer of Palantir Technologies.
Looking ahead to the third quarter, Palantir expects revenue to be between $2.16 billion and $2.164 billion, above the $2 billion estimate. Palantir expects adjusted operating profit during the period to be between $1.29 billion and $1.3 billion, above the $1.14 billion estimate. For the full year, Palantir now expects sales to be between $8.15 billion and $8.16 billion, above the previous range of $7.65 billion to $7.66 billion.
PLTR Stock Tests Key Resistance
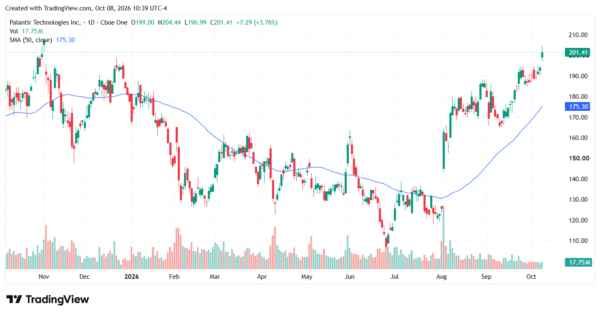
PLTR stock has regained strong upward momentum, with PLTR closing at $201.41 on Oct. 8 and trading well above its 50-day simple moving average of $175.30. The chart shows a clear series of higher highs and higher lows since the sharp recovery that began in August.
The latest move has pushed PLTR back toward the $205 area, which represents an important resistance zone near its prior high. A decisive breakout above that level could put the psychologically important $210 mark in focus.
On the downside, the $190 area offers an initial level to watch if the stock pulls back, while the rising 50-day moving average around $175 provides a deeper technical support level. Overall, the trend remains bullish as long as PLTR stays above its rising 50-day average.
What Investors Should Watch Next
Goldman’s upgrade gives investors a clear thesis to evaluate: a larger market, more specialized applications, and potentially more efficient delivery.
The next step is watching whether business results support those expectations. Revenue growth matters, but so do profitability, customer expansion, and the resources required to deliver that growth. Palantir’s opportunity is compelling because businesses need help turning AI spending into useful results. Its challenge is delivering those results consistently while meeting the expectations attached to its stock.


Tidak ada komentar:
Posting Komentar