 A Message From Investors Alley Want investment income without spending your retirement trading options? That's the appeal of the funds I call "Paycheck ETFs." The managers handle the options trades inside the fund. You buy ETF shares through your brokerage account. You don't have to choose contracts, track expiration dates, or decide when to close each trade. See how these funds generate income actively while all you have to do is buy-and-hold. That doesn't remove the investment risk. It puts the trading work in the manager's hands. And it opens up an income approach you may have dismissed as too complicated. I explain how it fits into your retirement plans in my Freedom Number presentation. Potentially generate up to $5,000 a month with these new funds (learn how) → Tim Plaehn
Today's Exclusive Story
IREN Limited's AI Pivot Gains Traction—But Can Its Data Centers Deliver?Authored by Thomas Hughes. First Published: 10/14/2026. 
Key Points
- IREN's previously announced AI lab contract has gained attention following an unconfirmed report linking the customer to Anthropic.
- Long-term agreements with Microsoft, NVIDIA, and other AI customers support IREN's expansion into AI cloud services.
- The company has secured substantial GPU financing, but construction timelines, customer concentration, and rising debt remain risks.
- Special Report: Elon's warning for America
IREN Limited (NASDAQ: IREN) drew market attention with its Q2 earnings release, which prominently announced a new, multiyear deal with a frontier hyperscale AI lab. The news was compounded by an as-yet-unconfirmed report that the customer may be Anthropic. Regardless, it is potentially game-changing news for the company, validating its shift from cryptocurrency mining to AI and establishing another long-term contract that improves revenue visibility. The question is what this means for the stock’s price, and the implications could be substantial. Hyperscale deals with leading frontier labs provide greater visibility into future operations and validate the AI buildout—not only industry-wide, but more importantly, for IREN’s cash flow and future profitability.
Among the questions answered is who will pay for IREN’s capacity and how. Assuming the contract is with Anthropic, the company’s revenue run rate topped $65 billion as of July, up from $47 billion in May, underpinned by enterprise demand. Reported projections suggest Anthropic could generate roughly $190 billion to $200 billion in annual revenue by 2028. The question it does not answer is whether Anthropic can monetize that capacity and sustain the contract over the longer term, creating value for both companies’ investors. 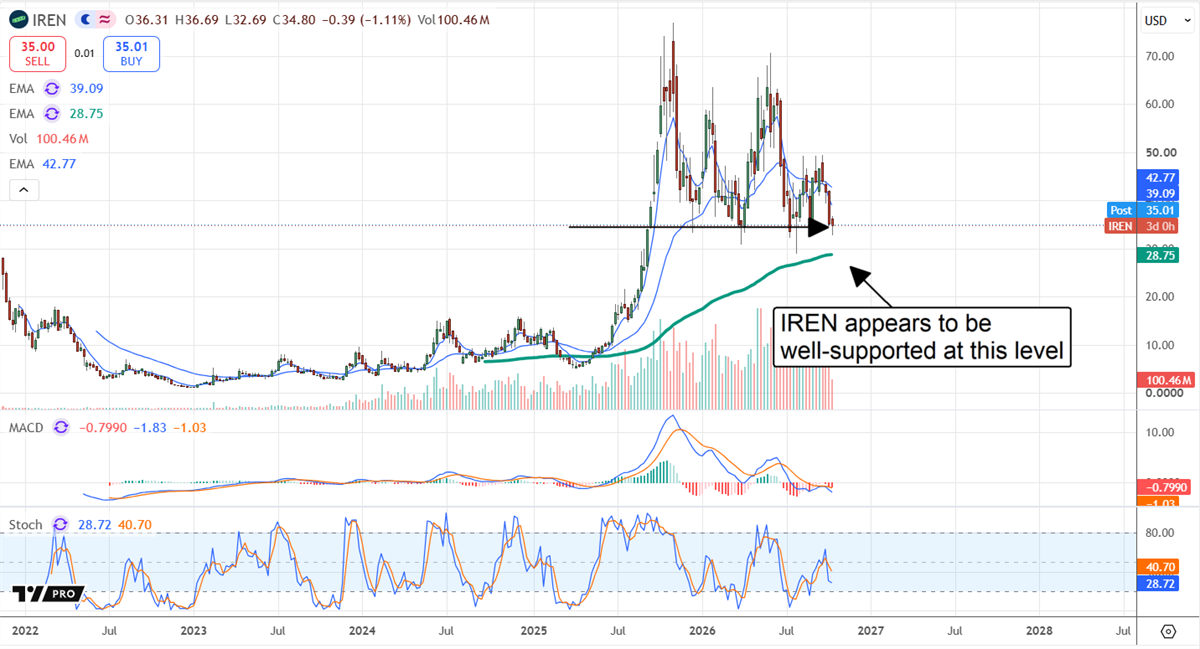
IREN Aggressively Expands Its Data Center BusinessIREN is aggressively expanding its data center business, having decommissioned cryptocurrency capacity sooner than expected to repurpose it for AI. The impact on results was tangible, leading to wider-than-expected losses, but the move accelerated the timeline for monetizing its backlog. As it stands, the company is targeting approximately 300MW of AI IT capacity by year-end and about 800MW by the end of 2027. Looking ahead, IREN has secured 5 GW of power across North America, Europe and the Asia-Pacific region, with additional AI infrastructure projects under construction and in development. Not all of that future capacity is covered by long-term contracts. Customer concentration risk remains, with most of the backlog tied to Microsoft (NASDAQ: MSFT), but the portfolio is growing. IREN’s announced AI cloud contracts exceed $13 billion in total value, underpinned by a $9.7 billion, five-year contract with Microsoft. Microsoft booked 200MW of capacity over four installments, the first of which was delivered in August. That deal, along with other contracts with AI developers, brought contracted annualized run-rate revenue to $4 billion for planned 2026 capacity, compared with $1 billion in operating annualized revenue as of late August. Much of the associated GPU spending is covered by committed financing and customer prepayments. IREN’s outlook is also somewhat less risky because of its project funding, which includes upfront payments and innovative financing that help limit the need for dilutive funding. Microsoft agreed to pay 20% upfront to finance GPU capacity, while newer contracts include customer prepayments covering approximately 45% to 55% of GPU costs, with additional financing provided by private creditors. The Microsoft deal includes debt and upfront payments totaling about 96% of the build, while the newer contracts are even more favorable. In some cases, financing and prepayments exceed the associated GPU costs. IREN Buys Growth, Expands Capacity in SpainIREN isn’t just building data centers; it is also buying growth as it accelerates its AI infrastructure business. Recent additions include Spain’s Nostrum Group and Mirantis Inc., providing an entry into the European Union (EU) and shifting its business from infrastructure provider to full-stack AI factory original equipment manufacturer (OEM). Nostrum Group is, notably, the Spanish version of IREN, building eco-friendly data centers and power solutions, while Mirantis Inc. provides what it calls a “metal to models” platform that can automate data center operations from initialization through model training and deployment. And if there was ever any doubt about the seriousness of IREN’s buildout plans, investors need only look to the NVIDIA (NASDAQ: NVDA) partnership. Announced in May 2026, the deal aims to accelerate the deployment of up to 5 GW of NVIDIA-based capacity, with a focus on IREN’s 2 GW Sweetwater, Texas, facility. The partnership also includes a $3.4 billion contract for IREN to provide AI cloud capacity for NVIDIA’s internal workloads. The next catalyst is the upcoming earnings report, expected in early November. Analysts are hopeful, but a hurdle remains: They forecast a year-over-year revenue decline tied to the decommissioned cryptocurrency business. Investors should focus on details such as new capacity, updates on its timing, new contracts and balance sheet health. The balance sheet boasts significant growth and ample liquidity, offset by rapidly increasing debt. The good news is that the business is on track to pay it back, but that will take time—and that is the risk for investors. The company is on track to ramp up capacity, but the biggest increases will not occur until next year and 2028, leaving investors with a long time to wait. . |


Tidak ada komentar:
Posting Komentar