Editor's Note: Our colleague, the former $900 million hedge fund manager Larry Benedict, has discovered a way to make money from gold… WITHOUT buying a single ounce. Read on to learn more…
Dear Reader,
A former hedge fund manager has discovered a unique way to pull cash from the gold markets.
Shares of Meta Platforms surged 11% on Monday, producing their strongest daily percentage gain since April 2025. The stock also reached its highest closing level since October 2025. While several factors may be supporting the rally, enthusiasm surrounding Muse appears to be one of the biggest catalysts. For investors who have spent months questioning Meta’s massive AI spending plans, Muse offers something they have been waiting to see: a potentially marketable product that ordinary consumers are eager to use.
Meta Platforms CEO Mark Zuckerberg has described the company’s AI vision as a push toward “personal superintelligence.” The idea is to create technology that understands individual users, adapts to their preferences and assists them with increasingly complicated tasks.
Muse is an early example of how that strategy could work.
Introduced on September 8, the AI assistant is designed to do more than answer questions or generate text. It can perform multistep assignments such as collecting information from several online accounts, completing web forms, comparing products and making purchases.
Muse can even negotiate certain online transactions on behalf of a user.
Consumers can interact with the assistant through the dedicated Muse app or access it through WhatsApp. That integration could prove especially valuable because WhatsApp already has a massive global user base. Instead of asking people to adopt an entirely unfamiliar service, Meta can place its AI tools inside platforms they already use regularly.
Meta Platforms Is Turning AI Spending Into a Catalyst
The rapid rise of Muse is contributing to an impressive month for Meta’s stock.
Shares have gained approximately 29% since the beginning of the month, putting the company on track for its strongest monthly performance in more than 13 years.
That is a significant turnaround.
Earlier in the year, investors reacted negatively when Meta increased its spending projections for 2026. The company is now expected to invest between $130 billion and $145 billion in capital expenditures this year. Much of that money will be directed toward data centers, computing equipment and the infrastructure needed to develop and operate advanced AI systems. Even for a company as profitable as Meta, that is an incredible amount of money.
The biggest concern was not whether Meta could afford the investment. Its core advertising business continues to generate substantial revenue and cash flow. The bigger question was whether the company could turn all that AI infrastructure into profitable new products.
Muse is beginning to ease some of those fears.
Meta Platforms Is Building Several Paths to Revenue
The basic version of Muse is currently free, which gives Meta an opportunity to attract a large audience. However, the company also offers paid subscription levels priced at $20 and $100 per month. Those subscriptions could create a new stream of recurring revenue if users decide that Muse saves enough time or provides enough value to justify the monthly expense. The higher-priced tier could be particularly attractive to business owners, professionals and other customers who regularly handle complicated online tasks.
Subscriptions are not Meta’s only potential AI revenue source.
The company recently introduced the Meta Model API, allowing developers and businesses to pay for access to its underlying AI models. It represents the first time Meta has directly charged enterprise customers and developers for this type of access.
Meta Platforms Stock Breaks Higher as Momentum Accelerates
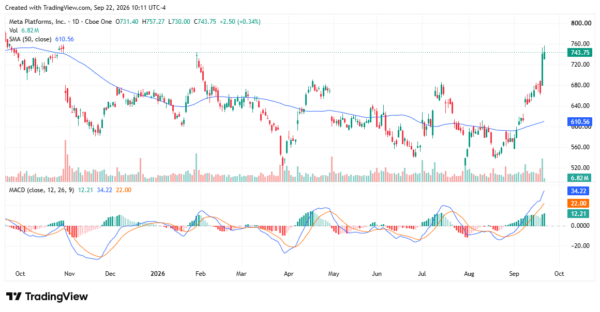
The chart suggests META stock has entered a significantly stronger technical setup. META closed at $743.75 on September 22, well above its 50-day moving average near $610.56. More importantly, the stock has broken out of the trading range that dominated much of the summer, with the recent move carrying shares toward the $760 area.
Momentum indicators are reinforcing the breakout. The MACD line sits around 34.2, compared with approximately 22.0 for the signal line, producing a positive histogram of roughly 12.2. Both lines have moved sharply higher since August, indicating that buying momentum has accelerated rather than simply producing a one-day spike.
The next important test is the $760 area, followed by the $800 level. A sustained move through those zones could keep the bullish trend intact. Conversely, a pullback toward the recent breakout area would give investors a better indication of whether the move has established new support.
Meta Platforms Stock Gets a New AI Growth Catalyst
For months, Wall Street largely saw billions of dollars flowing into data centers and advanced computing systems. Now investors can see a popular consumer product emerging from that investment. If Muse can maintain user interest, convert free customers into paying subscribers and expand across Meta’s collection of platforms, it could become an important new growth engine. More importantly, it could demonstrate that Meta Platforms’ expensive pursuit of personal AI is capable of producing real commercial results.
Today’s editorial pick for you
Costco Earnings: 3 Things Wall Street Wants to See
Posted On Sep 18, 2026 by Ian Cooper
Costco Wholesale (NASDAQ: COST) will report its fourth-quarter results after the market closes on September 24, 2026. As usual, Wall Street will be watching much more than the company’s headline earnings and revenue numbers.
Analysts currently expect the company to report quarterly earnings of approximately $6.55 per share. However, expectations may be a little too optimistic. Bank of America is reportedly looking for adjusted earnings of $6.52 per share, while analysts at Oppenheimer have also cautioned that the consensus estimate could be difficult to beat.
That sets up an interesting earnings report. Costco’s sales appear healthy, but the company may need more than another solid quarter to satisfy investors.
Elon Musk is rolling out a breakthrough technology that could replace our need for foreign oil.
Called “Dark Energy,” it can be deployed anywhere, goes online in about 5 minutes, and is 326 times more powerful than emergency generators used by hospitals.
But Musk has to go through a small group of little-known suppliers to get it.
Unlike many retailers, Costco releases monthly sales updates. That means investors already have a reasonably good idea of how much merchandise moved through its warehouses during the quarter.
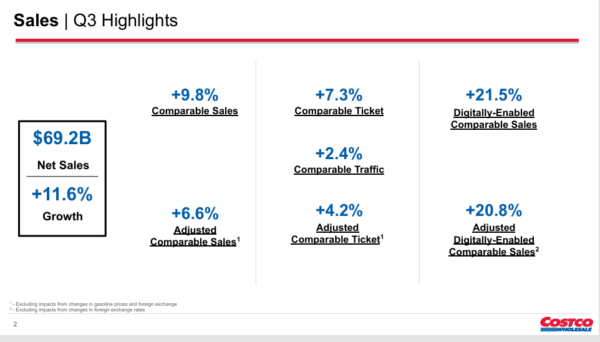
For the 16-week fiscal fourth quarter, Costco reported net sales of $93.9 billion, an increase of 11.3% from $84.4 billion a year earlier. Total comparable sales rose 9.4%.
Online growth was especially impressive. Digital comparable sales jumped nearly 20% during the quarter. That provides evidence that Costco is becoming more than a traditional warehouse chain. Its online operation is turning into an increasingly important growth engine.
Membership Growth Will Be Critical
Costco’s membership business is one of the most important parts of its financial model.
Membership fees provide a reliable stream of high-margin revenue, allowing Costco to keep merchandise prices low. That helps attract shoppers, strengthens customer loyalty and encourages members to renew their subscriptions.
Investors will also want to know whether more customers are upgrading to the higher-priced Executive membership.
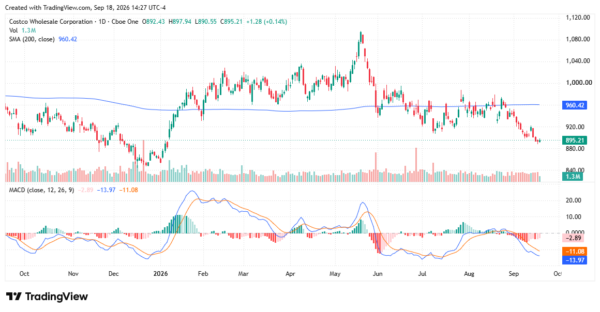
A slowdown in membership growth has become one of the market’s biggest concerns. COST stock is about 18% below its previous record despite the company’s strong sales performance.
Margins Could Decide the Market’s Reaction
Strong revenue does not automatically translate into strong earnings. That is why Costco’s operating margins may determine how investors respond to the report.
The company must manage higher wages, transportation expenses and other operating costs while maintaining the low prices that members expect. Gasoline sales can also complicate the picture. Higher fuel prices may increase reported revenue, but gasoline generally carries lower margins than many products sold inside Costco’s warehouses.
Wall Street will want to see whether Kirkland Signature, the company’s private-label brand, is helping offset those pressures. Kirkland products can provide attractive value to customers while giving Costco greater control over pricing and profitability.
Investors should also listen to the earnings call for management’s comments about tariffs, inflation and product sourcing. The company has enough purchasing power to negotiate favorable terms with suppliers, but it is not immune to rising import or commodity costs.
Could COST Announce a Special Dividend?
Some analysts believe Costco may be preparing to announce another special dividend. The company last distributed a special dividend of $15 per share in January 2024. Based on COST’s current share price and its history of returning excess cash to shareholders, that could happen.
However, there is no guarantee that management will make such an announcement alongside earnings. Still, the company’s cash-generating ability makes the possibility worth watching. A large special dividend could soften the market’s reaction if earnings come in slightly below expectations.
What to Watch After Costco Reports Earnings
Costco heads into its earnings report with strong momentum. Quarterly net sales increased by double digits, comparable sales remained healthy and digital activity expanded rapidly.
However, Wall Street already expects that. The real questions are whether profit margins are holding up, membership growth can accelerate, and management can provide a confident outlook for the new fiscal year.


Tidak ada komentar:
Posting Komentar