|
Reader,
If my math is correct, what I'm about to reveal here could generate as many as 410 new millionaires a day.
It's a brand-new project I call "The Presidio Initiative."
And the window to get in early is open right now.
I will explain everything in a short video...
I'll even tell you a way to invest in this right now with a 100% FREE recommendation revealed in the video.
Watch my presentation here.
Yours in smart speculation,
Bryan Bottarelli, Co-Founder
Monument Traders Alliance
P.S. Billionaires are already backing this mega-project. Including Elon Musk. According to one respected futurist (and New York Times bestselling author): "Twenty-trillion-dollar checks (are) waiting to be cashed." But nobody is talking about this quite like what I will show you...
Go here to see what I mean.
Amazon Raised Pay to $20. What It Costs Shareholders.
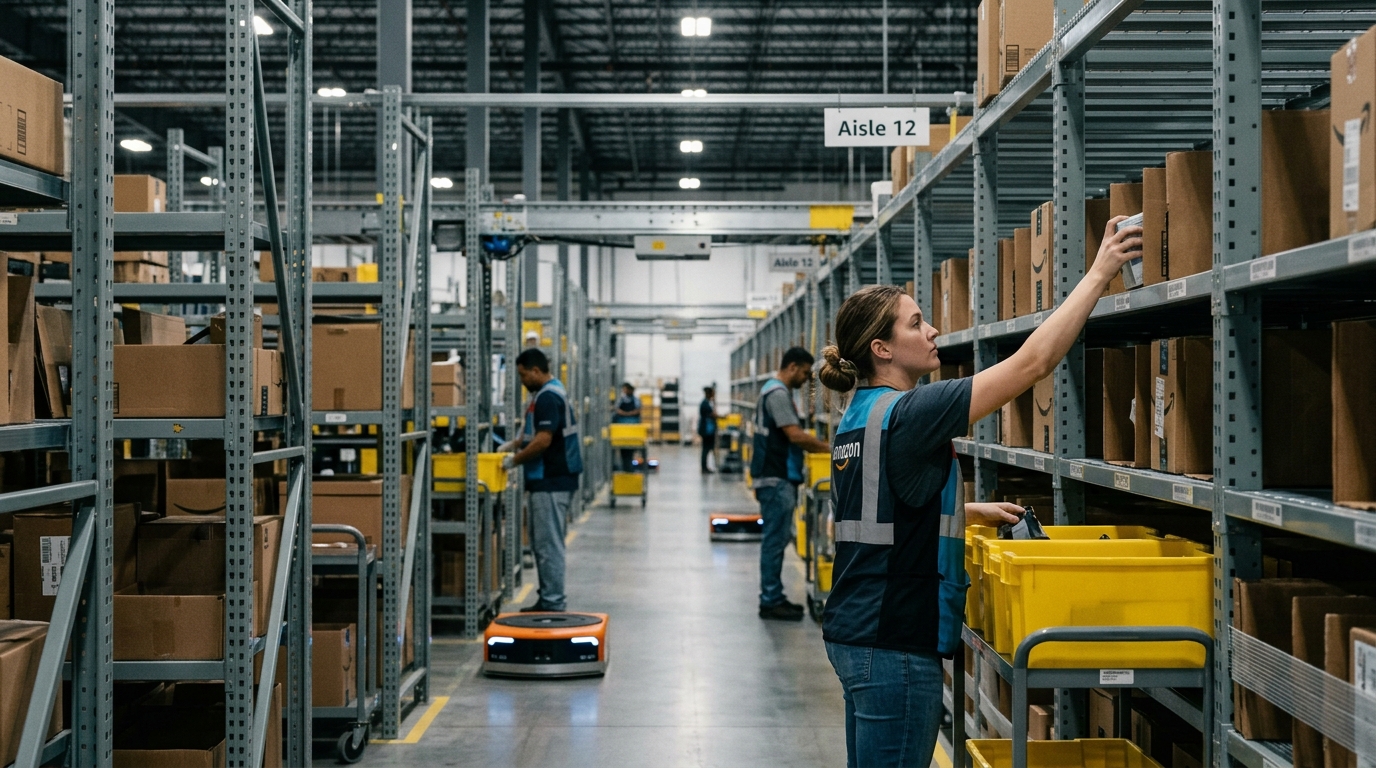
Hey there, bargain hunter. Amazon dropped two pieces of news on Wednesday that, taken together, tell you a lot about the cost of owning retail-facing shares right now. ScoreboardAmazon is raising the minimum starting hourly wage for its U.S. full-time core operations employees to $20, a $1-per-hour increase across the board, bringing average pay for those workers to nearly $24 an hour. Average total compensation, including benefits, will exceed $32 an hour. The company said the investment behind the increase totals more than $1.5 billion. It kicks in September 27. On the same afternoon, the Federal Reserve approved its first interest rate hike since the summer of 2023, lifting its benchmark rate 25 basis points to a target range of 3.75% to 4%. The Real Reason Both of These Matter TogetherThe Fed’s updated projections still point to inflation running above target in 2026, and most officials penciled in at least one more 25-basis-point hike before year-end, according to the Associated Press. That means the cost of capital is rising at the same moment Amazon is layering on a nine-figure wage bill. Neither event is catastrophic alone. Together, they compress the valuation math from two directions at once. Deep Dive: How Amazon's Operations Business Actually WorksAmazon's retail segment is not a margin engine. It is a volume engine that funds everything else. The warehouses, sortation centers, and delivery stations that will absorb this $20 floor are cost centers, not profit centers. In Q1 2026, the North America segment produced operating income of $8.3 billion on $104.1 billion in revenue, a segment margin of 9.0%, up from 8.0% a year earlier. That improvement came from logistics density: Amazon delivered same-day or overnight service for over 1 billion items in the quarter, and that throughput is what compresses fulfillment cost per unit. Labor cost is the one variable hardest to offset with robots on a compressed timeline. Amazon has said it plans to hire 250,000 full-time, part-time, and seasonal workers in the U.S. across its fulfillment and transportation network for the holidays. Every one of those hires now enters at a higher base. Is It Cheap?Amazon's net profit margin as of June 30, 2026 stands at 17.44%. That is a company-wide figure, carried heavily by AWS and advertising, both of which run at software-like incremental margins. The retail slice is the drag. Amazon notes that minimum starting pay has already risen more than 17% over the past three years, so this is not a one-time shock. It is a trend. The question is whether the Q4 revenue surge covers the incremental labor cost or whether it shows up as North America margin disappointment in the February earnings release. Bull / Base / Bear
- Bull: Amazon's logistics density absorbs most of the cost. Holiday volume is strong enough to lift segment margins above the Q1 9.0% level. AWS and advertising cushion the consolidated number. Shareholders barely notice.
- Base: North America operating margin retreats 50 to 75 basis points from Q1 levels in Q4 as wage costs front-run the revenue surge. AWS holds, advertising grows, the stock digests a modest earnings miss and moves on.
- Bear: Inflation stays elevated and a second Fed hike arrives later this year. Consumer spending softens enough to disappoint on the top line, and the $1.5 billion wage cost hits full force. North America margin reverts toward 7% and guides cautiously into 2027.
Action PlanDo not sell on this headline alone. The wage increase is real cost, but Amazon's retail margin story is still structurally better than it was three years ago. The Associated Press noted that Walmart’s average hourly starting wage is $16, so Amazon is buying labor market positioning, not just compliance. If you already hold AMZN and your cost basis is below $200, hold. If you are looking to add, wait for the Q3 results in late October. If retail margins hold above 8.5%, add on any weakness. If they dip below 8%, trim and reassess. Cheap Investor Scorecard
- North America segment margin: watch for Q4 vs. Q1's 9.0% baseline
- $1.5 billion wage cost: is it offset by Q4 volume or does it bleed into guidance?
- Seasonal hiring cadence: 250,000 workers at a higher base changes the cost-per-unit model
- Fed path: most Fed officials penciled in at least one more hike in 2026, which lifts discount rates on future earnings
- Diesel and freight: energy shocks can raise delivery costs before they get cheaper
- AWS and advertising margins: these carry the consolidated number; watch for any sign of deceleration
- Competitor wages: Walmart says supply chain associates average $27.50 an hour, so Amazon is competing in a tight labor market without needing to match every role dollar for dollar
Bottom LineIf Q4 volume is strong and logistics density holds, the $1.5 billion wage cost is a rounding error on a business running $400-plus billion in annual revenue. If the Fed hikes again later this year and consumer spending softens, that same cost becomes the margin story for the whole quarter. The shares are not obviously cheap or expensive at current levels. They are fairly priced for continued execution. One slip in North America margins, layered on top of another rate hike, and the story changes fast. Watch the Q3 release before committing new capital. |


Tidak ada komentar:
Posting Komentar