 A Message From Behind the Markets Dear Friend, Your mortgage rate, your car loan and your savings rest on one assumption: that the world keeps buying American debt. They stopped. China held $1.32 trillion of U.S. Treasury debt at the peak. Today, roughly $659 billion. An 18-year low. That money went into gold. Beijing's central bank has bought gold 20 months straight, its longest streak in a decade. Goldman Sachs ran the London flows and put China's real buying at 4.8 times the official figure. And the European Central Bank confirmed what has not been true in generations: gold has overtaken U.S. Treasury bonds as the world's #1 reserve asset. 27% gold. 22% our debt. The world's most conservative money is not hedging the dollar. It is leaving it. When foreign buyers stop absorbing our bonds, your rates rise and the interest bill eats the budget. You feel it at the pump and the grocery store. Washington's counterattack is already signed, funded and filed, with one small American gold company at the center of it. See Washington's counterattack here >> "The Buck Stops Here," Kelly Maguire Behind the Markets
Additional Reading from MarketBeat Media
Ollie's Bargain Outlet Stock Falls on Weak Comps Despite Margin GainsWritten by Thomas Hughes. Publication Date: 9/6/2026. 
Key Points
- Ollie's shares fell after weak comparable-store sales overshadowed margin gains, with adjusted EPS of $1.42 beating expectations by 30 cents.
- The company is converting former Big Lots stores into new locations, driving nearly 12% store growth and a path to margin recovery through dark rent conversion.
- MarketBeat tracks 17 analysts rating OLLI a Moderate Buy with roughly 40% upside, citing expectations for easing headwinds and accelerating share buybacks.
- Special Report: The 38% Crash Warning Every Retirement Saver Needs to Read Right Now
Ollie’s Bargain Outlet's (NASDAQ: OLLI) share price fell following its Q2 release as near-term headwinds overshadowed its structural improvements. The primary near-term headwind is a weak comparable-store performance, with comps declining unexpectedly as basket sizes contracted. The weakness runs counter to industry trends, as other retailers—particularly off-price and discount retailers—continue to perform well. As a result, the setback may prove to be more of a one-off than a lasting trend.
Management cited weather, consumer headwinds and an increasingly promotional selling environment as the reasons for the top-line miss. Investors should focus on the fact that Ollie’s continues to provide value for its customers, as reflected in the growth of its loyalty membership base. The membership base grew 12.7% year over year as of Q2, and it is not the only structural improvement worth noting. Ollie’s growth strategy involves converting former Big Lots facilities into new Ollie’s Bargain Outlets. The strategy requires high upfront costs, including significant dark rent, but it enables rapid growth and provides a path to margin recovery. The company grew its store count by nearly 12% over the 12 months leading up to the release and expects to sustain that robust pace through year-end. The path to margin recovery involves converting dark rent into revenue-producing floorspace and leveraging scale. Ollie’s business is expanding rapidly, enabling stronger relationships and better deals with its supply chain partners. Ollie’s Mixed Q2 Was Strong Where It CountsOllie’s Q2 report was not without disappointments. Revenue growth missed expectations, but the 9.1% advance still outpaced that of most retailers. New stores underpinned growth, offsetting weak comps, and the quarter also featured several strengths. The primary driver was the impact of dark-rent conversion on margins, cash flow and profits. These metrics improved and outperformed despite the revenue miss. Key details included a 330-basis-point (bps) improvement in adjusted EBITDA margin, a nearly 40% increase in net income and a 43% increase in adjusted earnings per share (EPS). Adjusted EPS came in at $1.42, 30 cents above expectations. Guidance is a near-term hurdle for the stock, but profitability blunts its impact. Ollie’s reduced its full-year revenue outlook, putting the midpoint below MarketBeat’s consensus estimate. Improved margins and a stronger earnings forecast, however, should cushion the top-line miss and reinforce the case for capital returns. While growth is a critical factor, cash flow and the capacity to return capital are even more important—and Ollie’s is on track to return ample cash over time. Catalysts for investment include buybacks, which are expected to accelerate based on the updated guidance. Trailing-12-month activity reduced the share count by more than 2.5% in Q2 on average, giving investors significant leverage. The full-year guidance update includes a 40% increase in expected annualized buyback spending. Analysts Stay Bullish Despite Mixed ReactionsAnalysts' responses to the release were mixed, much like the results. Some focused on the headwinds, while others emphasized margins. Several lowered their price targets, while others raised them or reaffirmed the consensus rating and price target. As it stands, MarketBeat tracks 17 analysts rating OLLI a Moderate Buy. The data shows a bullish bias and approximately 40% upside relative to the post-earnings share price. Key takeaways include expectations that headwinds will ease, comps will improve and margins will expand over time. Institutional ownership also reflects confidence in the long-term outlook and capital returns, with institutions owning more than 99% of the shares and accumulating moderately in 2026. 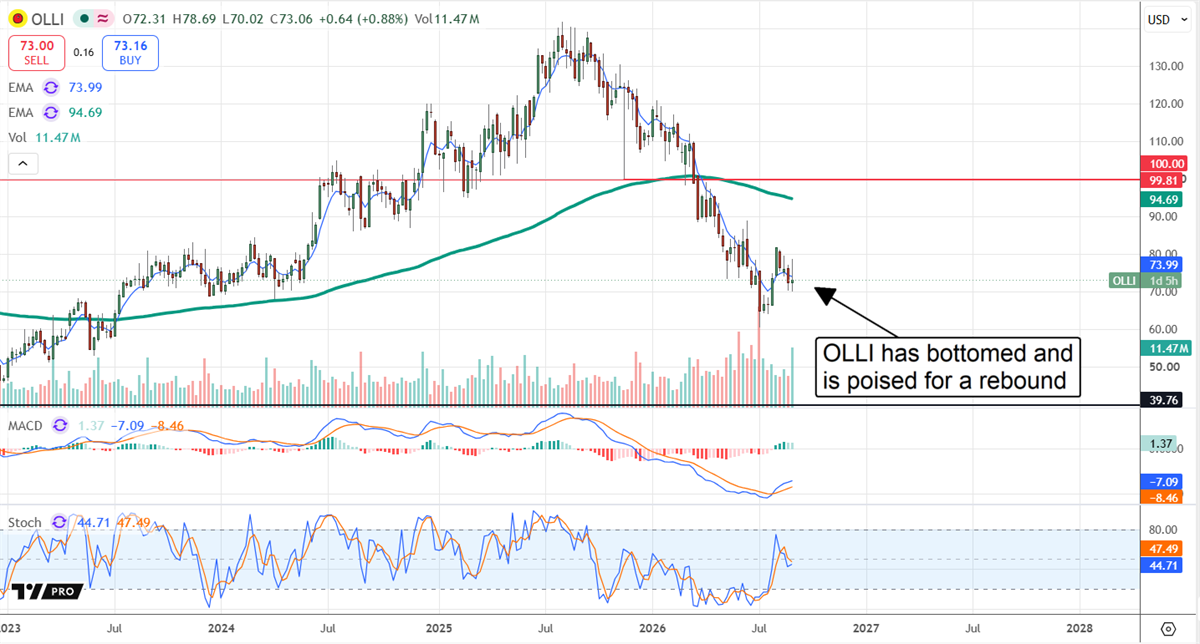
Ollie's Strong Balance Sheet Fuels Growth StrategyOllie’s Bargain Outlet’s balance sheet provides no red flags for investors. Highlights at the end of the quarter included reduced cash related to buybacks, increased inventory and investments, smaller increases in liabilities, and improved equity despite the share repurchases. Leverage remains very light, with long-term, non-lease debt below 0.1x equity, total liabilities below 1x equity, and cash flow improving. Looking ahead, Ollie’s is positioned for accelerated earnings growth even without an improvement in consumer habits. Improving consumer habits would accelerate both revenue and earnings growth further. This year’s catalysts include completing and opening two new distribution centers. These centers will enable the company to serve more than 800 locations seamlessly before additional infrastructure is needed. This sets the stage for profitable growth over the next two years without additional capital expenditures. The biggest risks are consumer headwinds, inflation and gasoline prices, all of which are pressuring Ollie’s lower-income customers. Investors should remember that Ollie’s Bargain Outlet is an off-price merchant akin to TJX Companies (NYSE: TJX), rather than a discount retailer or dollar store. It is not locked into any single product or category and can adapt to trends by opportunistically offering shoppers bargains as they emerge. The primary downside is that its treasure-hunt strategy does not translate well to digital sales, which are a pillar of today’s retail environment. . |


Tidak ada komentar:
Posting Komentar