According to a tech expert who helped manage $200 million for billionaire Steve Cohen's fund (owner of the New York Mets)... and who's personally met Elon Musk... the biotech stock that could soar next is NOT Moderna, Merck, or any stock you might expect.
The #1 play right now is a very different kind of company – directly tied into this story.
It holds the key to a new tech that could make Moderna and Merck's accomplishment look small by comparison...
This tech:
Is already backed by billionaires Elon Musk, Sam Altman, Jeff Bezos, and Peter Thiel.
Nvidia CEO Jensen Huang says it's about to have "the most dramatic impact" on our lives.
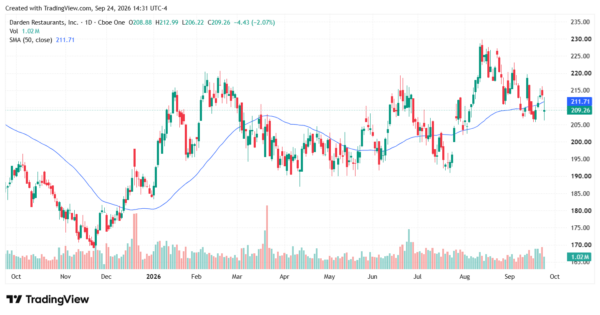
Darden’s Small Q1 Earnings Miss Masks an Olive Garden Slowdown
Posted On Sep 24, 2026 by Ian Cooper
Darden Restaurants (NASDAQ: DRI) missed Wall Street’s earnings estimates by a penny. Its revenue miss was small, too. But investors found a bigger reason to worry in the company’s latest results: Olive Garden, its largest chain, is growing much more slowly than Long Horn Steakhouse.
Table of Contents
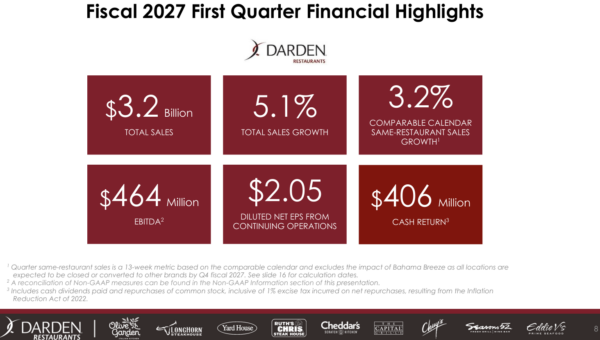
Shares of Darden fell after the company reported earnings of $2.05 per share for its fiscal first quarter. Analysts had expected $2.06. Revenue came in at $3.20 billion, compared with the $3.21 billion analysts expected. Those numbers were close to forecasts, and the company’s sales still rose 5.1% from a year earlier.
LongHorn Steakhouse was the standout. Sales at LongHorn restaurants rose 6.2% from a year earlier, making it the portfolio’s fastest-growing business during the quarter.
Olive Garden’s sales at established restaurants rose just 1.1%.
LongHorn’s strength is good news. The chain generated about $861 million in quarterly sales, up from roughly $776 million a year earlier. But Olive Garden remains much larger, bringing in nearly $1.33 billion during the quarter. That makes even a modest slowdown at Olive Garden important to Darden’s overall performance.
Olive Garden is still growing, and its sales increased from a year ago. The concern is the pace. When investors look at a restaurant chain this large, they want to see that existing locations can keep attracting customers and growing sales. A 1.1% gain leaves less room for comfort than LongHorn’s 6.2% increase.
The results do not tell us exactly why customers responded differently to the two chains. Diners may be more selective about eating out, but the company’s sales figures alone cannot show what is driving each decision. What they do show is that LongHorn currently has much stronger momentum.
The Rest of Darden Delivers
There was good news elsewhere in the portfolio. Same-restaurant sales rose 1.6% in its fine-dining division, which includes The Capital Grille and Ruth’s Chris Steak House. Its other-business group posted 3.8% growth.
Across the company, same-restaurant sales increased 3.1%. In other words, every business unit grew during the quarter. LongHorn led the way, while Olive Garden delivered the smallest increase among the groups Darden reported.
There is one wrinkle in the year-over-year comparison. The company’s fiscal calendar shifted by a week because the company moved from a 53-week year to a 52-week year. Comparing the same calendar weeks puts Olive Garden’s growth at 1.0% and LongHorn’s at 6.8%. Either way, the difference between the chains is clear.
Profit Tells a Different Story
Darden reported net income of $233.4 million, down from $257.8 million a year earlier. That drop can seem confusing when sales are rising, but last year’s reported profit included a gain from the sale of Olive Garden Canada.
Removing that gain and other adjustments gives a clearer comparison. The company earned an adjusted $1.97 per share from continuing operations a year ago, compared with $2.05 this quarter. On that basis, earnings per share rose 4.1%.
The company also kept its full-year outlook unchanged. The company expects fiscal 2027 earnings from continuing operations of $11.10 to $11.35 per share, with total sales of $13.60 billion to $13.75 billion. Management’s decision to stick with that forecast suggests it still expects the business to meet its goals after the first quarter.
For investors, the next report will offer a useful test. LongHorn is performing well, and Darden’s smaller businesses are adding growth. If Olive Garden picks up speed, the company’s results could look stronger across the board. If its growth stays near 1%, LongHorn and the other chains will have to keep doing more of the work.
That is why this earnings report is about more than a one-cent miss. Darden is growing, but its biggest chain is moving slowly. Investors will be watching to see whether Olive Garden can close some of the gap.
Today’s editorial pick for you
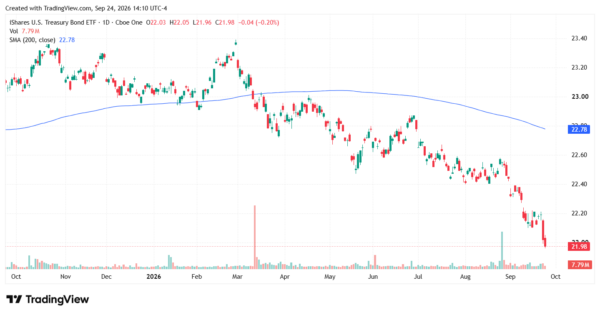
Treasury Yields Are Rising – Why That Matters Beyond Washington
Posted On Sep 24, 2026 by Ian Cooper
A jump in Treasury yields can sound like a problem for bond traders and the federal government. For households, the effects are easier to recognize: a higher mortgage payment, a more expensive car loan or a credit card balance that takes longer to pay off.
Table of Contents
Those costs are back in focus after Treasury yields rocketed higher. The 10-year yield briefly reached 5.125%, while the two-year yield climbed above 4.9%. Investors were weighing fresh inflation pressure, the possibility of another Federal Reserve rate hike in October and signs of weak demand at a five-year Treasury auction.
Thomas Wood says his Opening Bell Breakouts Trade Guide will not remain free much longer. The guide shows how to find one high-probability trade in the first 15 minutes of the day, execute it with as little as $75, and potentially be finished by 10:00 AM.
Once his upcoming paid course launches, Wood says the free guide will be removed permanently.
The 10-year Treasury yield is a key reference point for longer-term loans, especially mortgages. Mortgage rates do not move in lockstep with it, but a sustained rise in Treasury yields can push home financing costs higher.
That is already a concern for buyers. Mortgage News Daily put its average 30-year fixed rate at7.26% on September 23, up from 7.17% the day before and 6.37% a year earlier.
Even a small rate change matters when it lasts for 30 years. On a $400,000 mortgage, a move from 7% to 7.25% adds roughly $67 to the monthly principal and interest payment. That may seem manageable on its own. Add property taxes, insurance and other household bills, and it can be enough to put a home out of reach.
Higher rates can also discourage existing owners from moving. Someone with a much cheaper mortgage may hesitate to sell if buying another home means taking out a new loan at today’s rate. That can leave buyers with fewer homes to choose from.
The two-year Treasury yield tells a somewhat different story. It tends to respond more closely to expectations for Fed policy. Its rise suggests investors see a greater chance that short-term interest rates will remain high or climb further.
Credit Cards and Car Loans Could Get Pricier
When the Fed raises its benchmark rate, banks commonly raise their prime rate. Many variable-rate credit cards and home equity lines of credit are tied to prime, so another Fed hike could make existing balances more expensive.
That is especially painful for people who carry a credit card balance from month to month. Their required payment may change only a little, while more of it goes toward interest instead of reducing what they owe.
Car buyers face a similar squeeze, although auto loan rates depend on more than Fed policy. If monthly payments rise, some shoppers will choose a less expensive vehicle, keep their current car longer or delay buying altogether.
Those individual decisions add up. Slower spending can eventually affect car dealers, homebuilders, retailers and the workers they employ. Higher borrowing costs are one way that interest rates cool an economy, but they can also put pressure on families already managing tight budgets.
Will Savers Finally Benefit?
Higher interest rates do offer an upside: people buying newly issued Treasury securities may earn more, and some banks may offer better rates on deposits.
The benefit depends heavily on where savers keep their money. Rates on ordinary savings accounts can lag behind changes in market yields. Someone earning a modest return on a bank account may see little improvement, even as the rates on a mortgage or credit card rise quickly.
Banks face a mixed picture as well. They may earn more on some loans and investments, particularly if the rates they pay depositors rise more slowly. But higher borrowing costs can reduce demand for new loans. They can also make existing bonds held by banks less valuable and increase the risk that financially stretched borrowers fall behind.
Stocks To Watch as Treasury Yields Rise
Higher Treasury yields do not affect every stock the same way. Financial companies can have more opportunities to earn income on loans and interest-bearing assets, although the benefit depends on deposit costs, loan demand and the shape of the yield curve.
For investors focused more directly on the benefits of higher rates to insurers, Chubb (NYSE: CB) is another name worth watching. Insurers invest the premiums they collect, meaning higher yields can eventually provide more income on their investment portfolios as assets mature and are reinvested.
That does not mean higher yields automatically make financial stocks attractive. The impact depends on how quickly rates rise, whether the yield curve remains favorable and whether higher borrowing costs begin to weaken economic activity. Investors therefore need to consider both the potential benefits of higher rates and the pressure they can put on credit quality and demand.
The Economy Faces a Balancing Act
The recent rise in yields has come while the economy still appears strong. The Atlanta Fed’s GDP Now model estimated third-quarter growth at a 5.1% annualized rate in its September 17 update. That is a forecast, not a final reading, and it can change as new data arrives.
Strong growth can help households and businesses handle higher rates for a while. The question is how long they can do so if borrowing costs keep rising.


Tidak ada komentar:
Posting Komentar