KB Home Finds a Bright Spot as Its Backlog Starts Growing Again
Posted On Sep 23, 2026 by Grayson Cavern
KB Home’s backlog just grew for the first time in four years, even as the company sold fewer homes, delivered fewer homes and watched buyers become more cautious.
Table of Contents
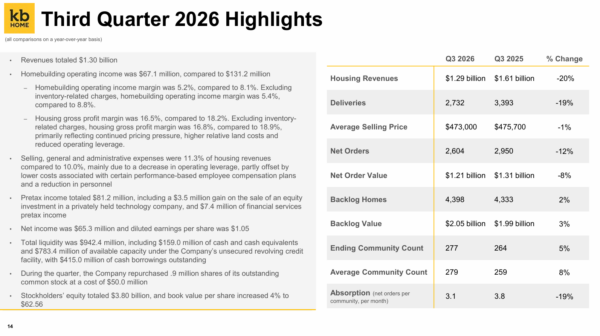
That combination tells me more about KB Home (NYSE: KBH) than the $1.05 in diluted EPS because it shows exactly where the business is improving and where the housing market is still pushing back. Third-quarter revenue fell 20% to $1.30 billion, deliveries fell 19% to 2,732 homes and net orders fell 12% to 2,604, yet ending backlog increased 2% to 4,398 homes worth $2.05 billion, up 3%.
You’ll discover that KBH is rebuilding visibility through its Built-to-Order model, but the backlog grew because deliveries fell faster than orders, not because demand suddenly accelerated.
The Backlog Is Growing Because the Business Is Moving Slower
The order numbers make the first part of this story clear. KBH generated 2,604 net orders during the quarter versus 2,950 a year earlier, while monthly net orders per community dropped to 3.1 from 3.8 and cancellations increased to 18% from 17%. At the same time, the company delivered 2,732 homes, 661 fewer than the 3,393 delivered in last year’s third quarter, allowing the remaining backlog to expand even with fewer new orders coming in.
That changes how I read the 4,398-home backlog. It gives KBH more homes already contracted and waiting to become revenue, but it does not show that buyers suddenly returned to the market. KBH said housing conditions weakened since its June earnings report as higher mortgage rates pressured affordability and broader economic and geopolitical uncertainty made prospective buyers more cautious.
There is also a clear regional split inside that backlog. The West Coast finished the quarter with 1,589 homes worth $1.02 billion, compared with 1,294 homes worth $834 million a year earlier, while the Southwest, Central and Southeast all carried fewer backlog homes than they did last year.
All of which makes the backlog more useful as a visibility metric than as a demand signal, and it leads directly to the part of KBH’s business that is changing the quality of that visibility.
BTO Is Giving KBH More Control Over Its Capital
Nearly three-quarters of third-quarter deliveries came from Built-to-Order homes, and management said the higher BTO mix contributed to sequential improvement in housing gross profit margin. KBH has also expanded its community footprint, with average communities up 8% to 279 and ending communities up 5% to 277, giving the company more places to sell even while demand remains soft.
BTO also changes when KB Home commits capital relative to when it gets a buyer. With more homes sold before construction, the company can match construction activity more closely to actual orders instead of building as aggressively ahead of demand. The balance sheet shows some evidence of that shift: inventory increased 5% to $5.98 billion, while lots owned or under contract declined 5% to 61,581. KBH did spend $722.3 million on land and land development during the quarter, 40% more than a year earlier, but nine-month land-related investment still fell 8% to $1.79 billion.
That leaves KBH carrying more backlog without simply loading up on land and inventory, which is the kind of operating change a homebuilder needs when buyers remain cautious. The catch is that better capital control has not yet repaired the economics of each home.
Pricing Pressure Is Still Eating Into The Margin
Third-quarter housing gross profit margin fell to 16.5% from 18.2%, or 16.8% from 18.9% after excluding inventory-related charges, with KBH pointing to continued pricing pressure, higher relative land costs and reduced operating leverage. SG&A also rose to 11.3% of housing revenue from 10.0%, leaving homebuilding operating income at $67.1 million versus $131.2 million a year earlier.
The nine-month figures show how deep that pressure has run. Revenue fell to $3.49 billion from $4.54 billion, deliveries declined 19% to 7,497, average selling price dropped 5% to $462,900, and net income fell to $126.1 million from $327.3 million. Diluted EPS came in at $2.00 versus $4.60.
KBH expects the fourth quarter to improve sequentially, with 3,000 to 3,500 deliveries and $1.45 billion to $1.65 billion of housing revenue, but the gross margin guide of 16.0% to 16.6% still leaves profitability below where it stood a year ago. Full-year housing gross margin should land at 16.0% to 16.2%, alongside $4.90 billion to $5.10 billion of housing revenue.
That leaves KBH with a specific job: turn the better BTO mix and larger backlog into higher-quality revenue before pricing pressure erodes the benefit.
KBH Needs the Numbers to Catch Up
The chart adds another layer to the setup. KBH sits around $47.91, below its 20-day moving average near $50.62, its 50-day near $54.10 and its 200-day near $55.65, after falling from roughly $62 in July and breaking the rising support line that had carried the shares higher from the spring.
Yet KBH reported book value of $62.56 per share at August 31, up 4% year over year, while repurchasing $175 million of stock during the first nine months, including $50 million during the third quarter. The company still had $725 million available under its current repurchase authorization.
I would watch the operating numbers rather than try to call the bottom from the chart. The backlog has started growing again, BTO now dominates deliveries and inventory growth remains contained, but orders per community, cancellations, pricing and margins still show a housing market making growth expensive.
KBH has rebuilt some visibility into the business. The next step is proving that those 4,398 homes can become profitable revenue without giving the margin back along the way.
Today’s editorial pick for you
UBS Sees an Opportunity in CoreWeave Stock
Posted On Sep 23, 2026 by Ian Cooper
CoreWeave (NASDAQ: CRWV) sits at the center of two big Wall Street debates. Investors are excited about the demand for artificial intelligence (AI) computing power. They are also worried about how much money CoreWeave must borrow and raise to meet that demand.
Table of Contents
Unfortunately, the worries won, sending the stock down about 18% over the last three months. However, according to analysts at UBS, the pullback has created an opportunity. It’s why the firm just initiated a buy rating with a $120 price target on the stock.
This debate is not unique to CoreWeave. Other AI-focused cloud companies, including Nebius Group (NASDAQ: NBIS), IREN (NASDAQ: IREN) and Applied Digital (NASDAQ: APLD), are also attracting investor attention as demand for specialized AI infrastructure expands. Their different business models give investors another way to assess the potential—and risks—of the neocloud market.
UBS analyst Karl Keirstead acknowledges the concern about CoreWeave’s debt. His view is that investors may be paying too much attention to the financing risk and too little attention to the demand for the company’s services.
In the biggest federal push since the Apollo program that landed on the Moon... Trump is now pouring the full support of the federal government into a new type of AI that could soon be worth 500 times more than ChatGPT.
It works 10,000 times faster than human PhDs... and Elon Musk calls the underlying tech "the most disruptive force in history.
Think of it this way: An AI company may need substantial computing capacity, but building and operating its own data centers takes time, money, equipment and electricity. CoreWeave does that work and sells access to the resulting capacity.
The more companies train AI models or put AI tools to work, the greater the potential demand for computing services. UBS believes that demand extends beyond the best-known AI labs. Businesses across other industries could become a growing source of customers as they adopt AI.
That puts CoreWeave in the same broader investment conversation as other so-called neocloud providers. Nebius, IREN and Applied Digital are pursuing opportunities tied to the rapidly expanding need for AI computing capacity, although their infrastructure footprints, customer bases and financing strategies differ. For investors, the comparison highlights a central question across the group: how much revenue and cash flow can each company generate from the expensive infrastructure it is building?
Why Has the Stock Pulled Back?
Meeting that demand is expensive. CoreWeave needs to secure data centers, power and computing equipment before it can deliver capacity to customers. That means spending heavily today in hopes of collecting substantial revenue later.
Its latest financing plans brought the issue back into focus. On September 17, CoreWeave proposed a $3 billion convertible debt offering. The company subsequently priced an upsized $3.7 billion offering. Convertible debt is borrowing that may, under its terms, be converted into shares. It can help a company raise capital, but it also raises questions about future dilution for existing shareholders.
Why UBS Is Still Bullish
Keirstead believes the market may be underestimating how durable AI computing demand could be. In the UBS comments provided, he also points to stronger GPU pricing, the prospect of generating more revenue from each gigawatt of capacity, and CoreWeave’s reputation for performance. UBS estimates that CoreWeave could eventually lift that figure from roughly $11 billion to more than $15 billion.
That is an analyst projection, not a result CoreWeave has already achieved. Still, it explains the bullish case: If the company can earn more from the infrastructure it builds, today’s spending may look more attractive over time.
UBS is essentially betting that demand and pricing will strengthen enough to outweigh investors’ current financing concerns. The $120 target reflects that outlook; it is not a guarantee that the stock will reach it.
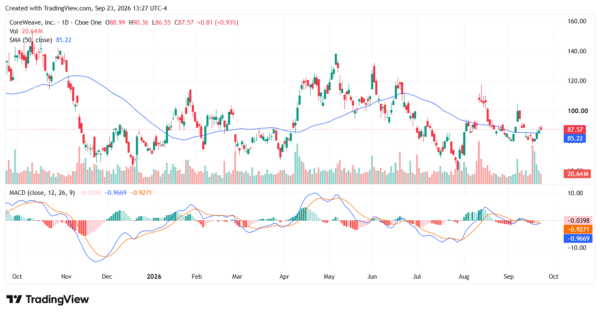
CRWV Reclaims Its 50-Day Moving Average
CoreWeave stock is showing some signs of stabilization after its recent decline. As of September 23, CRWV was trading around $87.57, slightly above its 50-day simple moving average of $85.22. That puts the stock back above an important intermediate-term trend indicator, although it has not yet established a decisive move higher.
The chart also shows near-term resistance around $90 to $95, followed by a more significant hurdle around $100. On the downside, the 50-day moving average near $85 could provide initial support, while the recent August and September lows create additional support zones in the upper-$70s to low-$80s.
The MACD remains close to the zero line, suggesting that momentum has not yet developed a strong directional signal. For CRWV, a sustained move above recent resistance could strengthen the technical picture, while a break back below the 50-day average would put the recent stabilization into question.
What Investors Should Watch Next
The next few quarters should help clarify which side of the debate has the stronger case.
Start with customer demand. Is CoreWeave continuing to sign contracts at attractive prices? Then look at execution. Can it bring new capacity online when promised and turn those commitments into revenue?
Finally, watch the cost of growth. Additional borrowing, interest payments and share sales all affect what shareholders ultimately receive from the AI opportunity.
CoreWeave offers exposure to a fast-growing market, and UBS sees its recent decline as a chance to buy into that growth. The stock’s future, however, depends on more than enthusiasm for AI. CoreWeave has to show that building more capacity creates enough value to cover the substantial bill.


Tidak ada komentar:
Posting Komentar