 A Message From Golden Portfolio In late 2023, Newmont Mining acquired Newcrest for more than $15 billion. It was the largest acquisition in gold mining history. Here's the problem: 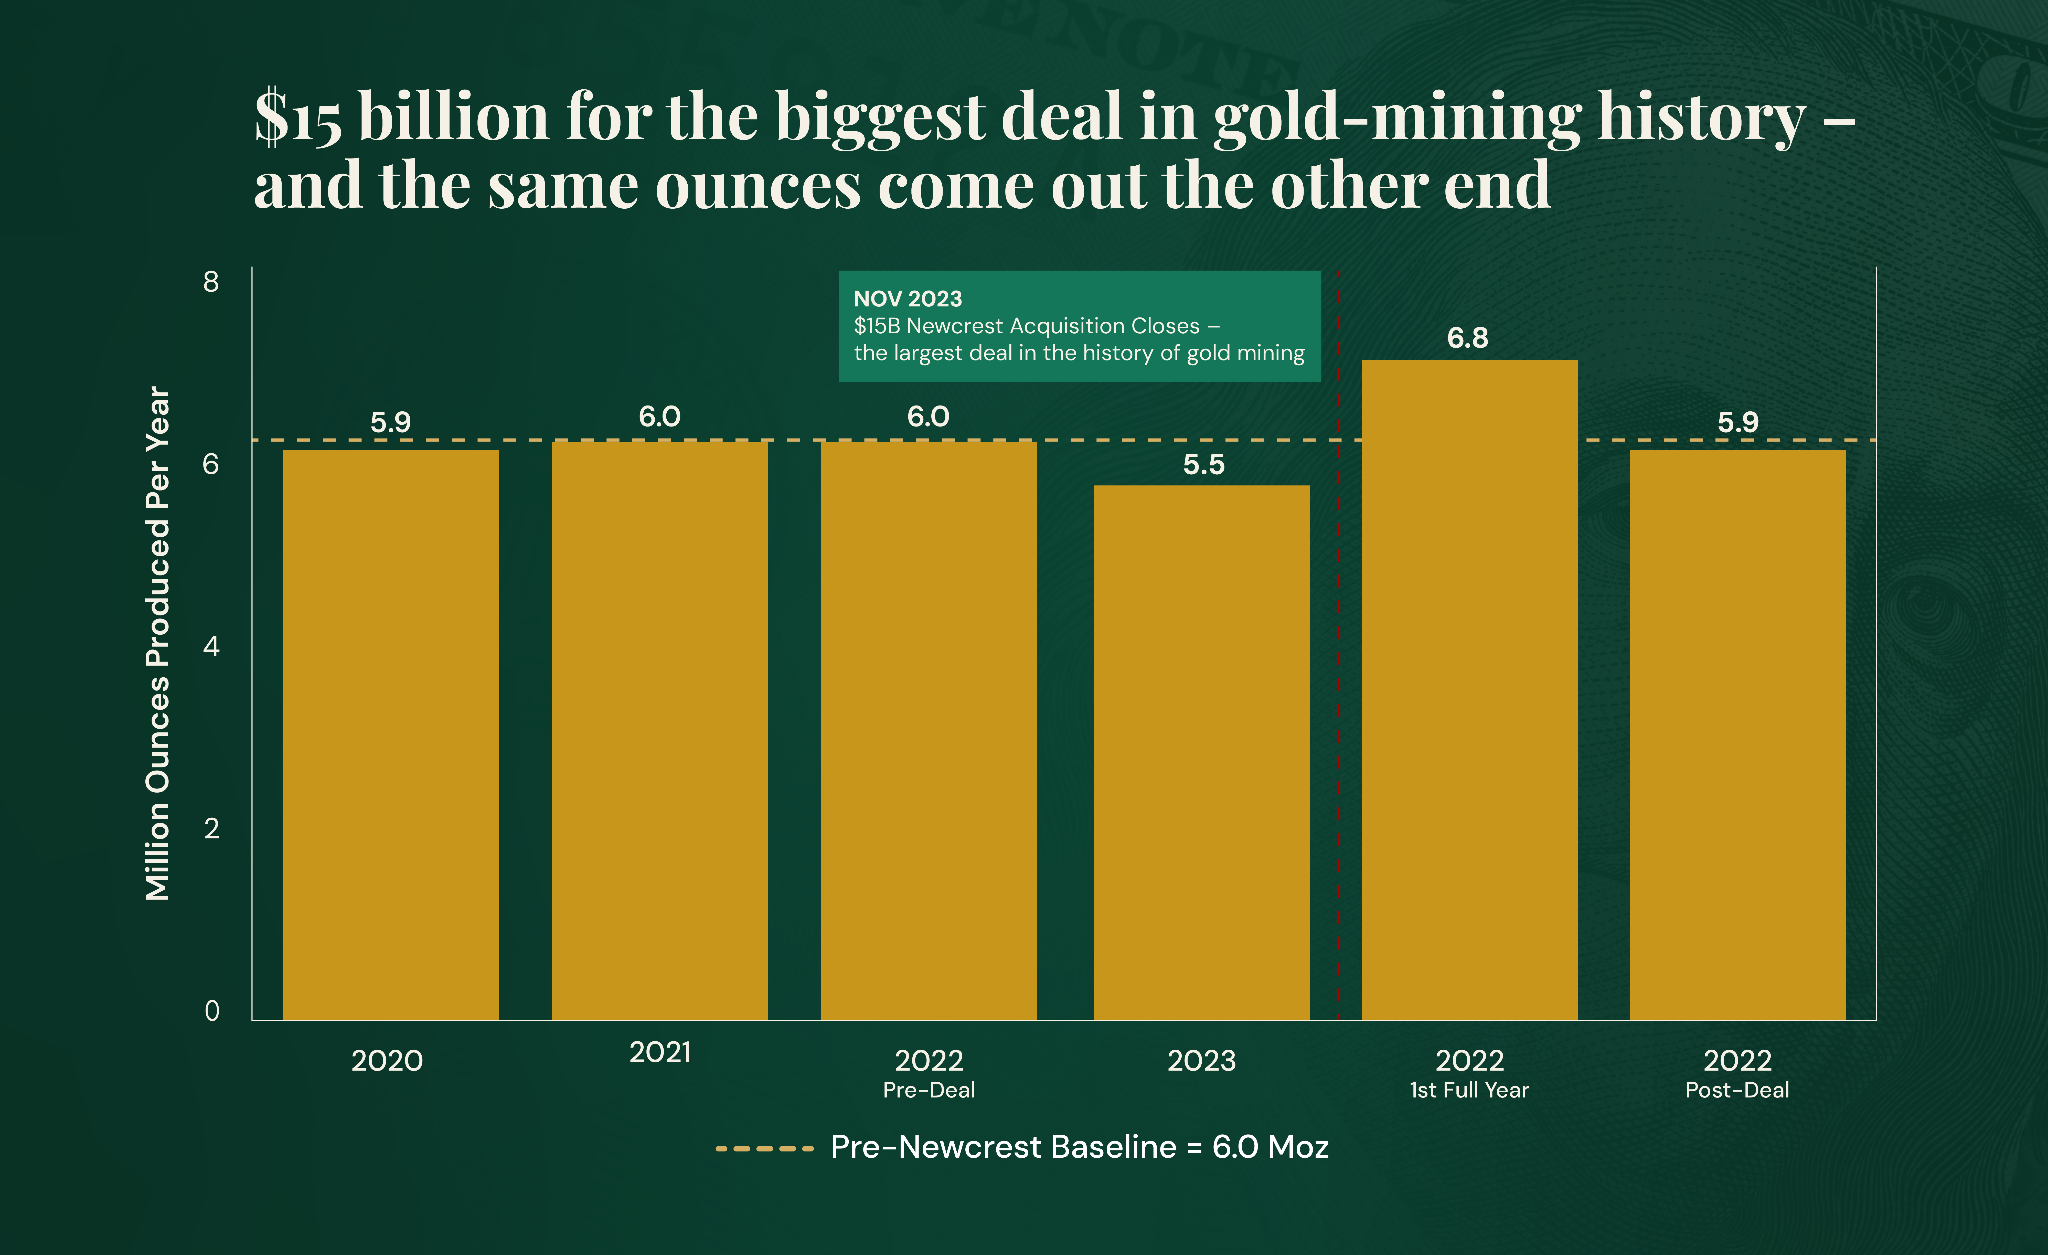
In 2020, Newmont produced 5.9 million ounces. In 2025, after spending $15 billion, it produced 5.9 million ounces. In other words… The largest gold miner on earth spent a record $15 billion — and five years on… It made absolutely no difference to their total production numbers. Either gold majors like Newmont find new sources of gold to bring to market, or they go out of business. And it's not just Newmont... The three largest gold miners all face the same problem. Gold majors like Newmont, Barrick and Agnico are running out of gold. The only way they can get more is to buy existing productive assets. That means small junior miners that are already in production. Go here and I’ll show you the top four buy-out targets If you know which junior miners are at the top of the shopping list for these cashed-up gold majors… You can collect huge overnight gains when they get acquired. Want proof? When Agnico Eagle announced it was buying Rupert Resources for $2.87 billion... Rupert popped 67% in one trading session. When G Mining Ventures announced it was buying G2 Goldfields in a $2.1 billion deal… G2 popped 79% in a single trading session. Imagine waking up to a 79% overnight gain! My name is Garrett Goggin. Porter Stansberry – author of the End of America documentary that broke the internet back in 2011 recently called me:
"THE most knowledgeable gold investor in the world. If you want to maintain your standard of living… you have GOT to be allocated to gold. And there's nobody better in the entire world to explain exactly how to do that [than Garrett]."
Go here for details on my top four buy-out targets for the current acquisition phase of this gold bull market Regards, Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio P.S. One way or another, you better own some gold if you want to maintain your lifestyle and purchasing power through the current monetary and geopolitical chaos. Why not own the best junior gold stocks – before they get bought out… and collect an overnight premium on top of your capital gain? Go here for details on my top-performing portfolio
Additional Reading from MarketBeat Media
NVIDIA’s Hugging Face Deal Raises a Bigger Question About Its AI Moat NowAuthored by Jeffrey Neal Johnson. Published: 9/3/2026. 
Key Points
- NVIDIA’s agreement to acquire Hugging Face could strengthen its position beyond data-center hardware and deepen its ties to the open-source AI developer ecosystem.
- The deal may help NVIDIA defend CUDA and its broader platform strategy as hyperscalers continue building custom AI accelerators.
- Macro risks, tariff uncertainty and valuation pressure remain real concerns, but AI infrastructure demand continues to support the long-term bull case.
- Special Report: The energy story near the Grand Canyon
Silicon alone does not guarantee a lasting monopoly. For years, the market valued NVIDIA Corporation (NASDAQ: NVDA) largely on the dominance of its data-center hardware. But the hyperscaler wars are evolving. Building the fastest chips is no longer enough as major cloud providers aggressively deploy custom accelerators. The true battleground has shifted toward ecosystem lock-in. The market is now digesting a transformative catalyst. NVIDIA has agreed to acquire the open-source AI platform Hugging Face for approximately $12.9 billion. The deal represents a vital strategic evolution, signaling a shift from a primarily hardware-focused vendor to a broader enterprise software platform.
Capturing the central hub of open-source AI models could fundamentally alter the competitive landscape. If finalized, this aggressive move to control more of the deployment layer could help neutralize threats to the CUDA architecture and redefine NVIDIA's long-term terminal value. Laying the Foundation: Pivoting From Hardware to SoftwareWhen a tech sector hardware titan targets a software repository, the goal is rarely direct revenue generation. The objective is to create friction. If developers naturally build, train and deploy their machine learning models in an environment owned by the hardware provider, switching to a competitor's silicon becomes prohibitively expensive and time-consuming. Hugging Face operates as the central nervous system for open-source AI developers. By bringing the platform in-house, NVIDIA would position itself to influence the standards of model deployment. This would shift its relationship with enterprise clients from a transactional hardware cycle to continuous software integration. The strategy could help ensure that, as the physical constraints of Moore's Law eventually catch up with advancements in the semiconductor sector, NVIDIA maintains its moat through high switching costs across the developer ecosystem. Securing the Knights: The $1 Billion Developer Retention PlanThe core purchase price of the software platform is approximately $11.9 billion, with up to $1 billion in equity-based retention awards for Hugging Face employees who join NVIDIA. That retention package is the most critical line item in the deal. Hugging Face's ultimate value lies not in its code alone, but in the trust and engagement of its active developer community. Independent developers flock to the platform because of its historical neutrality. Incorporating an open-source hub into a proprietary corporate structure poses a meaningful risk of triggering a developer exodus. By locking in the original engineering team with substantial financial incentives, NVIDIA aims to preserve the platform's culture and prevent competitors from spinning up a viable alternative repository. Controlling this developer base would allow engineers to optimize foundational open models directly for the CUDA architecture, establishing a stronger walled garden. Filling the Moat: A Nearly $13 Billion Price TagAcquisitions of this magnitude often strain balance sheets, but the capital allocation strategy here is distinctly aggressive yet entirely manageable. NVIDIA generates quarterly revenue exceeding $96 billion and net margins above 63%, so it can absorb an approximately $12.9 billion transaction without compromising its liquidity profile. The acquisition represents a redirection of abundant free cash flow into a high-leverage strategic moat rather than a heavy financial burden. Arming the Sentinels: Defending the Moat on 2 FrontsThe most credible bearish argument against NVIDIA has always been the rise of custom silicon. Cloud hyperscalers are aggressively funding their own AI accelerators to reduce their dependence on expensive third-party GPUs. The Hugging Face acquisition is only half of the defense strategy. Recently, NVIDIA invested about $3.5 billion in a convertible bond in MediaTek. This capital injection is designed to revive the Rubin CPX custom-chip program, directly defending NVIDIA's market share in the custom-silicon space. By simultaneously buying the premier software deployment layer and funding custom hardware alternatives, management is executing a dual-pronged defense against hyperscaler independence. Competitors attempting to circumvent traditional data-center GPUs will now find themselves battling optimized software standards on one front and well-funded custom hardware on the other. Guarding the Gates: NVIDIA Overrides Policy NoiseEven structurally dominant organizations operate within the physical economy, and peripheral risks require attention. A recent global bond sell-off has pushed long-term U.S. Treasury yields higher. Elevated yields naturally pressure the valuation multiples of high-growth technology equities. With a beta hovering around 2.22, NVIDIA remains sensitive to macroeconomic volatility. Adding to the friction, U.S. Commerce Secretary Howard Lutnick recently commented on forthcoming semiconductor tariffs. Broad trade policy shifts introduce immediate uncertainty into global supply chains and hardware pricing models. Despite these genuine macroeconomic headwinds, underlying physical demand continues to offset policy noise. Recent earnings from infrastructure giants such as Dell Technologies (NYSE: DELL) revealed raised guidance and substantial enterprise spending on AI servers. Hyperscalers are not slowing their capital expenditures. Secular demand for compute power provides a robust buffer against short-term interest-rate and tariff fluctuations. The New Kingdom: Structuring Your Portfolio for SoftwareWall Street traditionally assigns cyclical, conservative multiples to semiconductor hardware manufacturers. Hardware businesses are capital-intensive and subject to brutal inventory cycles. Software platforms, conversely, command premium multiples because of their recurring revenue, high margins and immense scalability. By acquiring Hugging Face, NVIDIA is effectively beginning a transition from the former to the latter. The market is slowly realizing that NVIDIA is no longer just a chipmaker; it is becoming more of a foundational operating system for artificial intelligence. This structural pivot provides substantial fundamental support for institutional price targets. The current consensus price target is around $324, representing healthy upside, while some aggressive analysts project targets approaching $515. Short interest remains at manageable levels, indicating that institutional bears lack the conviction to bet against this strategic pivot. Investors might want to add NVIDIA to their active watchlists and use any tariff-induced price pullbacks as strategic entry points before the Hugging Face acquisition fully materializes and software multiple expansion takes hold. . |


Tidak ada komentar:
Posting Komentar