You're probably hearing all kinds of wild rumours about the best way to play AI right now...
The SpaceX IPO created 4,400 new millionaires... and OpenAI is reportedly planning its own $1 trillion IPO as early as this fall, which is expected to create even more overnight millionaires...
While early holders of Nvidia have had the chance to make millions of dollars on just one stock. (One schoolteacher in New Hampshire retired early after making $2,545,000 on the stock.)
MIT says right now is the best time in history to become wealthier, thanks to AI.
But the truth is...
The best way for ordinary folks to take advantage from what's happening isn't to speculate on AI IPOs... or try to guess which stock will be the "next Nvidia".
P.S. Sam Altman says AI will be "as essential as electricity" in the future. That's a very grand claim. But it doesn't tell you where your money should be for the best chance to profit and avoid falling behind.
That's why I'm urging you to try our new AI tool now and potentially grow your money 10x using just five stocks.
COST Q4 Earnings: Strong Sales Face a Tougher Stock Market Test
Posted On Sep 21, 2026 by Grayson Cavern
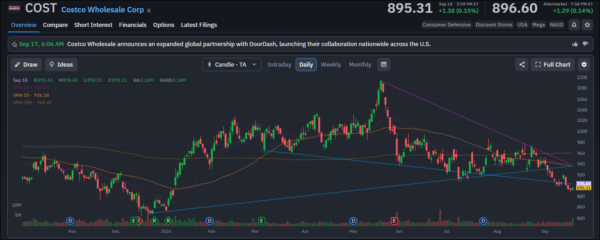
Costco Wholesale Corp. (NASDAQ: COST) has already done the part of this earnings setup that usually gets investors excited by showing that the customer is still spending. But the stock has been doing the opposite. COST closed at $895.31 on Sept. 18, well below the roughly $1,096 May peak, while fiscal Q4 sales came in at $93.9 billion, up 11.3%.
Table of Contents
So the setup is pretty simple: the business is still growing hard, but the underlying sales rate has cooled, and now the market has to decide how much premium it wants to keep paying for that growth.
May was the monster month, with comparable sales up 12.5% and 8.0% after stripping out gasoline and foreign exchange. June slowed to 8.8%, or 7.0% ex-gas and FX; July came in at 8.9%, or 6.6%; and August finished at 8.4%, or 5.4%. The full fiscal Q4 landed at 9.4%, with the cleaner ex-gas/FX number at 6.7%. Digital was still flying, with digitally enabled Q4 comps up 19.5%.
That progression is the number I would keep on the screen going into the print. Headline comps remain high, but the underlying rate moved from 8.0% in May to 5.4% in August. Some August softness was calendar noise because Costco said the later Labor Day reduced August sales by a little less than 75 basis points. Still, the sequence shows a business coming off its spring pace.
And this is where traders can get caught leaning the wrong way. Costco has already told the market that people are spending. Buying the stock because the sales number looks strong after that number is already public is chasing a known fact. The fresh information is what those sales produced for earnings.
The Membership Engine Is The Cushion
Looking at the recurring revenue underneath the merchandise business, earlier fiscal 2026 numbers showed $1.373 billion of quarterly membership fees, up 10.7%, with 82.9 million paid memberships. Renewal rates were 92.2% in the U.S. and Canada and 89.7% worldwide, while Executive memberships reached 41.2 million. Operating cash flow hit $11.133 billion through the first 36 weeks, versus $9.468 billion a year earlier.
I would read that less as another “membership is great” bullet point and more as the cushion underneath the retail machine. If merchandise comps cool, recurring membership revenue and cash generation give Costco another lever to keep the earnings engine moving. But investors already know this part of the story. The earlier valuation work put COST around 48 times trailing earnings and 42 times forward earnings, meaning a lot of durability was already priced in.
So Thursday is less about proving Costco is a great business. The trade is about whether the earnings can keep the premium from getting squeezed as the sales rate cools.
Don’t Let The Earnings Setup Fool You
There are a few classic mistakes sitting all over this setup.
First, anchoring to the 9.4% Q4 comp and ignoring the 6.7% ex-gas/FX figure. Both are useful, but they answer different questions. Gasoline and currency can move the headline; the cleaner figure gives you a better read on the underlying retail machine.
Second, treating the consensus EPS number as the finish line. If COST clears the estimate but margins or the forward tone disappoint, the stock can still get hit because traders are repricing what comes after the quarter. A beat is not a trade thesis by itself.
Third, buying the chart before the chart confirms anything. COST is below its 20-day average of around $924.60, its 50-day average of around $936.54 and its 200-day around $960.42 on the chart provided. That puts roughly $925-$940 in the first recovery zone, with $960 as the bigger test. Buying calls simply because the sales numbers look good is a different trade from waiting to see whether buyers actually show up.
And I’d not build the thesis around a special $15 dividend rumor either. A payout can move sentiment, but it does not fix a cooling sales rate or give the business a cheaper valuation.
What I Want From COST Thursday
My scoreboard going into Thursday is simple: Costco has to show that the $93.9 billion Q4 sales haul converted into enough profit and cash to keep the premium attached to the stock. The sales engine is still running. The issues are the direction of the underlying comp, the ability to protect profitability as the business scales, and whether membership economics continue to provide that cushion. So I would rather see the stock tell me what the market thinks than guess beforehand. A clean reclaim of the moving averages would change the chart. A failure there would keep the May peak firmly in the rearview mirror.
Today’s editorial pick for you
NVIDIA’s Next Growth Phase Could Be Even Bigger Than Expected
Posted On Sep 21, 2026 by Ian Cooper
NVIDIA (NASDAQ: NVDA) CEO Jensen Huang raised expectations again. At an artificial intelligence summit in Scotland, Huang said he expects NVIDIA to sell twice as many chips next year as it does this year. That is a substantial forecast for a company already producing and shipping millions of advanced processors to customers around the world.
Table of Contents
The reason, according to Huang, is simple: Artificial intelligence is becoming increasingly valuable to businesses, industries and entire economies. Companies and governments are investing heavily in the technology because they believe it can improve productivity, accelerate research and create new products and services.
For NVIDIA investors, Huang’s prediction offers another indication that the AI infrastructure boom may still have plenty of room to run.
NVIDIA recently projected revenue growth of more than 70% for the fiscal year ending in January 2028. The outlook was strong enough to push analysts’ estimates higher and reinforce Nvidia’s position at the center of the AI economy. Now, Huang’s prediction that chip volume could double adds another bullish layer to the story.
In addition, company growth is no longer dependent on a single product. Its graphics processing units, or GPUs, receive most of the attention, but the company’s opportunity is much broader.
NVIDIA Is Selling More Than GPUs
NVIDIA’s Blackwell and next-generation Rubin processors are designed to train and operate increasingly sophisticated AI systems. Last year, Huang said the company had shipped six million Blackwell GPUs in four quarters.
NVIDIA also sells central processing units, networking switches, optical-networking components and other chips needed to connect thousands of processors inside data centers. The company supplies Jetson systems for robots and autonomous machines, chips for laptops and automotive technology, and the processor used in Nintendo’s Switch 2 console.
Also, analysts say NVIDIA’s upcoming Vera Rubin platform and expanding line of CPUs and networking products could help drive shipment growth in 2027. Some industry estimates suggest the chip maker could ship approximately 70,000 to 80,000 advanced server racks during 2026, although the company has not confirmed those figures.
The Global AI Race Is Getting Bigger
Huang’s comments also highlight why he remains so optimistic: AI investment is becoming a global priority. The United States is leading much of the current spending, but it is hardly alone. Countries across Europe, Asia and the Middle East are developing domestic AI infrastructure.
That does not mean NVIDIA’s path will be perfectly smooth. Doubling shipments will require substantial manufacturing capacity, advanced memory, sophisticated packaging and electricity and data-center infrastructure. Competition from AMD, custom chips developed by major cloud providers and Chinese semiconductor companies could also intensify.
Still, the company’s recent results and outlook suggest that demand remains stronger than supply in several areas. Some Wall Street analysts have even raised the possibility that the company could eventually generate $1 trillion in annual revenue if AI spending continues expanding at its current pace.
NVDA’s Next Growth Phase Could Be Massive
For now, Huang sees no shortage of demand. If NVIDIA can come close to doubling its chip shipments while delivering its projected revenue growth, the company’s expansion may be far from finished. The larger question is no longer whether the world wants more AI computing power. It is whether NVDA and the rest of the technology industry can build it fast enough.
Of course, expectations this high also create risks. NVIDIA will need to secure enough manufacturing capacity, advanced memory and power infrastructure to keep pace with demand. It must also respond to growing competition from Advanced Micro Devices (NASDAQ: AMD), custom chips developed by major technology companies and emerging semiconductor manufacturers in China.
Still, NVIDIA has repeatedly demonstrated its ability to turn rising demand for computing power into substantial revenue growth. The company is no longer simply a manufacturer of high-performance graphics chips. It has become one of the most important suppliers of the hardware, networking technology and software needed to build and operate AI systems.


Tidak ada komentar:
Posting Komentar