 A Message From Chaikin Analytics Editor's Note: Marc Chaikin's last major recommendation for our readers drew a huge response. Today he's back with a new #1 retirement pick — and he's sharing the details free, no email or credit card required.
Dear Reader, In 2014, I recommended my readers put a big chunk of their retirement money into one stock: Nvidia. Anyone who followed that recommendation is up more than 45,000% at this point. I've spent 60 years on Wall Street. I built one of Wall Street's most well-known tools – Chaikin Money Flow indicator. Even Jim Cramer said he's learned never to bet against me given my decades long track record of picking stock market winners. Now I've unearthed what I believe could be an even better retirement stock for the years ahead — and today I'm going to share the details, totally free of charge. (Click here to get the specifics.) Here's the single biggest reason why. This company is sitting on three fast-growing businesses, and each one could be spun off into a separate publicly traded company. If that happens — and I believe the next 12 to 24 months are when it could — anyone holding this stock beforehand could have those spinoff shares deposited into their account automatically. In other words, one ticker today could become three tickers tomorrow. That's the kind of setup that almost never appears in a stock this size. And Wall Street still considers this company a "dark horse" in the AI race. It shouldn't when its autonomous vehicle division is already being called the "undisputed leader" against Tesla. And it's streaming service has 10X greater reach than Netflix. Yet most investors have no idea it's even in those businesses. The market is pricing this as one ordinary company instead of three extraordinary ones. There's also a dividend — which is rare for a high-growth technology company. Most AI names pay nothing at all. In my new presentation, I explain everything you need to know — including why a major event that just occurred in AI's frontier labs put this company at the top of my buy list. That's why I believe this might be the greatest retirement stock in America right now. Click here to get the details of this amazing stock, totally free of charge. No credit card, no email required. Sincerely, Marc Chaikin
Founder, Chaikin Analytics P.S. A high-growth tech stock that pays a dividend is a rarity — this one is the exception. To be in line and claim your share of the next $2.6 billion payout, you need to own at least one share by September 4th. Click here so you don't miss the cutoff.
This Month's Featured News
Petco Is Still Being Priced Like the Old PetcoAuthor: Chris Markoch. Published: 9/7/2026. 
Key Points
- Petco stock fell 4% after its earnings report, though net income more than doubled and free cash flow improved significantly.
- The company made progress paying down debt, prepaying $170 million over nine months while pursuing a turnaround strategy CEO Joel Anderson says is gaining traction.
- Analyst ratings remain mixed with a consensus Reduce rating, though the average price target of $3.42 implies 32% upside from recent levels.
- Special Report: Bezos… DOOMED?
At a surface level, Petco Health and Wellness (NASDAQ: WOOF) looks like a company that could be a solid defensive stock in times like these. Data from the American Pet Products Association forecasts that Americans will spend $165 billion on their pets in 2026, an increase of 4.4% from 2025.
That low-single-digit growth didn't show up in WOOF's latest revenue numbers, which were flat year over year (YOY). But does that justify a 4% drop in the company's stock price? The report had some positives. More importantly, the market has been pricing the stock for failure for so long that it may be setting up an opportunity for risk-tolerant investors. The Good and the Bad From Petco's EarningsIn the second quarter of Petco's 2027 fiscal year, the company booked net sales of $1.49 billion, essentially flat compared with the year-ago period, while comparable sales rose 0.6%. That marked the second straight quarter of positive comps. Management attributed some of the top-line softness to a rockier-than-expected rollout of a relaunched membership program. Specifically, point redemptions came in heavier than anticipated right out of the gate, pulling sales forward and creating a short-term drag. That could be a sign of a stressed consumer. However, Petco said sales were tracking ahead of its internal targets before the relaunch. On the bottom line, the story looks better. Gross profit rose to $591.1 million, a 39.7% margin that was up 37 basis points from a year ago. But that improvement came with a caveat: About $6.8 million resulted from a net benefit tied to IEEPA tariff refunds. Excluding that benefit, normalized gross margin was roughly flat YOY. Operating income still climbed 11.1% to $47.8 million, and net income more than doubled to $38.7 million from $14 million in the same period last year. Adjusted EBITDA came in at $122.2 million, compared with $113.9 million a year ago, or $115.4 million on a normalized basis excluding the tariff item. Petco also made real progress on its balance sheet. First-half free cash flow improved to $60.8 million, up from just $9.9 million over the same stretch in 2025, and total debt fell to $1.48 billion from $1.59 billion a year earlier. After the quarter closed, the company voluntarily prepaid another $75 million of debt, bringing total prepayments to $170 million over the past nine months as it works toward a leverage target of 2x net debt to adjusted EBITDA. Petco's Turnaround Strategy Is Gaining TractionCEO Joel Anderson framed the results as evidence that the company's "Reach for the Sky" turnaround strategy is gaining traction, particularly in consumables. CFO Sabrina Simmons pointed to the debt prepayment as a sign that the company is balancing growth investments with deleveraging. Petco left its full-year guidance unchanged, calling for net sales that are flat to up 1.5% and adjusted EBITDA of $415 million to $430 million. The company also guided for third-quarter sales growth of 0.4% to 1.0% and adjusted EBITDA of $100 million to $103 million. Management also flagged initiatives for the back half of the year—including a rollout of Hill's Pet Nutrition fresh dog food and continued growth in cat products—as levers to reaccelerate the top line. WOOF May Be Forming a BottomIt's always tough to call a bottom for a stock. That said, the WOOF chart suggests the worst may already be priced in. Since May 2026, the stock has found support near $2.50, which is close to its closing price on Sept. 4. But concerns remain. WOOF has been trading near its descending 200-day moving average, which has also acted as resistance. Complicating things further is the lack of institutional ownership. Only about 6% of the WOOF float is sold short, but because institutional buyers are limited, traders can have an outsized influence on price action. That was the case the day after the earnings report, when the stock fell more than 4% on nearly five times its normal trading volume. 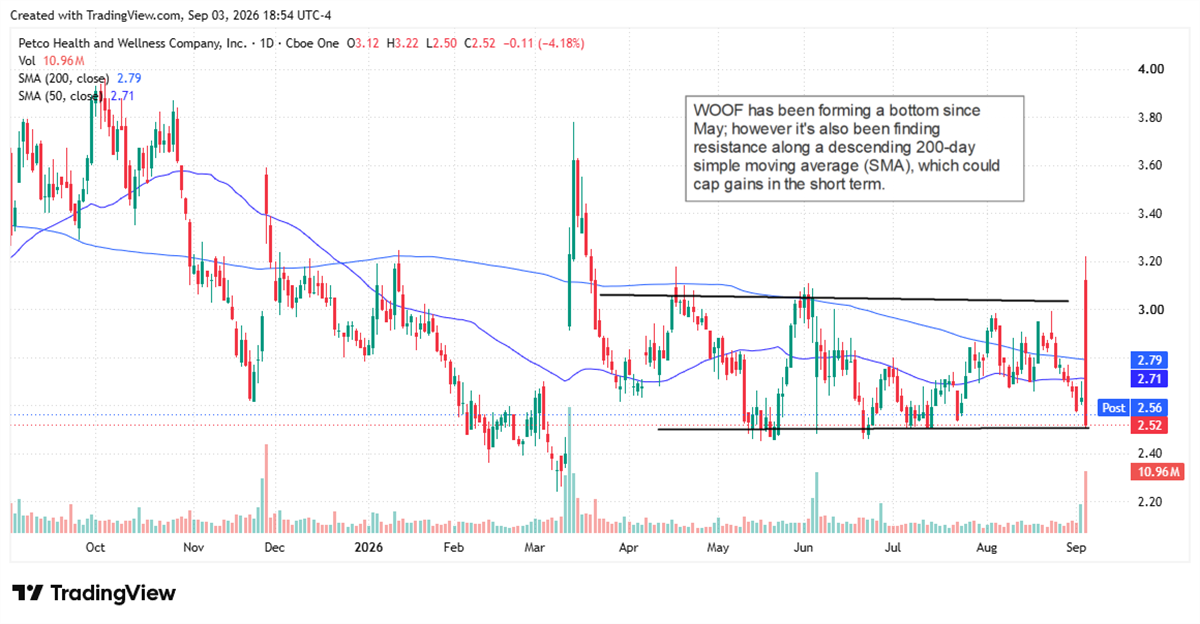
How to Approach Petco After EarningsAnalyst coverage of WOOF is light, and ratings from the group tracked by MarketBeat are mixed. Of the nine analysts, two have a Sell rating, and the consensus rating is Reduce. However, the consensus price target of $3.42 offers 32% upside. For that upside to materialize, the company will need to show strong improvement not only in margins but also in its growth investments. The bottom line is that, as much as WOOF seems like the right stock for the right time, there are better options for investors with a speculative itch to scratch.
This ad is sent on behalf of Chaikin Analytics, 201 King Of Prussia Rd., Suite 650, Radnor, PA 19087. If you would like to optout from receiving offers from Chaikin Analytics please click here.
This ad is sent on behalf of Chaikin Analytics, 201 King Of Prussia Rd., Suite 650, Radnor, PA 19087. If you would like to optout from receiving offers from Chaikin Analytics please click here.
. |


Tidak ada komentar:
Posting Komentar