Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
The new money raises NVIDIA’s remaining authorization to $235 billion. Management expects to complete the full program through fiscal 2028. The old record belonged to Apple, which added $110 billion to its buyback in 2024.
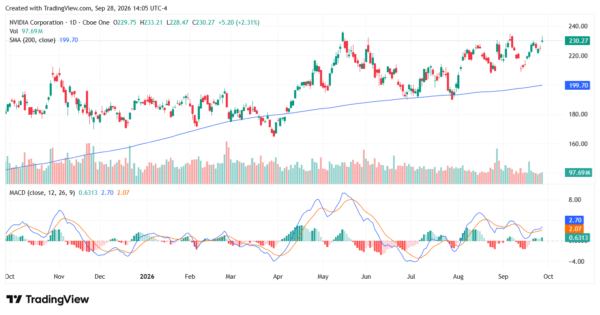
Investors cheered. NVDA shares rose 1.9% Monday morning, even as the broader tech sector slumped.
But the buyback itself is a short story. An authorization is permission, not a promise. NVIDIA will still set the pace based on its share price, cash needs, and investment plans.
The bigger story is the cash engine behind it. NVIDIA now generates enough cash to reward shareholders, fund its growth, and bankroll much of the AI ecosystem. Few companies in history have done all three at once. That raises a fair question for investors. Which other AI leaders have balance sheets strong enough to play the same game?
Buybacks say a lot about how management views its own stock. NVIDIA trades at about 24 times forward earnings, not far above the S&P 500’s 20-times multiple. That’s a modest premium for a company still doubling revenue.
This is a classic perception-versus-fundamentals gap. The market prices NVIDIA like a cyclical chipmaker nearing a peak. Management is pricing it like a platform company early in a long cycle. In the release, Jensen Huang said the authorization reflects his confidence in the long-term opportunity ahead.
Following the Cash: $70 Billion in Six Months
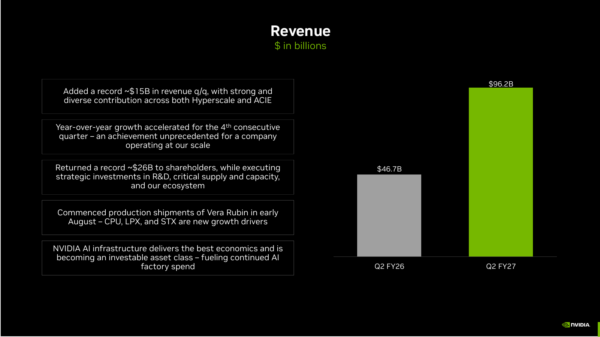
The fundamentals back up that confidence. Second-quarter revenue hit $96.2 billion, up 106% from a year ago. Free cash flow for the first six months totaled $69.9 billion.
NVIDIA returned about $26 billion to shareholders in the second quarter through buybacks and dividends. It ended the quarter with $22.4 billion in cash and $34.1 billion in marketable debt securities.
There is one wrinkle worth watching. Second-quarter free cash flow fell to $21.3 billion from $48.6 billion the prior quarter. A $22.3 billion jump in accounts receivable drove most of that decline. Growing customers are paying more slowly. Fast growth often looks like this, but it bears monitoring.
The math on the buyback is also ambitious. Spending $235 billion by early 2028 would mean more than $40 billion per quarter. That’s above NVIDIA’s average quarterly free cash flow so far this year. Notably, the company raised about $24.9 billion in new debt during the quarter.
NVIDIA Is Now the AI Economy’s Banker
Buybacks are only half of how NVIDIA deploys its cash. As of July 26, it held $99 billion in equity investments, with another $25 billion committed.
The largest stakes include OpenAI at $30 billion, Anthropic at up to $10 billion, and Safe Superintelligence at $5 billion. Some bets have already paid off handsomely. NVIDIA’s $5 billion stake in Intel was worth over $25 billion within months.
NVIDIA is also helping others finance the buildout. It partnered with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR on platforms aiming to mobilize over $500 billion in third-party capital for AI infrastructure. It also agreed to acquire Hugging Face for $12.9 billion after the quarter closed.
Critics call this circular. NVIDIA backs companies that buy its chips, which some say could inflate valuations across the sector. That concern is valid. But it is also a luxury problem. Only a company with extraordinary cash flow can fund its own customers.
Three More AI Leaders With Deep Pockets
NVIDIA isn’t the only AI company sitting on a cash fortress. But its peers are spending theirs very differently.
Alphabet: The Biggest Cash Pile, Spending Hard
Alphabet (NASDAQ: GOOGL) holds the largest war chest in the group. It had $242.5 billion in cash, cash equivalents, and short-term marketable securities as of June 30.
Yet the headline number spooked some investors. Second-quarter free cash flow was negative $5.9 billion as capital spending of $44.9 billion outran operating cash flow. In June, Alphabet also raised roughly $49.6 billion in equity and $20.3 billion in senior notes to fund AI compute.
The fundamentals tell a better story. Trailing 12-month free cash flow remained positive at $53.3 billion. Google Cloud revenue soared 82% to $24.8 billion. Its cloud backlog reached $514 billion. Alphabet is converting cash into capacity, and the demand appears to be there.
Microsoft: Positive Cash Flow Despite Record Capex
Microsoft (NASDAQ: MSFT) is walking a similar line. Fourth-quarter capital expenditures and finance leases jumped 69% to $41 billion. Even so, the company still produced $19.6 billion in free cash flow.
Operating cash flow for fiscal 2026 rose $46.8 billion to $182.9 billion. Microsoft ended the year with $76.8 billion in cash and short-term investments, plus $36.3 billion in equity and other investments.
Like NVIDIA, Microsoft is profiting from its AI stakes. It booked a $3.2 billion gain on its Anthropic investment last quarter. Management also expects to remain free cash flow positive in fiscal 2027.
Broadcom: A Cash Machine With Almost No Capex
Broadcom (NASDAQ: AVGO) looks most like NVIDIA financially. Both design chips without owning heavy manufacturing. That keeps capital needs low and cash conversion high.
Third-quarter revenue climbed 86% to $29.6 billion. Free cash flow reached $13.7 billion, or 46% of revenue, on just $0.5 billion in capex. Cash rose to $24.0 billion from $19.6 billion a quarter earlier.
AI is the engine. AI semiconductor revenue jumped 221% to $16.7 billion, with $21.7 billion expected next quarter. Broadcom still carries debt from its VMware deal. But its cash flow is growing fast enough to shrink that burden quickly.
Cash Is the New Moat
In the AI race, the balance sheet has become strategy. The companies with the most cash set the pace for everyone else.
NVIDIA stands out because it sells the picks and shovels. It doesn’t have to pour concrete for data centers. That leaves room to buy back stock, invest in partners, and still build its own business.
The market keeps debating whether AI is a bubble. The cash flows suggest something more durable. Investors should still watch receivables and circular deals closely. But a record buyback is hard to fake. It’s a bet management is making with real money.
Today’s editorial pick for you
3 Dividend Stocks That Just Delivered a Bigger Payday
60-year Wall Street veteran Marc Chaikin just issued a shocking new prediction. And if you have a PENNY invested in AI... take heed.
According to Chaikin, every U.S. AI firm now relies on massive data centers. But these monstrosities suck up our electricity. They drain our water supplies. They steal precious land.
That's why a new technology is about to make all current data centers obsolete – with the flick of a switch. And the company he believes is behind it could make early investors very rich.
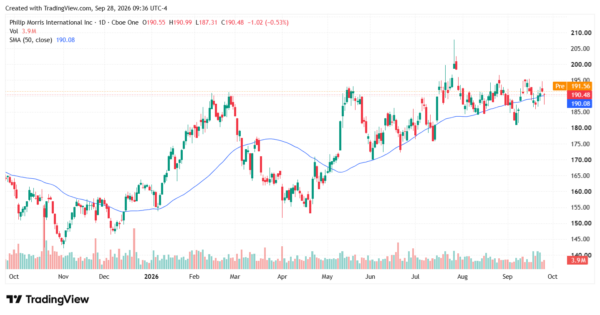
Philip Morris Raised Its Quarterly Payout to $1.60
Philip Morris raised its quarterly dividend from $1.47 to $1.60 per share. That is an 8.8% increase. That’s payable on October 26 to shareholders of record as of October 2. Philip Morris still sells cigarettes, but it has also built a growing business around products such as heated tobacco devices and nicotine pouches. Those smoke-free products brought in about 42% of its net revenue in the second quarter of 2026, according to the company.
The company also just hiked its guidance. It raised its full-year diluted EPS forecast to a range of $7.28 to $7.43. The company also updated its third-quarter adjusted diluted EPS forecast to a range of $2.29 to $2.34. The midpoint of the range, $2.315, is ahead of the estimate of $2.25.
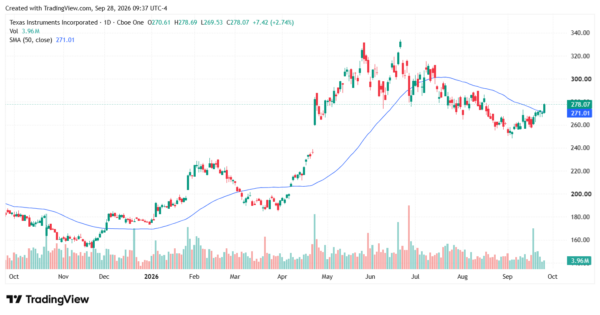
Texas Instruments Raised Its Dividend to $1.52
Texas Instruments just raised its dividend to $1.52 from $1.42. That’s payable on November 10 to shareholders of record as of October 30. Analysts at Citi also reiterated a buy rating on the stock, noting that, “We remain buyers of TXN, our top analog pick, as its manufacturing capacity should position it to capture a greater share,” as quoted by Seeking Alpha.
Earnings and guidance were also strong. In its second quarter, EPS OF $2.14 beat by 20 cents. Revenue of $5.46 billion, up 22.7% year over year, beat by $220 million. The company added that “Revenue increased 13% sequentially and 23% from the same quarter a year ago with broad growth led by industrial, data center and automotive,” as reported by Seeking Alpha. “TI’s third quarter outlook is for revenue in the range of $5.65 billion to $6.15 billion vs. $5.24B consensus and earnings per share between $2.23 and $2.57 vs. $1.95 consensus.”
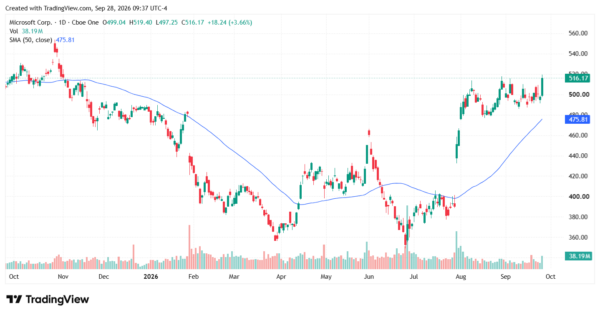
Helping, the stock was just upgraded to Buy from Hold at Stifel, as the investment firm said the tech giant is “getting back on track,” reported Seeking Alpha. “We are increasingly comfortable with the company’s ability to sustain mid/upper teens revenue growth as open-weight model advancement has boosted management’s LLM-agnostic strategy (Azure & Copilot), COGS/OPEX operational efficiencies are supportive of stable operating margins, and strong cash flows should limit the company’s need for outside financing,” they added.
The firm also increased its price target on Microsoft to $575 from $530 and added that it expects “accelerating” revenue growth in Azure.
What These Dividend Raises Mean for Investors
Dividend increases are encouraging because they put more cash in shareholders’ pockets. They can also show that a company feels confident about its ability to keep generating cash in the years ahead.
These companies give investors three different businesses to consider for income. Philip Morris is growing its smoke-free product business, Texas Instruments is seeing stronger demand across several markets, and Microsoft continues to benefit from its cloud business. Each company is also returning more cash to shareholders. And if you’re looking to build a portfolio that can pay you while you hold it, PM, TXN, and MSFT are worth a closer look.
Of course, a dividend increase doesn’t guarantee that a stock will rise. Investors still need to consider the price they’re paying and whether each company can sustain its growth. But for anyone building a portfolio with both income and long-term potential in mind, these three stocks deserve a place on the watchlist.


Tidak ada komentar:
Posting Komentar