Right now, you can buy a dollar's worth of gold for about 36 cents.
That sounds impossible. Here's how it's real.
The major gold miners are throwing off record cash flow — even after gold's recent pullback. The four largest have never had this much free cash on hand. Ever. At today's gold price, they're running margins as high as 75% — the most profitable they have ever been.
When a major gold miner makes record profits, it does one of two things: hand the cash back to shareholders, or buy the best junior mining assets to secure future production.
So the majors are staring at their own future production shrinking, sitting on record cash, looking at top-tier junior assets trading at a fraction of what that gold is worth at today's price.
They don't have a choice. They buy — or their output keeps shrinking until they're out of business.
The gap between what these assets are worth and what they trade for has a name. I call it the Golden Anomaly. It only appears early in a gold bull market, and it closes fast — usually the moment the majors start writing cheques.
So you can pay full price after the gap closes…
Or buy the dollar for 36 cents while the Anomaly still exists.
My name is Garrett Goggin, CFA, CMT, and it's why Porter Stansberry recently called me:
"THE most knowledgeable gold investor in the world."
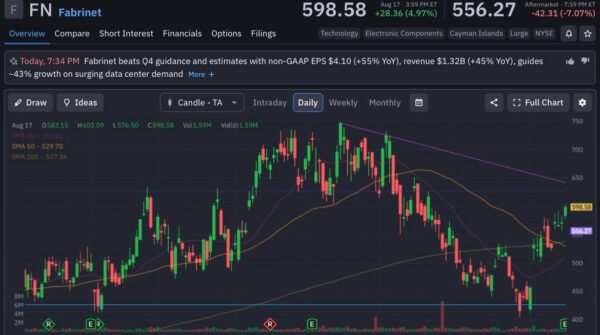
And yet the market’s reaction on was almost comically disconnected from the strength of the headline numbers: Fabrinet (NYSE: FN) closed at $598.58, up 4.97%, before falling to about $556.27 after hours, a roughly 7% reversal.
I don’t think the after-hours reversal is a verdict on Fabrinet’s demand story. It looks more like the market has spotted a bill coming due.
Fabrinet’s AI Surge Is Demanding A Much Bigger Investment
The eye-catching part of Fabrinet’s $4.64 billion fiscal 2026 is not just how much revenue it produced, but how much capital the company had to put behind that growth: $252.5 million in capital expenditures, more than double the $121.1 million spent in FY25. That spending helped push FY26 free cash flow down to just $4.2 million, from $207.3 million a year earlier.
That is a hell of a commitment to make in one year, but the rest of the balance sheet gives us some context. Inventory climbed from $581 million to $1.02 billion, while accounts receivable increased from $759 million to $1.02 billion. Fabrinet is clearly putting more resources into the business ahead of the demand it expects to serve.
And management isn’t behaving like the boom is about to disappear. Q1 FY27 guidance calls for $1.375 billion to $1.425 billion in revenue, which would put the company on pace for another record quarter.
The spending makes more sense when you look at what Fabrinet is preparing for: more capacity, more inventory and a larger operation built to handle the demand coming from its customers. Investors now need that investment to translate into substantially more earnings and cash flow before the price tag starts looking attractive.
Wall Street Is Starting To Treat Fabrinet Like An AI Stock
The market has spent months repricing Fabrinet as investors realize just how much of the AI infrastructure buildout runs through optical connectivity, and that recognition is now showing up in the analyst narrative around the stock. Yahoo Finance’s “13 Best Strong Buy AI Stocks” list? included Fabrinet among its picks, while others argued that the stock may already be approaching fair value after its enormous multi-year run.
I think both views tell us that FN is no longer being valued like an obscure contract manufacturer that happens to benefit from AI spending. Investors are beginning to price it as one of the infrastructure companies that could keep feeding the expansion of data centers, optical networks and high-performance computing.
The underlying business gives them a reason to do it. Fabrinet’s Q4 growth came as optical communications and other high-complexity manufacturing programs continued expanding, while management said multiple significant growth drivers are contributing to the momentum heading into FY27.
That follows a trend already visible in the previous quarter, when Fabrinet reported $1.214 billion of revenue, up 39%, with data-center interconnect revenue reaching $196.9 million, up 90% year over year.
At the same time, it makes OSI Systems (NASDAQ: OSIS)worth watching as the next data point for the broader electronics and advanced-manufacturing space, with its June-quarter results due August 20 and consensus calling for $3.76 in EPS. Of course, OSI is one of the other stocks operating in Fabrinet’s broader industry group. But the point isn’t that OSI and Fabrinet are interchangeable businesses. They aren’t. It’s that another set of results will give investors a useful read on whether the strength we’re seeing across these specialized manufacturing and infrastructure businesses is broadening.
So I don’t think the AI angle is some convenient story being attached to FN after a good earnings report. The business has been moving toward it quarter after quarter, and the market is finally catching up.
That creates a much tougher standard for the stock from here: when investors start giving a manufacturing company an AI-growth multiple, execution has to keep outrunning expectations.
FN Just Reclaimed All Three Major Moving Averages
The chart is actually much stronger than the after-hours reaction makes it look. Fabrinet closed Monday at $598.58, putting the stock comfortably above its 20-day moving average at $511.01, 50-day at $529.70 and 200-day at $537.36, with 1.59 million shares changing hands during the session.
That is a meaningful technical reset after FN spent much of the summer sliding from the $700 area toward the low $400s. The stock has now recovered sharply from that June-July washout, pushed back through the 200-day average and is approaching the $600 area, where the next real test begins.
I would pay particular attention to what happens if the after-hours weakness carries into the next session. Holding the $537-$530 zone would keep the recent recovery intact and turn those moving averages into support; falling back through them would tell us the market wasn’t ready to sustain the post-earnings optimism.
For now, the chart is still leaning bullish. The market may have taken some money off the table after the earnings release, but it hasn’t broken the underlying recovery in FN.
Bullish, Not Blind To The Price
I’m bullish on what Fabrinet is building, but I’m not going to pretend the stock is asking investors for nothing in return.
The business has earned the right to be taken seriously as a major beneficiary of the optical infrastructure buildout, and the FY27 outlook gives me little reason to think that growth is about to disappear.
What keeps me from getting carried away is the valuation and the cash conversion. Fabrinet now has to prove that the enormous investment it is making can produce enough incremental earnings and cash to justify the expectations attached to the stock.
Today’s editorial pick for you
It May Be Time to Book an Options Trade on Carnival (CCL) Stock
Posted On Aug 19, 2026 by Joshua Enomoto
While global economic challenges ordinarily aren’t helpful for the cruise ship industry, Carnival (NYSE: CCL) may have found a sweet spot. According to Google Finance, CCL stock is benefiting from robust booking demand and continuous balance sheet improvements. Further, Wall Street experts “project steady third-quarter earnings as sentiment suggests a balanced long-term recovery driven by strong pricing power.”
Table of Contents
Of course, there are challenges that shouldn’t be ignored. One of the headwinds is that a softened near-term forecast may put a cap on robust upside gains. To be honest, I’m not entirely sure how much of an impact is going to be involved. I find it incredibly difficult to project what might happen over the next few months, let alone a timeline of a year or longer.
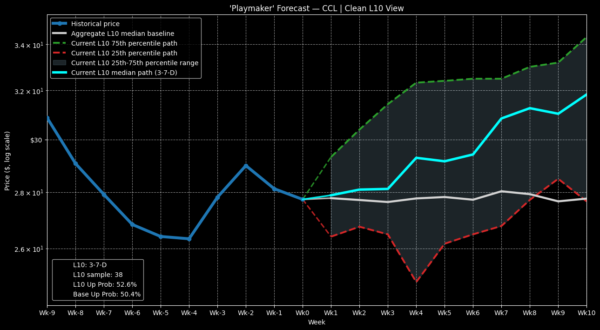
What really fascinates me about CCL stock is the near-term picture. As I write this, the ticker has closed on Monday at a price of $27.73. With enough luck, I anticipate a move to $30 next month. Specifically, I’m looking at the 29/30 bull call spread expiring Sep. 18.
For this trade to be fully profitable, Carnival stock must rise through the $30 strike at expiration, which is roughly five weeks away. That requires a move of 8.19% from the time-of-writing price, which is aggressive. For the Sep. 18 options chain, the historical volatility is 36.92%, which is relatively low. While the current implied volatility (IV) reading is 38.71%, there doesn’t seem to be enough “fuel” to justify this debit trade.
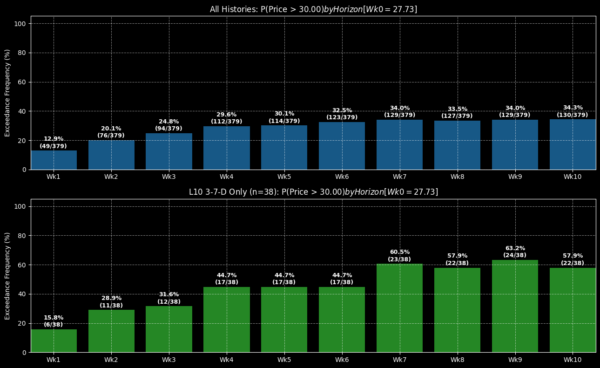
Indeed, Wall Street assigns a probability of profit (breakeven) of only 31% for the above call spread. Making matters worse, the probability distribution screener suggests that the chances of CCL stock hitting the $30 strike at expiration is only about 23.94%.
With a maximum payout of just under 186%, there’s no way for the above call spread to generate a positive expected value (EV). Even though you’d be winning a bunch of money on the 24% of the time you are successful, the 76% failure rate statistically ensures that you’d be throwing money into a sinking boat.
Why the Nonrandom Walk is the More Likely Outcome for CCL Stock
When you look at the probabilities that Wall Street provides for your options trades, you should be aware that they’re implied probabilities based on the target security traversing the market through Brownian motion, otherwise known as a random walk. It really has to be this way in order for derivative contracts to clear the market.
Now, the Street utilizes calculations derived from the Black-Scholes family of pricing models. Think of a T-shirt throwing event at a ballgame. Basically, you have a cheer team launching T-shirts bundled like a burrito into the crowd, to the delight of everyone. But here’s the financial detail most people ignore: those T-shirts are almost always unisex and XL-sized.
Why? Because any adult should technically be able to fit into an XL but large-framed individuals wouldn’t be able to fit into a size S. Thus, to keep everyone satisfied — though few are happy — XL T-shirts are launched into the mass of people.
Black-Scholes operates on the same principle. Essentially, the implied pricing of probabilities assumes a random, risk-neutral environment. Obviously, it’s not going to be the most appropriate framework for the plethora of publicly traded companies. But since creating probabilistically biased or privileged models would cause a nightmare in the derivatives market, we’re left with an all-are-satisfied, none-are-happy framework.
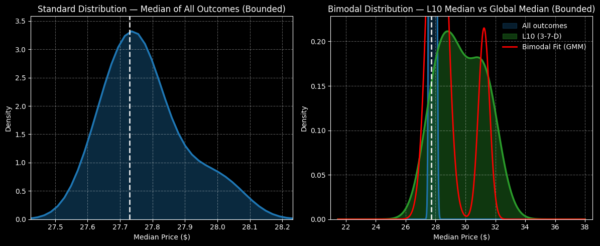
So, getting back to Carnival stock, what do the above probabilities mean? Basically, if CCL were to take a random walk journey from the current starting point to the expiration date, there would only be a 24% chance that the ticker would hit the $30 strike.
My contention, though, is that under the current circumstances, CCL stock should incur a nonrandom walk. If you look at the last 10 weeks, the quantitative structure is rather poor: only three up weeks were printed, leading to a downward slope.
It’s not so much that this 3-7-D quant sequence is somehow privileged or special. Rather, in prior manifestations of this signal, CCL stock has demonstrated upward mobility beyond what is expected under random conditions.
If you want to know why this is so, it’s because the equities market is reflexive. As conditions change, major participants respond to the shift, thus influencing the probabilistic outcome of Carnival stock.
Looking at the Bull Spread Through a Different Lens
It must be said that whether you look at CCL stock from a random framework or nonrandom, the proposition is presuppositional. Since nobody knows what the future will hold, we have to rely on certain assumptions to move the central argument forward.
As the Carnival stock options are currently priced, Wall Street is effectively presupposing that CCL will undergo a random walk. I’m presupposing that it will instead undergo a nonrandom walk. Who’s right? We won’t know until we find out. However, I believe that I have a more credible case than simply assuming Brownian motion.
Over the last 38 times that the 3-7-D signal has flashed on a rolling basis since January 2019, CCL stock exceeded the equivalent of the $30 strike price a total of 17 times at the end of week 5 (or roughly equivalent to the Sep. 18 expiration date). That gives us a conditional, observed success ratio of 44.7%.
Obviously, you’re still looking at a probabilistically risky trade. However, consider the EV calculation. If you indeed won full profitability 44.7% of the time, you would multiply 0.447 with the maximum payout of the 29/30 call spread, which is $65. This arithmetical exercise comes out to $29.06. Of course, you would lose 55.3% of the time, meaning you must multiply 0.553 with the net debit paid to enter the trade, which is $35. That comes out to a loss of $19.36.
Over the theoretical long run, you’re looking at a net gain of $9.70.
Risks to Consider
Does a positive EV mean you should go out and buy Carnival stock options right now? Not necessarily because the calculation is a theoretical one. On any given day, for any given trade, anything can happen. That’s true even though there may be an established pattern of positive variance.
Unfortunately, when you run an inductive model on a non-determinative system, you always incur a black swan risk. Just because some trend or pattern has materialized thousands of times does not mean it is guaranteed to recur in the future. No matter what model you use, you will always face this dilemma in the market. It is what it is.
That said, I believe that my presupposition — of order flow imbalances leading to a statistically exploitable response — is more credible than simply assuming that CCL stock will undergo a random walk, regardless of outside conditions. But at the end of the day, it’s up to each individual trader to decide what assumptions align with their own beliefs.


Tidak ada komentar:
Posting Komentar