Michael Robinson Director of Tech Strategies Weiss Ratings
Today’s editorial pick for you
Levi Strauss Earnings: The Tariff Windfall Is Hiding A Better Margin Story
Posted On Oct 08, 2026 by Grayson Cavern
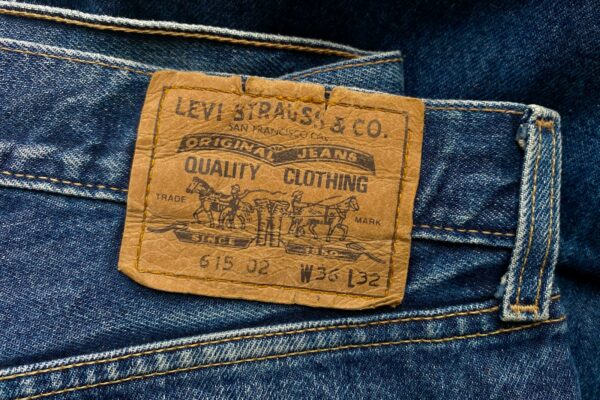
Levi Strauss & Co. (NYSE: LEVI) delivered $0.48 in adjusted earnings per share (EPS) for Q3, up 41% year over year, on $1.61 billion in revenue, up 4%, with organic revenue rising 5%. Then the stock dropped almost 5% to $19.51. At first glance, the selloff looks justified: Levi received $79 million in IEEPA tariff refunds through cost of goods sold and another $5 million in interest income, with the refund contributing a net $0.11 to adjusted EPS after the company redeployed part of the benefit back into the business.
Table of Contents
But there is a much better way to trade the quarter than simply subtracting $0.11 from EPS and calling it a day.
Adjusted EBIT climbed 36% to $249 million, pushing adjusted EBIT margin to 15.5% from 11.8%. Yes, the tariff refund contributed 490 basis points of margin expansion, but Levi spent roughly 160 basis points of that benefit supporting the business, leaving a 330-basis-point net benefit. Gross margin expanded 450 basis points to 66.2%, with the net tariff contribution accounting for 370 basis points. The underlying gross-margin improvement was therefore about 80 basis points.
Sure enough, the refund inflated the quarter. But it did not manufacture every bit of the improvement underneath it.
Elon is gearing up to buy a tiny, publicly traded company.
Why? Because it holds the exclusive rights to a $16 trillion MOTHERLODE of the exact materials his empire runs on... rare metals like cobalt, manganese and lithium.
On January 1st, a new Pentagon rule cuts off his Chinese supply.
Today, it's a $5 stock... but once Elon makes his move, it could soar to $50 within 6 months.
Levi’s direct-to-consumer business remains the part of the chart I wouldn’t ignore. DTC revenue rose only 2% in Q3, comparable sales increased 0.4%, U.S. DTC revenue declined 1%, and Europe DTC fell 2%. With DTC accounting for 45% of total revenue, a sluggish consumer channel can still put a lid on the stock.
The rest of the portfolio is carrying more weight as wholesale revenue increased 6% on both a reported and organic basis, with every segment contributing and Europe and Asia particularly strong. Europe organic revenue increased 5%, Asia jumped 10%, and Beyond Yoga grew 9%. The Levi’s brand itself delivered 4% organic growth, while Levi Strauss Signature increased 12.6%.
That leaves LEVI with a peculiar earnings setup. The channel most visible to the consumer is dragging, while the wholesale machine is gaining traction across multiple geographies. Through nine months, organic revenue was up 6.5%, wholesale organic revenue had increased 6.3%, and adjusted EBIT had risen 20% to $608 million.
Management also says recent DTC trends have accelerated enough to support mid-single-digit DTC growth in Q4, including in the U.S. That is the number bothering me for the next quarter. If DTC finally starts contributing alongside the wholesale and international businesses, Levi’s earnings growth gets a much cleaner runway.
The Guidance Is Doing More Work Than The Refund
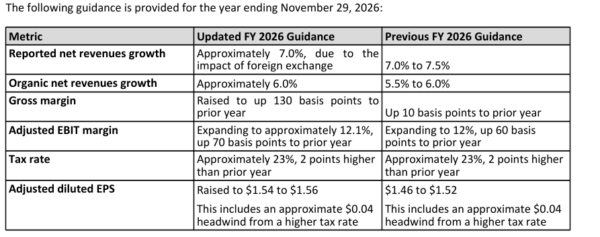
Levi raised its full-year outlook after Q3. Organic revenue growth is now expected at approximately 6%, compared with the previous 5.5%-6% range. Adjusted EBIT margin is projected at approximately 12.1%, up 70 basis points from the prior year and above the previous 12% forecast. Adjusted diluted EPS moved from 1.46-1.52 to 1.54-1.56.
Management expects to redeploy roughly $60 million of tariff refunds during the full year, including approximately $35 million in Q4, assuming current tariff rates remain in place. That money is going toward areas such as marketing and promotions rather than simply dropping straight to the bottom line. Levi is also initiating another $100 million accelerated share repurchase after completing its previous $200 million ASR, which retired about 9.4 million shares across the program.
So yes, the tariff refund will disappear from the model eventually. The higher revenue base, the wholesale growth, the international momentum, the cost structure, and the shares retired through buybacks won’t disappear with it.
Levi’s own forecast does carry some baggage. The company assumes no significant worsening in consumer pressure, inflation, supply-chain disruptions, tariffs or currency fluctuations. Management also openly acknowledged that Q3 DTC performance fell short of internal expectations. For the bulls, Q4 DTC is the next checkpoint.
Source: Levi Strauss
On A Technical Fault Line
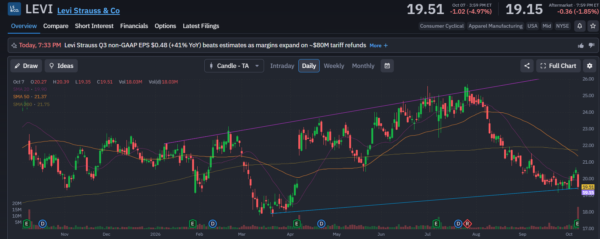
The earnings reaction has put the stock in an awkward spot. LEVI closed at $19.51, below its 20-day SMA at roughly $19.90 and well below the 50-day and 200-day averages around $21.37 and $21.75. The stock had already rolled over from roughly $25.50 in late July, and Wednesday’s 4.97% drop pushed it back toward the rising trendline that has been connecting the spring lows.
That trendline is now sitting around the $19.50 area, almost exactly where the stock closed. For traders, the levels are pretty straightforward. Lose that trendline decisively and the March-to-October recovery structure takes a hit. Reclaim $19.90 first, then $21.37, and the tape starts looking less like a failed breakout and more like an earnings-driven shakeout. Above the 200-day around $21.75, LEVI would have a much better shot at challenging the 23–25 region where sellers took control during the summer.
I wouldn’t chase the stock simply because adjusted EPS beat. The better trade is tied to what happens next with the underlying earnings power.
At $19.51, the stock sits directly on a technical support line, while the business posts stronger organic growth and margins beneath a quarter distorted by tariffs. If U.S. DTC finally joins the wholesale and international businesses, the next leg in LEVI’s earnings story could have considerably less to do with tariff refunds and more to do with the brand itself.
Today’s editorial pick for you
Lululemon Taps Athleta CEO in Reset: Is LULU Stock a Buy or a Trade?
The newly created role takes effect October 26. It puts design, merchandising, footwear, product innovation and materials science under one leader. Lululemon also hired Walmart Canada’s Joseph Godsey as chief operating officer. Two senior executives are leaving. Searches are underway for brand, communications and technology chiefs.
O’Neill took over as CEO on September 8. She is barely a month into the job. Yet she is already rebuilding the leadership bench. These moves are likely the first of several designed to breathe life into a troubled brand.
There’s a familiar thread here. O’Neill and Gauger are both Nike veterans. Gauger ran Nike’s North America women’s business before taking over Athleta in 2025. In other words, Lululemon just hired the executive running one of its direct competitors.
The question for investors is timing. Should you buy LULU stock on the leadership news? Or should you wait for proof the brand is regaining traction? Right now, both the options market and the chart suggest Lululemon may be a better trade than an investment.
Lululemon helped invent the athleisure category. It turned $100 leggings into a status symbol. But success attracts a crowd. Alo Yoga and Vuori built devoted followings. Nike and Athleta pushed harder into women’s activewear. Lower-priced dupes flooded social media.
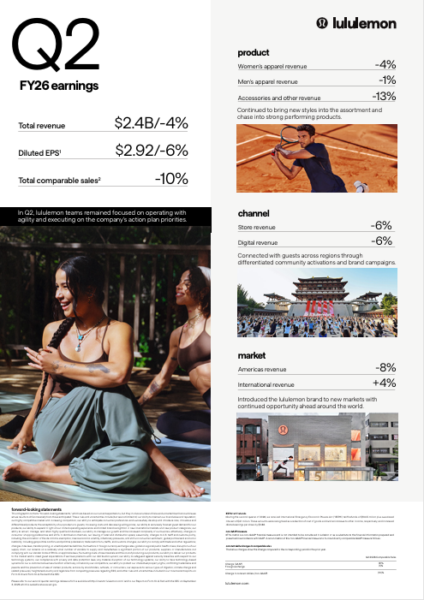
Lululemon was slow to respond, and arguably slow to see it coming. Its core assortment started to look stale while rivals moved faster on style. In the second quarter, comparable sales fell 9%. Every geography posted negative comps. Americas revenue dropped 8%. Management pointed to weaker store traffic and inconsistent product launches.
China was supposed to be the offset. Instead, growth there has slowed. Much of the recent gain has come from new stores rather than stronger sales at existing locations. That’s not the organic demand investors were counting on.
The result was the second guidance cut this year. Lululemon now expects fiscal 2026 revenue of $10.35 billion to $10.5 billion, a 5% to 7% decline. Third-quarter guidance calls for revenue down 10% to 11%. Earnings per share (EPS) is expected at 93 cents to 98 cents, versus $2.59 a year ago. Shares fell about 15% the next day.
A Cheap Stock With a Broken Story
On paper, LULU looks cheap. At about $92, the stock trades under 10 times the midpoint of full-year EPS guidance.
That guidance includes 86 cents per share in one-time tariff refunds. Strip those out, and the multiple is closer to 10.5 times. That’s still inexpensive for a brand with Lululemon’s margins and loyalty.
The balance sheet gives O’Neill room to work. Lululemon ended the quarter with about $1.4 billion in cash. Free cash flow rose sharply, and the company kept buying back stock.
But a low multiple on shrinking earnings isn’t a bargain. It’s a value trap until the trend turns. Gauger’s hire targets the right problem, which is product. However, new product takes seasons, not weeks, to reach shelves. The December report will mostly reflect decisions made before she arrived.
Trading Lululemon’s December Earnings With Options
That makes options expensive. The $90 straddle costs about $16.77, roughly 18% of the share price. A straddle buyer needs LULU below $73 or above $107 at expiration just to break even.
Positioning leans defensive. Across the most active strikes, put open interest totals roughly 14,300 contracts versus about 5,200 for calls. The $75 put carries the largest open interest at 3,647 contracts. That looks like institutional hedging, not speculation.
The most active contract was the $100 call, with 147 contracts across 27 trades. But 121 of those traded at the bid. That points to sellers, possibly holders writing covered calls. They don’t appear to expect a quick move above $100.
With implied volatility this high, defined-risk spreads make more sense than buying options outright. Two examples based on Oct. 7 closing prices:
Bullish call spread: Buy the $100 call and sell the $110 call for about $2.76. Maximum gain is $7.24 if LULU closes above $110. Breakeven is roughly $102.76.
Bearish put spread: Buy the $90 put and sell the $75 put for about $4.56. Maximum gain is about $10.44 below $75. Breakeven is roughly $85.45.
Selling the short leg offsets part of the volatility premium. Note that these are last-trade prices. Actual fills will vary with the bid-ask spread.
Technical Analysis: Oversold, But Still in a Downtrend
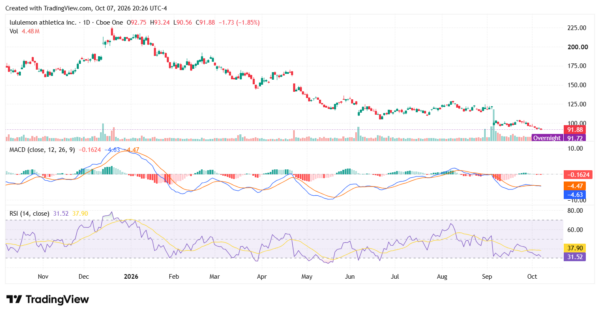
The chart tells the same story as the fundamentals. LULU has posted a series of lower highs since peaking near $225 in December 2025. At $91.88, the stock is down nearly 60% from that high.
The September earnings gap took shares from the low $120s to around $100. A brief bounce stalled near $103. The stock has since broken below that post-gap range to fresh 52-week lows.
The relative strength index (RSI) sits at 31.5, just above the oversold threshold of 30. Over the past year, RSI readings near 30 in April, May, and June produced sharp but short-lived bounces. None of them reversed the larger trend.
The MACD line is at -4.63, just below its signal line at -4.47. The histogram is slightly negative. Momentum remains bearish but is flattening. A cross back above the signal line would be the first sign of a turn.
Resistance sits at $100, a round number and the post-gap shelf. Above that, $105 to $110 is the next hurdle. The unfilled gap near $120 is the bigger target. On the downside, $90 is psychological support. Below that, watch $85 and the $75 level where put open interest clusters.
An oversold bounce toward $100 is plausible. That’s a trade. A trend reversal would require a close above $105 and a higher high. That’s an investment signal, and it isn’t here yet.
Should Investors Buy the News or Wait?
Maggie Gauger is the right kind of hire. She has worked to rebuild a women’s activewear brand and knows the competitive landscape from the inside. Heidi O’Neill is clearly moving fast.
But investors don’t get paid for being early to a turnaround. They get paid for being right. The confirmation signals are clear: stabilizing comparable sales, a bottom in China, and products that generate buzz again. Those likely won’t show up until 2027.
Until then, LULU stock looks like a vehicle for traders, not a core holding. Long-term investors can afford to wait for proof. The stock may cost more when that proof arrives, but the risk will be far lower.



Tidak ada komentar:
Posting Komentar