Editor’s Note: Jeff Brown is the former tech executive who picked Nvidia in 2016 before it jumped 37,000% higher. He’s now recommending another AI stock that’s the same size Nvidia was 10 years ago. He calls it “Elon Musk’s One Stock Retirement Plan” because he believes Elon Musk is about to create massive demand for this company’s patented technology. Click here to see the details or read more below.
Dear Reader,
Make your calendar…
By November 11, I believe Elon Musk is going to help trigger a historic rally in what could be…
It’s a leader in an AI breakthrough that’s protected by 150 patents…
It’s a small company, unknown to most people… still in the initial phase of exponential growth…
Plus, it has a near term catalyst that could send shares skyrocketing… starting November 11.
Today’s editorial pick for you
TSMC Earnings Face a $480 Test as AI Demand Powers Growth
Posted On Oct 13, 2026 by Grayson Cavern
Taiwan Semiconductor Manufacturing Company (NYSE: TSM) has climbed more than 50% from its April lows, riding the AI infrastructure boom toward $480. Now the stock is pulling back just as investors prepare to judge whether the chipmaker can keep delivering the growth that fueled its rally. TSM closed October 12 at $444.35, down nearly 2% on the session, after failing to hold its recent highs.
Table of Contents
Thursday’s earnings report arrives with a demanding benchmark already on the table. TSMC generated $40.2 billion in second-quarter revenue, up 33.7% year over year, and management guided for $44.6 billion to $45.8 billion in Q3 revenue. Advanced-node demand remains the engine, but the company also projected lower margins. The next report needs to show that AI-driven growth can keep scaling without eroding the profitability that makes TSMC such a powerful semiconductor play.
Elon Musk has gone "all in" on Texas, home of SpaceX. But Texas just froze ALL new AI data center buildouts.
The reason? Data center demand in Texas has soared from 48 gigawatts to 474 gigawatts... since 2023, according to Reuters. But according to 60-year Wall Street legend Marc Chaikin, one company has the solution. Its "micro cluster" technology will consume an estimated 99% less electricity and water. And it'll come online as soon as Oct. 20th. When it does, it'll make current data centers obsolete when it comes to major AI breakthroughs – including Elon's Grok.
TSMC’s Q2 results showed what happens when demand for leading-edge chips meets the company’s manufacturing advantage. Revenue rose 12% sequentially, while net income jumped 77.4% year over year to NT$706.56 billion. Gross margin reached 67.7%, operating margin hit 60.3%, and net profit margin came in at 55.6%.
Those are exceptional numbers, and they leave little room for a lazy earnings thesis built around AI spending alone. The company’s Q3 revenue guidance of $44.6 billion to $45.8 billion implies roughly 11% sequential growth at the midpoint. Investors already have a strong growth target to measure Thursday’s results against; the forward outlook will determine whether TSMC can keep exceeding it.
The first number to examine is revenue. A result above the guided range would signal that demand and production are running ahead of management’s expectations. A result inside the range could still be solid, but the market reaction will depend on what executives say about the following quarter and the pace of customer demand. If guidance merely meets expectations after the stock’s huge run, traders may take profits rather than chase another leg higher.
Advanced Chips Must Keep Carrying the Load
The more revealing evidence will come from TSMC’s advanced-node business. In Q2, advanced technologies accounted for 77% of wafer revenue, with 3nm contributing 30%, 5nm accounting for 33%, and 2nm already contributing 3%. Management attributed its performance to strong demand for leading-edge process technologies and expected that demand to continue into Q3, including a steep ramp-up of 2nm production.
That mix gives TSMC a direct route to monetizing the rising complexity of AI chips. As customers require more advanced manufacturing, the company’s process technology and production capacity become central to their product road maps. Thursday’s report should tell us whether advanced-node demand is still expanding and whether the 2nm ramp is progressing as planned.
There is a catch in the margin guidance. Management projected Q3 gross margin of 65%–67% and operating margin of 56%–58%, both below Q2’s levels of 67.7% and 60.3%. The company is already signaling that stronger revenue may come with some margin compression.
I would focus on how actual margins compare with those ranges and what management attributes any change to. If revenue growth remains strong while gross margin holds near the top of guidance, TSMC could demonstrate that its operating model is absorbing the costs of expansion. A sharper decline would complicate the bullish case, particularly if the company also tempers its revenue outlook.
TSM Is Testing Its Own Momentum
The chart is giving traders a separate reason to be careful. TSM has formed a potential double top around $480, and the latest pullback has pushed the share price below its 20-day simple moving average at $451.79. The stock remains above its 50-day average at $433.27 and its 200-day average at $392.51, so the longer-term uptrend has not yet broken.
The first reclaim level is $452, around the 20-day average. Getting back above it would help repair short-term momentum, but buyers still need to overcome the $480 resistance zone to establish a fresh breakout. On the downside, $433 is the first level to watch, followed by the rising trendline in the low $420s. A deeper correction would put the 200-day average near $393 into view.
A double top is a warning, not a verdict. Earnings could supply the catalyst that pushes TSM through resistance, while a disappointing outlook could turn the pattern into a more damaging reversal. The distinction will come from the reaction after the numbers land, not the headline alone.
The Verdict Depends on Guidance
I remain bullish on TSMC’s underlying business heading into Thursday’s report. Q2 showed strong revenue growth, exceptional profitability, and a business mix increasingly concentrated in advanced manufacturing. Those advantages leave the company well positioned to benefit from continued demand for high-performance computing and AI infrastructure.
But I would not chase the stock simply because revenue beats expectations. Management’s Q3 guidance already points to lower margins, and TSM has retreated from the $480 area while losing its short-term moving average. The earnings call needs to support another leg of growth and explain how profitability will hold up as production ramps.
I rate TSM a BUY, with $433 as the first support level and $480 as the breakout hurdle. A revenue beat accompanied by resilient margins and confident forward guidance could bring buyers back. If growth meets expectations while margins weaken and the outlook lacks upside, the stock could continue consolidating despite the strength of the AI trade.
Today’s editorial pick for you
Hotel Stocks Still Shine, but Q4 May Not Be the Time to Check In
Posted On Oct 05, 2026 by Chris Markoch
Premium hotel stocks have a perception problem, and it isn’t the one you might expect. The fundamentals are strong. Hilton, Marriott, and Hyatt all raised their 2026 RevPAR guidance after the second quarter. Luxury travelers kept spending. The FIFA World Cup delivered a bigger boost than planned.
Table of Contents
Yet the stocks tell a more cautious story. All three peaked in June and spent the summer giving back gains. Marriott and Hilton dipped below their 200-day moving averages in September before recovering. Hyatt is still below its own.
That gap between performance and price action is the story for the fourth quarter. The market is looking past a strong 2026 toward a slower 2027. CoStar and Tourism Economics now forecast 4.4% U.S. RevPAR growth this year. Their 2027 forecast falls to just 2.1%.
For that reason, hotel stocks may not be the best place for new money in Q4 2026. The easy comparisons are fading. The event-driven tailwinds are behind them. Meanwhile, valuations still assume premium growth.
But here’s why investors building positions for 2027 and beyond should pay attention to hotel stocks now. These are asset-light businesses with record pipelines and heavy capital returns. The question is which name, and at what price. Here’s how Hilton (NYSE: HLT), Marriott (NASDAQ: MAR) and Hyatt (NYSE: H) stack up.
Elon Musk just dropped a bombshell—he’s taking on cell phone providers.
After keeping his plans quiet for months, he finally showed his hand. He’s set to launch a new device that could replace the iPhone and hand early investors a potential 50x payday.
To be clear, it’s not smooth sailing for hotel stocks. Several headwinds converge in the final quarter. First, the World Cup lift is gone. Marriott said the tournament added about 45 basis points to full-year global RevPAR. That beat its own estimate, but it won’t repeat.
Second, Hilton’s guidance points to a slowdown. It expects roughly 4% RevPAR growth in Q3. Its full-year range of 3% to 3.5% implies low-single-digit growth in Q4. Management sees the underlying run rate at just 2% to 2.5% once event noise is stripped out.
Third, the Middle East conflict remains a drag. Marriott noted the region enters its peak tourism season in October. That gives the conflict more weight in Q4 than in Q3. Hyatt has also flagged softness in Mexico’s all-inclusive resorts.
None of this, however, breaks the long-term thesis. When consumer discretionary stocks turn around, hotel stocks will be among the winners. But the headwinds just make the near-term setup less compelling.
Hyatt: The Priciest Name May Be the Best Short-Term Value
Hyatt carries the richest multiple of the group. It trades around 45 times forward earnings. That compares to roughly 34 for Hilton and 28 for Marriott.
At first glance, that looks like a red flag. But the multiple reflects a company in transition. Hyatt sold the Playa real estate portfolio for about $2 billion. It now expects roughly 90% of adjusted EBITDA to come from asset-light sources.
Growth backs up the price. Hyatt posted 5.9% system-wide RevPAR growth in Q2, the best of the three. It raised full-year RevPAR guidance to 3.5% to 4.5%. Adjusted EBITDA guidance calls for 13% to 18% growth. By several measures, its PEG ratio sits below 1.0.
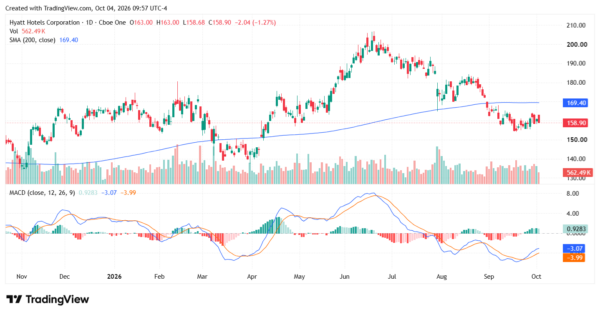
The stock hasn’t gotten credit for any of it. Shares fell 6.7% after Q2 despite an earnings beat. At about $159, Hyatt trades roughly 23% below its June high near $207. Hilton and Marriott sit only 11% to 13% off their peaks.
There’s a caveat. Hyatt is the only one of the three still below its 200-day SMA, near $169. Its MACD has crossed bullish, but from below zero. Short-term buyers should want to see the stock reclaim that line. Until it does, the value case is running ahead of the chart.
Marriott: A Core Holding, but Not at Any Price
Marriott is the scale player. Its system holds roughly 1.8 million rooms, with a record pipeline of nearly 629,000 more. U.S. and Canada RevPAR rose 5% in Q2, its best showing in 13 quarters. Luxury RevPAR climbed more than 9%.
Marriott also returns a lot of cash. It returned about $2.6 billion to shareholders in the first half. New co-branded credit card deals should add meaningful fee income by 2028.
It has the lowest multiple of the three. The catch is that the multiple has expanded. Marriott’s forward P/E was near 22 a year ago. Today it’s closer to 28.
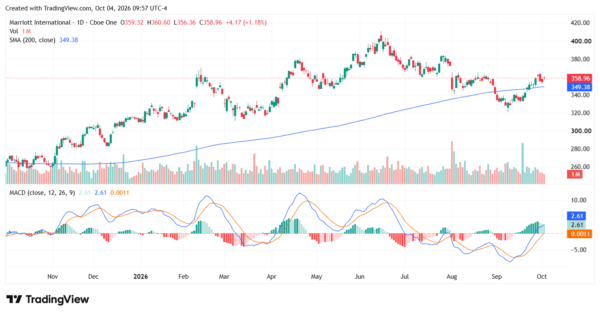
The chart looks healthy. Shares closed near $359, above the 200-day SMA around $349. The MACD just crossed back above zero. But with the stock only about 3% above that average, there’s little cushion. A meaningful dip would be a retest of the September lows near $320. That’s where Marriott shifts from Hold to Buy.
Hilton: Quality Comes at a Premium
Hilton may be the highest-quality operator of the three. Its 6% to 7% net unit growth guidance leads the group. It plans to return about $3.5 billion to shareholders in 2026. Business transient RevPAR jumped 5.7% in Q2.
Management is also leaning into 2027. It cited AI-related spending and infrastructure investment as drivers of above-trend growth next year. That’s a constructive signal for long-term holders.
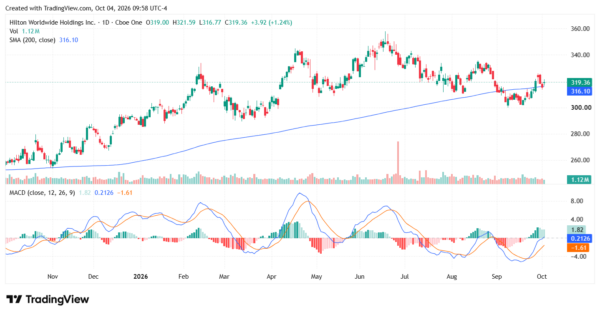
The problem is price. At roughly 34 times forward earnings, Hilton costs more than Marriott. Shares sit near $319, barely 1% above the 200-day SMA around $316. The MACD has turned positive, but the stock already bounced hard off its lows. A pullback toward the September lows near $300 would offer a far better entry.
Hotel Stocks: Which Name Offers the Best Opportunity?
Hotel stocks are creating a classic perception-versus-fundamentals setup. The fundamentals are still strong. But the market is already pricing in a slower 2027, and Q4 offers few catalysts to change that view.
For short-term investors, Hyatt offers the most upside if the asset-light story earns a rerating. Waiting for it to reclaim its 200-day SMA would be the prudent move.
For buy-and-hold investors, Marriott and Hilton remain names to own. At current prices, though, they look like Holds. A meaningful dip toward their September lows would turn patience into opportunity.




Tidak ada komentar:
Posting Komentar