Matt Weinschenk Publisher and Director of Research, Stansberry Research
P.S. Whitney believes what's happening today could reset the financial system after these midterm elections. If Whitney's even half-right, it's going to have a huge impact on your money and your future. Get the details here...
Today’s editorial pick for you
What Wall Street Expects From Amazon’s Q3 Earnings Report
Posted On Oct 15, 2026 by Ian Cooper
Amazon’s (NASDAQ: AMZN) upcoming earnings report will give investors a fresh look at growing demand for artificial intelligence and the cost of keeping up with it.
Elon is gearing up to buy a tiny, publicly traded company.
Why? Because it holds the exclusive rights to a $16 trillion MOTHERLODE of the exact materials his empire runs on... rare metals like cobalt, manganese and lithium.
On January 1st, a new Pentagon rule cuts off his Chinese supply.
Today, it's a $5 stock... but once Elon makes his move, it could soar to $50 within 6 months.
Wall Street expects Amazon to deliver another quarter of higher sales, although earnings forecasts vary across data providers. Right now, there are estimates of EPS of $1.96 per share on revenue of about $202.1 billion.
Management projected third-quarter revenue between $197 billion and $202 billion, or growth of 9% to 12%. It also forecast operating income between $22.5 billion and $26.5 billion, compared with $17.4 billion a year earlier.
Investors should also account for the timing of Prime Day. Amazon said that excluding the event’s impact in both years would make projected third-quarter sales growth nearly four percentage points higher. Simply comparing quarterly growth rates could therefore give an incomplete picture of demand.
AWS Has a High Bar to Clear
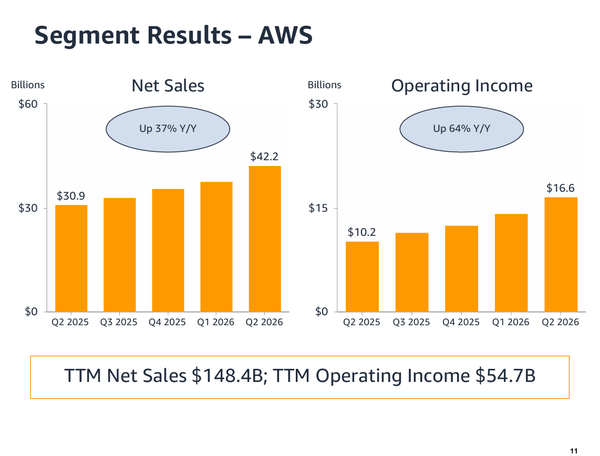
Amazon Web Services (AWS), the company’s cloud-computing division, will likely be central to the earnings reaction. In the second quarter, AWS revenue increased 37% to $42.2 billion, its fastest growth in 18 quarters. The division generated $16.6 billion in operating income, accounting for roughly 60% of Amazon’s total.
Those numbers explain why investors watch AWS so closely. Stronger cloud demand can have an outsized effect on the company’s overall profits. The question now is whether that momentum continued through September. Investors will be looking for evidence that customers are expanding their cloud workloads and spending more on AI services.
Source: Amazon
Recent Analyst Target Increases Add Optimism
Several recent analyst actions have strengthened the bullish case.
On Oct. 6, Tigress Financial raised its AMZN price target to $385 from $315 while maintaining a Buy rating. That represents a substantial increase in the firm’s valuation outlook.
Rosenblatt also raised its target, lifting it to $360 from $335 on September 30 and maintaining a Buy rating. The firm argued that concerns about AI shopping assistants disrupting the company’s advertising business were overstated. Its view is that Amazon can adapt as shopping habits evolve. Meanwhile, Goldman Sachs added Amazon to its conviction list on October 1 with a $375 price target, giving the stock another prominent endorsement.
The Spending Question Could Decide the Reaction
Amazon’s growth opportunity comes with a considerable bill.
Management’s 2026 capital-spending estimate reached approximately $220 billion, according to reporting on its second-quarter earnings call. Meanwhile, Amazon reported negative free cash flow of $7.6 billion over the twelve months through June, largely reflecting increased investment in AI infrastructure. Investors will want a clearer sense of when that investment can produce stronger cash generation.
Ultimately, Amazon needs to connect three things: healthy customer demand, profitable growth, and a credible return on spending. Strong AWS results and an encouraging holiday outlook could reinforce the recent bullish analyst calls. Another increase in spending without comparable progress could leave investors asking harder questions.
For AMZN investors, this earnings report comes down to a fairly simple question: Is all that spending starting to pay off? Higher sales would be encouraging, but stronger profits and a clearer path to generating cash would give shareholders more reason to feel confident. The recent analyst target increases suggest there’s optimism heading into the report. Now the company needs to back it up and show that it can keep growing without the bill growing faster.
Today’s editorial pick for you
3 Mid-Cap Stocks Challenging the Mag 7’s Grip on the AI Trade
Posted On Oct 06, 2026 by Grayson Cavern
The AI trade has become so concentrated that it is easy to forget how much money has to be spent before an AI model can answer a single prompt. Nvidia (NASDAQ: NVDA) supplies the GPUs, while other mega-cap technologies are building enormous computing capacity and driving the market higher at the same time.
Table of Contents
But under the hood, the physical AI buildout creates problems software cannot solve. More GPUs mean more heat. More AI infrastructure means more electricity. Thousands of accelerators also need to be integrated, deployed, and managed before they generate anything for a customer…
As of this moment, MOD is worth $9.71 billion, PENG $3.11 billion, and POWL $7.21 billion. Their market caps have climbed 25.4%, 113.9%, and 96.4%, respectively, over the past year.
The more computing power you pack into a data center, the harder thermal management becomes. That gives Modine (MOD) a direct way to participate in the AI buildout without selling a single GPU.
Modine’s latest quarterly results? show how quickly that business is scaling. Q1 fiscal 2027 revenue reached $874.1 million, up 28% year over year, while EPS rose 44%. Data Center revenue was the standout, jumping 90% year over year.
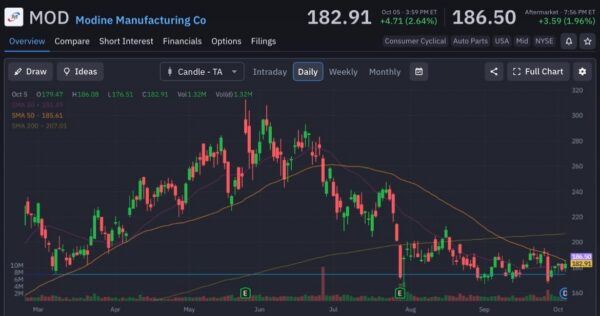
MOD closed at $182.91 on October 5, sitting just above its 20-day SMA at $181.49 but below its 50-day at $185.61 and well below its 200-day at $207.01. After falling from above $300 earlier in the year, the stock found buyers around $170-$175 in September and has started forming a higher-low structure.
A move through $186 would put the 50-day average back underneath the stock, while $200-$207 is the much bigger test. Until then, MOD is recovering from a major drawdown rather than sitting in a confirmed long-term uptrend.
That makes the operating growth particularly important. Modine already shows a business seeing substantial demand from data-center customers, while the cooling problem only becomes more demanding as computing density rises.
PENG Is Moving From Hardware To AI Factories
Penguin Solutions (PENG) sits closer to the point where AI hardware becomes a functioning system.
The company reported record Q3 fiscal 2026 revenue of $478.7 million, up 48% year over year. GAAP operating income jumped 417%, while non-GAAP EPS increased 79%. Management subsequently raised its full-year outlook as demand strengthened across its Integrated Memory and AI Infrastructure businesses.
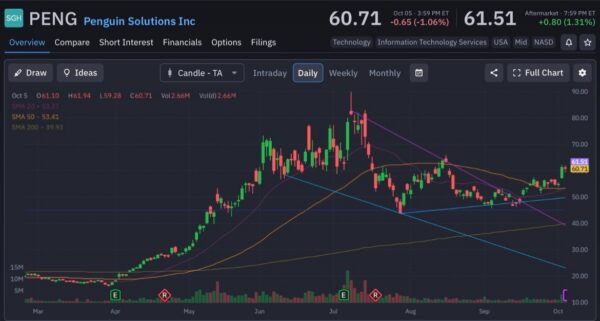
The stock chart is considerably stronger than MOD’s. PENG closed at $60.71, more than $7 above both its 20-day and 50-day SMAs, which sit around $53.37 and $53.41. The 200-day SMA is down at $39.93. More importantly, PENG has broken above the descending trendline that had capped the stock since its July peak near $80.
The next hurdle is around $62, followed by the $70 area. Holding above $53-$54 would preserve the current breakout structure. For me, that combination of accelerating revenue and a technical breakout makes PENG the most aggressive momentum setup of the three.
Powell makes engineered equipment for the management, control, and distribution of electrical energy. Its Q3 fiscal 2026 results showed $934 million of new orders, up 158%, pushing backlog to $2.4 billion, up 69%. Book-to-bill reached 3.0x. In fact, Powell also secured a data-center project worth more than $400 million.
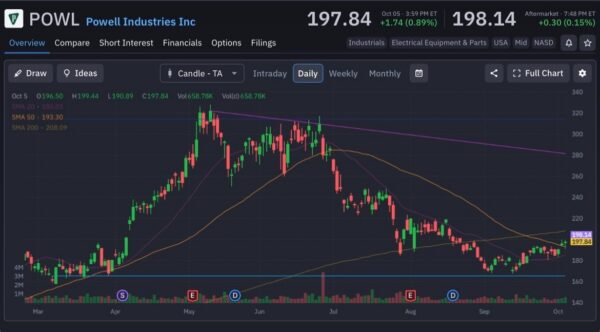
And the chart has now started recovering too. POWL closed at $197.84, above its 20-day SMA at $185.03 and 50-day at $193.30, after bouncing from the $165-$175 area in September. The 200-day SMA sits at $208.09, making $200-$208 the immediate technical ceiling.
A clean break through that zone would put POWL back above its long-term average for the first time since its summer decline. Failure there leaves the stock trapped between roughly $175 support and $208 resistance.
The AI Trade Has a Much Bigger Supply Chain
This is where I think the opportunity gets interesting for investors who already own the obvious AI winners.
Nvidia, Microsoft, Amazon, and Alphabet have captured the attention because their products sit at the center of the AI revolution. But just as you’ve seen, MOD, PENG, and POWL sit further down the chain, where the physical constraints of that revolution are becoming increasingly expensive to solve.
None of these companies needs to become the next Nvidia for the thesis to work. They need AI capital spending to keep flowing into data centers, and their recent financial results suggest that spending is already reaching their businesses. Getting exposed to this basket of 3 smaller companies, sitting underneath the same multitrillion-dollar AI spending cycle, each attacking a physical bottleneck the Mag 7 cannot simply wish away…is almost a no-brainer for me.


Tidak ada komentar:
Posting Komentar