 A Message From Banyan Hill Publishing Dear Reader, I’ve never been angrier at the U.S. banking system. Here’s something most people don’t know. Since 2020, American banks have been required to keep exactly zero percent of your deposits on hand. Zero. Your money isn’t really there. They’ve lent it out, every last dollar. They pay you 0.04% on your savings… then charge you 25% on your credit card. For years, we had no choice. But now it’s all about to change. The U.S. Treasury just cleared the way for a new form of money — riding on a law President Trump signed last summer, the GENIUS Act. And starting January 18, it could soon hand the richest man on Earth the legal right to do the one thing the banks feared most: make money great again. With up to 6% interest on your savings. It’s already live in 47 states. Position yourself early, and you could make a fortune. Go here and I’ll show you what I’ve found. Regards, 
Ian King
Chief Strategist, Strategic Fortunes
Exclusive Content
2 Short-Squeeze Candidates Waiting for the Right CatalystAuthor: Thomas Hughes. Published: 9/29/2026. 
Key Points
- Hertz Global and SoundHound AI are both heavily shorted stocks with elevated days to cover, creating conditions that could support a short squeeze.
- Hertz is working to improve fleet economics and return to profitability, while SoundHound AI is focused on growth, AI expansion and integrating LivePerson.
- Both stocks still need a meaningful catalyst to force short sellers to cover, making execution and upcoming results especially important.
- Special Report: Tech expert smashes iPhone with golf club
Stocks with high short interest are a dime a dozen; the question is whether short sellers can cover quickly, which is indicated by days to cover. Days to cover measures how many days of average trading volume it would take short sellers to close out 100% of their positions. The higher the figure, the better it is for investors looking for a squeeze, and a reading above five is generally considered favorable. More than five days to cover suggests that short sellers may have difficulty closing their positions, provided an explosive catalyst emerges. Hertz Global: The Engine Is Running, Just Waiting for the SignalHertz Global (NASDAQ: HTZ) is among the most heavily shorted stocks on the market and is exhibiting classic signs of a short squeeze. Depending on the platform, short interest ranges from approximately 30% at the low end to as much as 75%, with a high short ratio to match.
The high short ratio is a key factor because it indicates that it would take more than a week of buying at normal levels to close out the short positions. Some platforms report as many as 11.5 days to cover. With this dynamic in play, the market needs only a catalyst to invigorate retail trading and drive demand for the available shares, sending short sellers scrambling to cover and potentially sending the share price sharply higher. Catalysts include the company’s growth strategy and pathway to profitability. Recent results reflected unexpected strengths, including improved core fleet-efficiency metrics, a smaller fleet size, 9% revenue-per-unit growth and 8% revenue-per-day growth. Looking ahead, the company is expected to reach profitability over the coming year and may surprise investors with positive news along the way. Hertz's 2026 strategy rests on four pillars: fleet age, stabilizing depreciation, expanding service areas and extending vehicle lifecycles. Fleet age is central; by reducing the overall fleet age to an average of about two to three years, the company aims to lower maintenance and repair costs. Short sellers are focused on the company’s high debt. Meanwhile, the fleet mix is also changing, with fewer EVs to better align with the company’s depreciation profile. For growth, the strategy focuses on markets outside airports, the company’s traditional home turf. These markets provide more predictable revenue with less exposure to holiday-related fluctuations. Likewise, targeting the rideshare and delivery markets could extend vehicle lifecycles and improve monetization by giving drivers easier access to vehicles. Analyst trends are a headwind. The eight analysts MarketBeat tracks rate the stock as a Reduce, and price targets are falling. While consensus forecasts suggest about 80% upside, the trend points to the low end of that range, well below late-September trading levels. Institutions, however, own nearly 100% of the shares and have been accumulating them at these low levels, raising the stakes for short sellers. 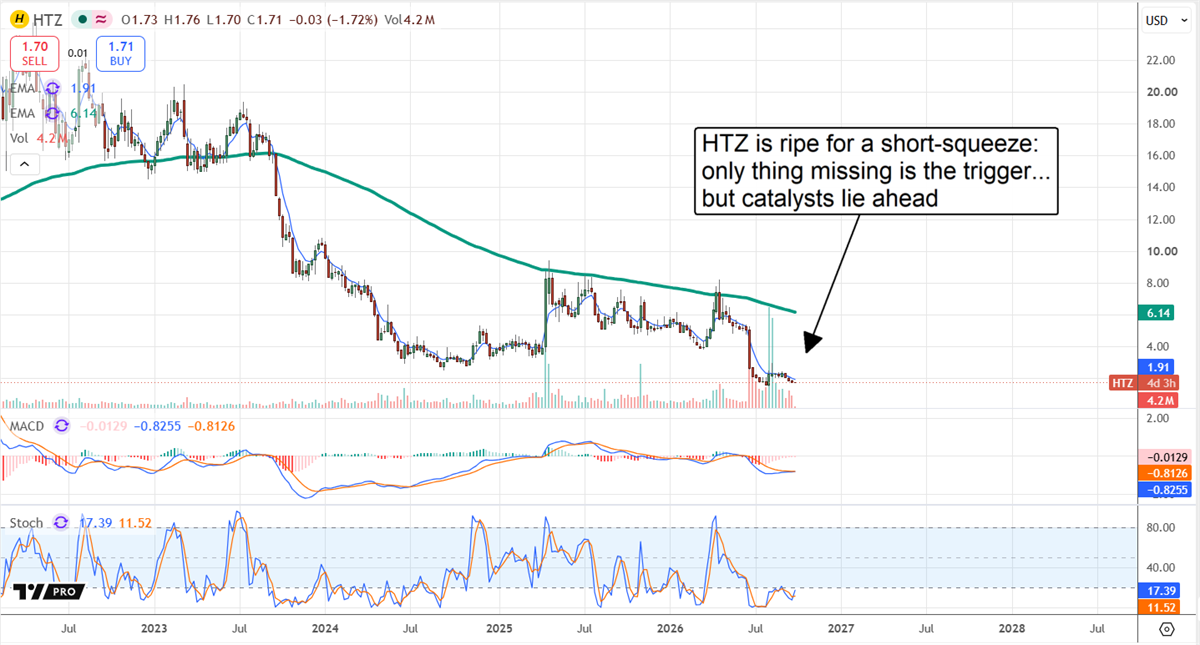
SoundHound AI: An Execution Story in PlaySoundHound (NASDAQ: SOUN) is another heavily shorted stock, with short interest above 40% as of mid-September. The risks include cash burn and execution. Skeptics wonder whether the company can successfully monetize its backlog and transition to profitability while integrating major acquisitions such as LivePerson. Again, days to cover matters, with MarketBeat data indicating seven days to cover, or more than a week of trading volume. That suggests this market is a tinderbox waiting to be lit. Catalysts include quarterly outperformance, which could be supported by current trends and the rapid LivePerson integration. LivePerson is a key element of the strategy, validating SoundHound’s ability to scale rapidly and capitalize on cross-selling opportunities if the integration succeeds. Other catalysts include product innovation, including agentic AI and in-car voice assistance. The Oasys Edge platform aims to open new addressable markets by enabling localized AI deployment without an internet connection, while deals with Stellantis (NYSE: STLA) and NVIDIA (NASDAQ: NVDA) are strengthening its position as a leader in agentic automotive original equipment manufacturer (OEM) software. The market gets SoundHound wrong by treating it as a niche, automotive-focused company with questionable leverage. It is transitioning into an enterprise-quality vendor that provides consumer-facing interfaces across the stack and is starting to show leverage at scale. The OASYS and LivePerson acquisitions are central to the strategy, creating an omnichannel provider with voice, web, mobile and SMS capabilities that already serves 25% of the Fortune 100. The question is whether the company can integrate the systems into a universal product and expand its user base, which would represent the optimal scenario. Conversely, the seven analysts covering SoundHound rate it a consensus Moderate Buy, with more than 50% of ratings on the Buy side. They see a price floor near $6, aligning with the critical support target, and more than 100% upside at the midpoint target. Good news could trigger a move toward the consensus target; the key question is whether it will be enough to lift sentiment and spur analysts to raise their price targets. 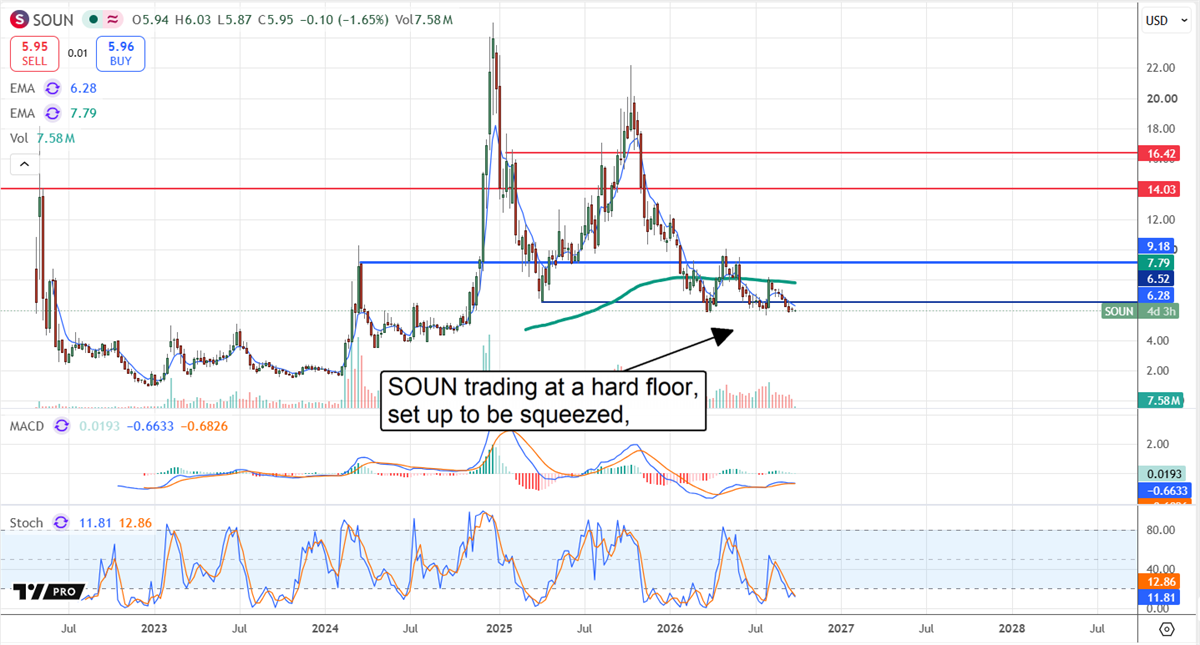
This ad is sent on behalf of Banyan Hill Publishing.
This ad is sent on behalf of Banyan Hill Publishing.
. |


Tidak ada komentar:
Posting Komentar