
A Message From Base Camp Trading
Hey Trader,
This certainly isn't going to win me any friends in the industry.
But I don't care.
For Black Friday, I'm practically giving away my proprietary "Snapback Indicator."
It's yours for just a single payment of $7. No strings attached.
When you see the Crash Alert, that's your cue to get out or go short.
When you see the Bull Run Alert, that's your cue to buy or go long.
Don't make another trade until you see this indicator in action. Best of all… I'm giving you LIFETIME access. Others paid $500 for this. But you're getting lifetime access to the Snapback Indicator for just $7.
Go here:
Black Friday Bombshell: "Snapback" Indicator For $7
In your corner,
Thomas Wood
Base Camp Trading
P.S. There's an unusual reason why I'm giving you such an outlandish discount on this incredible indicator. Full explanation here.
This Month's Bonus Article
3 Building-Materials Stocks Rallying While Homebuilders Struggle to Find Buyers
By Dan Schmidt. Originally Published: 11/14/2026.
Key Points
- High mortgage rates are discouraging homeowners from moving, pushing them to renovate existing properties instead, which benefits building-materials suppliers.
- Masco, Carlisle, and James Hardie each beat earnings estimates in their most recent quarters and are showing strong year-to-date stock price gains.
- While homebuilders like D.R. Horton face margin pressure from buyer incentives, repair, renovation, and replacement-focused material suppliers are outperforming with bullish technical signals.
- Special Report: SpaceX can't do this alone (meet Elon's silent partner)
The housing market's slowdown is creating a divide in the building-materials industry. While homebuilders struggle to attract buyers, companies that supply materials for repairs, renovations, and replacement projects have a different opportunity to capture demand.
The gap between new and existing mortgage rates helps explain why. Mortgage rates have risen back above 7%, which not only prices out first-time buyers but also makes moving financially unfeasible. Federal housing data analysis showed that while the number of homeowners with mortgage rates above 6% grew in Q2 2026, only 22.5% of total mortgages had rates of 6% or higher. The average rate on outstanding mortgages is 4.4%, so most Americans have little incentive to move unless there’s a catalyst, such as children or a new job.
The pressure is evident in the new-home market. The NAHB/Wells Fargo Housing Market Index fell to 29 in October, its lowest reading since June 2012. Meanwhile, homebuilders like D.R. Horton Inc. (NYSE: DHI) continue offering costly mortgage-rate buydowns and other incentives to attract buyers, putting additional pressure on their margins.
Instead of moving, some homeowners are choosing to invest in their existing properties. Combined with ongoing demand for commercial property maintenance and replacement projects, that creates opportunities for building-materials suppliers. Three stocks in particular are showing momentum that many homebuilders lack.
Masco: The Cleanest Repair and Remodel Play
One of the biggest beneficiaries of homeowner upgrades is Masco Corp. (NYSE: MAS), which manufactures faucets and fixtures under the Delta, Peerless, and Hansgrohe brands, and paint under Behr and Kilz.
Unlike most companies in the homebuilding industry, Masco is growing margins and raising guidance, and the stock has responded with a year-to-date (YTD) gain of more than 30%.
Masco reported Q3 2026 earnings on Oct. 28 and posted a top- and bottom-line beat, but the outlook was what really impressed the market.
Revenue grew 3% year over year (YOY), and operating profit surged 13% YOY, with both figures exceeding analysts’ estimates. Gross margins expanded 2.4 percentage points to 36.6%. Notably, these results were relatively free of one-time items, with pricing, cost savings, and lower year-over-year tariff costs helping drive profit growth.
Management raised full-year 2026 earnings per share (EPS) guidance to $4.65 to $4.75 and its operating margin outlook to 18% to 18.5%, despite anticipating inflation from copper, oil, and freight in the coming period.
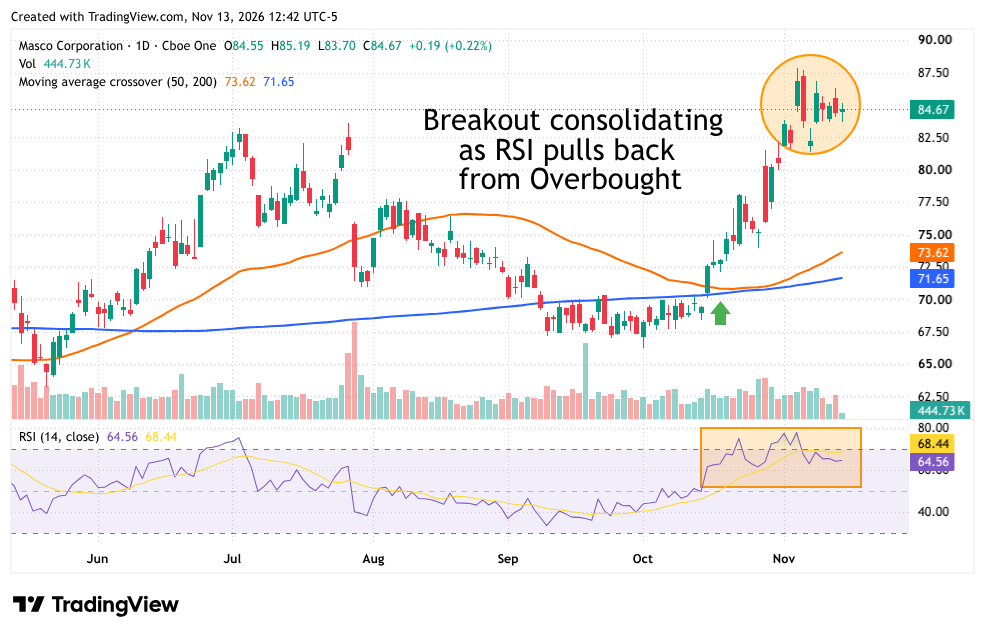
The stock broke above its previous 2024 all-time high earlier this month and now appears to be consolidating ahead of its next move. The price is firmly above the 50-day and 200-day moving averages, and the Relative Strength Index (RSI) has retreated from overbought territory. Unless component inflation comes in higher than expected, Masco has both fundamental and technical tailwinds behind it.
Carlisle: Businesses Need New Roofs Too
Carlisle Companies Inc. (NYSE: CSL) doesn’t traditionally sell into the residential market.
Instead, it focuses on commercial roofing and insulation, and many business owners are choosing to replace roofs rather than finance new construction.
The roofing segment has been one of the company’s leaders for decades, and its revenue continues to grow strongly.
Carlisle also beat estimates in its Q3 2026 report on Oct. 28, with Construction Materials (the roofing segment) revenue up 8% YOY. Adjusted EPS hit a third-quarter record of $5.92 despite material and freight inflation cutting into margins, and management expects costs to normalize in 2027.
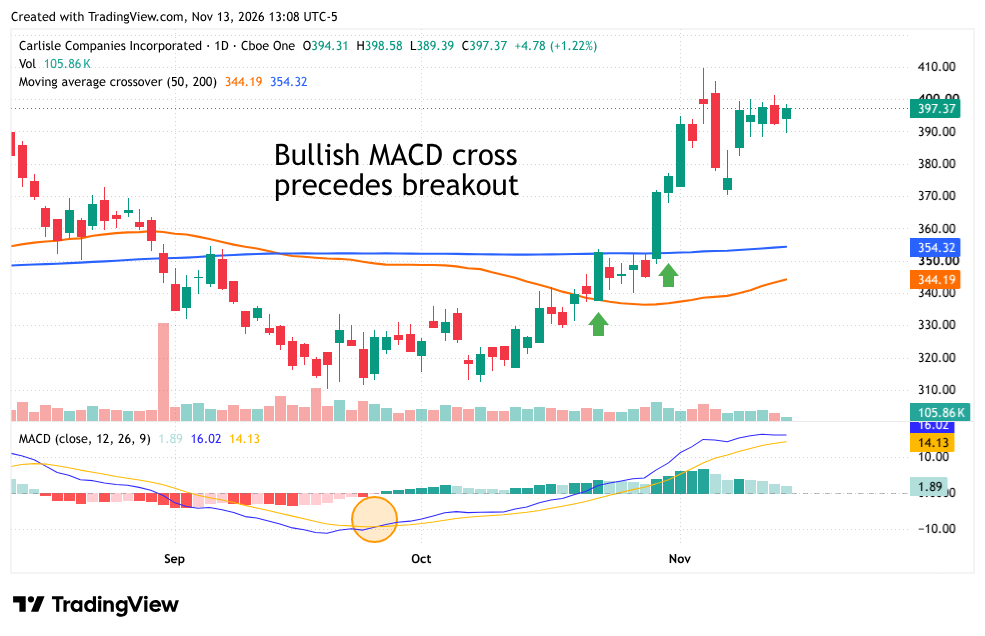
A bullish Moving Average Convergence Divergence (MACD) crossover in September preceded the recent breakout, which took the price back above the 50-day and 200-day moving averages. The stock is now up nearly 25% on the year, with nearly all of those gains coming in the last 30 days. Momentum is strong, and the technical signals point to more upside ahead.
James Hardie: Taking Market Share Through Mergers and Acquisitions
James Hardie Industries PLC (NYSE: JHX) is a global building-materials firm that expanded into the home remodeling space with its TimberTech decking and fiber-cement siding through its 2025 AZEK acquisition.
Homeowners looking to redo a patio or add an exterior feature will likely seek these products and services, and the company is ahead of schedule in deleveraging after its acquisition.
The company reported fiscal Q2 2027 results on Nov. 5, beating top- and bottom-line estimates and posting YOY sales growth of 24% from continuing operations.
Adjusted EBITDA margin expanded 450 basis points to 31.8%, and the company reaffirmed its full-year fiscal 2027 sales guidance while raising its free cash flow guidance. By segment, Siding & Trim sales grew 15%, and Deck, Rail & Accessories sales grew 51%, with approximately 14 percentage points coming from underlying growth.
However, the Q3 sales guide was below expectations, and the company is priced for perfect execution at 45 times earnings.
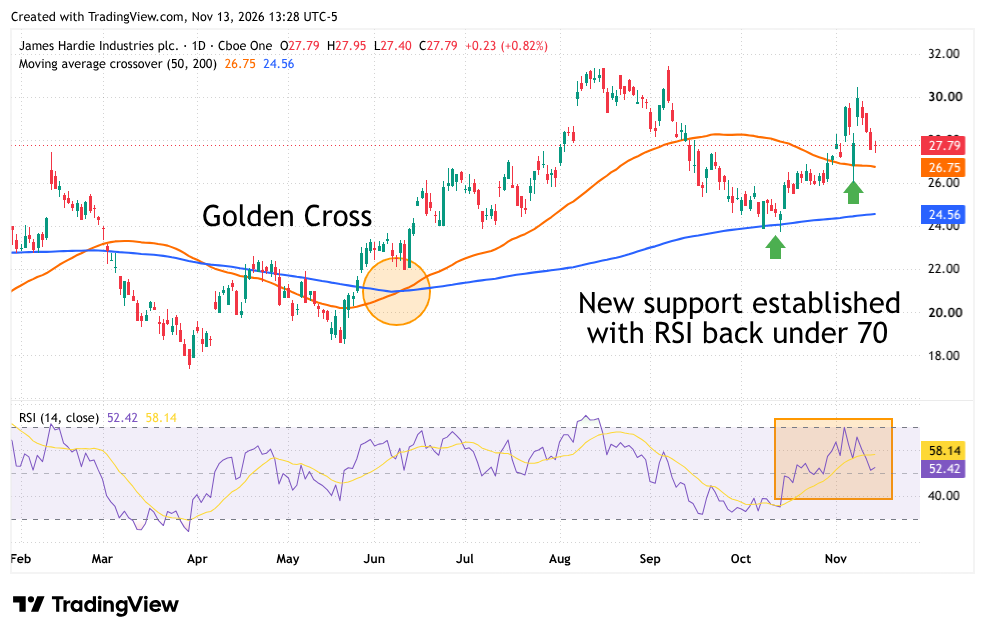
JHX shares have had the rockiest ride in 2026 of our three remodeling stocks, but they’re still up more than 30% YTD and more than 10% in the last month alone.
A Golden Cross in July provided technical traders with some optimism, but momentum faded after a brief rally, and shares once again tested the 200-day moving average. The 200-day moving average held, and the RSI moved back into bullish territory, signaling that the next leg of the rally could begin. Shares are now challenging the 50-day moving average; if support holds here, the rally will maintain a strong technical uptrend that would likely take a negative catalyst to break.
. |


Tidak ada komentar:
Posting Komentar