p.s. It's normally $29.97 on our website, but you can download this quarter's edition free right here.
Today’s editorial pick for you
IREN Q1 Earnings Answer the Microsoft Question—Sellers May Regret It
Posted On Nov 06, 2026 by Chris Markoch
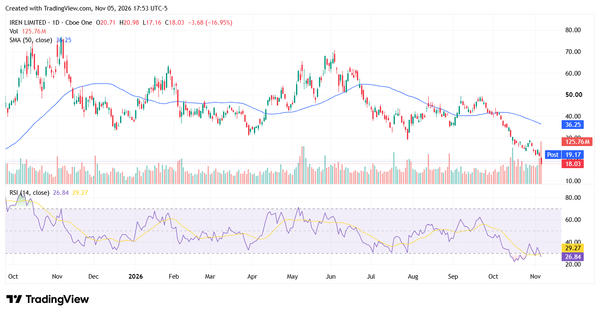
IREN Ltd. (NASDAQ: IREN) shareholders had a rough Thursday before the company even reported earnings. A media report the night before tied delays at IREN’s Childress, Texas, campus to a shortfall in Microsoft’s (NASDAQ: MSFT) quarterly AI spending. The stock fell about 17% in regular trading to close at $18.03, a new 52-week low, on nearly three times its average volume.
Table of Contents
Then IREN reported fiscal first-quarter 2027 results after the close. The headline numbers weren’t flashy. But the report did something more important. It explained the delay, put a size on it, and showed that the money to finish the job is already lined up.
Shares rose about 6% in after-hours trading.
For investors who sold on the headline, the report is a useful reminder. Selling the news often means selling at the worst moment, before a company has had a chance to explain.
The quarter also showed why IREN’s vertically integrated model matters. IREN owns the land, the power, the data centers, and the GPUs. That gives it more ways to fund growth than most rivals have. And funding is the question hanging over every AI cloud stock right now.
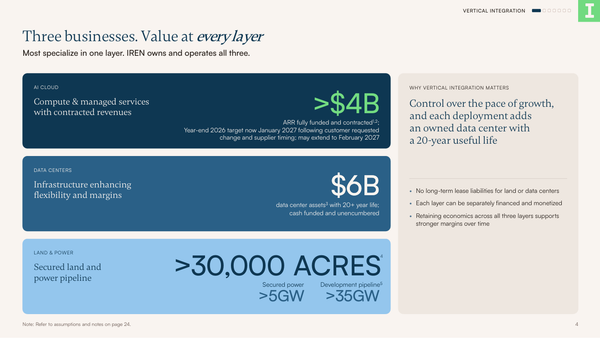
IREN confirmed that its target of more than $4 billion in annualized run-rate revenue (ARR) has slipped. The company now expects to reach it in January 2027 rather than by the end of 2026. It said the date could extend to the end of February.
The reason matters. On the earnings call, co-CEO Daniel Roberts identified the customer as Microsoft. He said Microsoft asked IREN to reconfigure and upgrade network infrastructure so the 200 megawatts (MW) at Childress could serve the latest frontier AI models. Supplier timing also played a role.
That’s a very different story from a construction failure. A customer asking for a bigger, better build is a demand signal, not a warning sign. And the slip is measured in weeks to a couple of months, not quarters.
IREN also says the $4 billion target remains fully contracted and fully funded.
The Quarter: Revenue Beat, Margins Widened
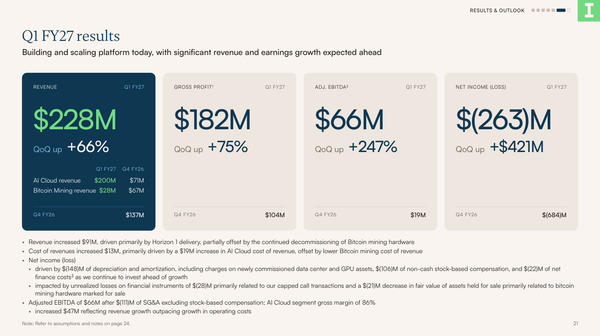
Total revenue rose 66% from the prior quarter to $228 million. That topped the $221 million analyst average compiled by LSEG. AI Cloud revenue nearly tripled to $200 million as Horizon 1 went into service for Microsoft. Bitcoin mining revenue fell to $28 million as IREN continued retiring mining hardware.
AI Cloud gross margin held at 86%. Adjusted EBITDA more than tripled to $66 million, a 29% margin, up from 14% in the prior quarter. Operating ARR doubled to $1 billion.
The net loss narrowed to $263 million from $684 million. Much of what remains is non-cash, including $148 million of depreciation and amortization and $106 million of stock-based compensation.
Revenue backlog rose 22% to $20.3 billion, and about two-thirds of it is with investment-grade counterparties. Microsoft accounts for $9.6 billion and NVIDIA for $3.4 billion. AI developers, a frontier lab, and channel partners make up the remaining $7.2 billion. After the quarter ended, IREN also doubled its capacity with a leading frontier AI lab.
Why Vertical Integration Matters Now
IREN’s pitch is simple. Most AI infrastructure companies specialize in one layer. IREN owns all three: land and power, data centers, and the GPUs that run inside them.
That structure shows up on the balance sheet. IREN holds about $6 billion of data center assets that are cash-funded and unencumbered, with a 20-year useful life. It has more than 5 gigawatts of secured power. And because it owns its buildings, it carries no long-term lease liabilities for land or data centers.
Ownership also lets IREN finance each layer separately. GPU contracts can come with customer prepayments. A five-year deal signed after the quarter includes prepayments covering up to 90% of the GPU cost. Using IREN’s illustrative economics, that cuts the cash payback on the GPUs from about 2.4 years to under half a year.
Pricing is moving in IREN’s favor, too. Recent five-year contracts were priced at about $22 million per MW per year. Short-term contracts came in near $40 million per MW. One H100 contract renewed at double its prior price.
Roberts acknowledged on the call that capital markets have become more selective. Investors now care less about contract size and more about delivery, financing, and profitability. Owning every layer is IREN’s answer to all three.
The Funding Picture
Financing has been the bear case all fall. The report addresses it head-on.
IREN ended September with $5.8 billion in cash, including restricted cash. Remaining planned capital spending for fiscal 2027 is about $15 billion. Of that, $9 billion is covered by cash, committed GPU financing, and customer prepayments. The other $6 billion still needs to be raised.
IREN outlined $12 billion to $15 billion of potential funding capacity at its targeted terms, before any convertible notes or new equity. That includes debt backed by its unencumbered data centers and additional GPU financing.
Near-term maturities look manageable. About $723 million of debt principal comes due over the rest of fiscal 2027. The largest share matures in fiscal 2032 or later.
There are trade-offs. Net debt rose to $4.4 billion from $216 million a quarter earlier. IREN raised about $498 million by selling shares during the quarter. And its newest GPU financing, backed by non-investment-grade customers, carries a 9% rate, compared with 6% on the Microsoft financing.
What the Chart Says
IREN peaked near $77 about a year ago. At Thursday’s close of $18.03, it was down about 76% from that high. The stock trades roughly 50% below its 50-day moving average, and its 14-day RSI sits near 27, deep in oversold territory.
For investors who bought near the top, IREN has been a painful hold. Many weren’t wrong about the business. They were early.
At $18, the setup looks different. IREN’s market value of roughly $7 billion is about a third of its $20.3 billion backlog. It’s also only about 1.4 times the company’s $5.1 billion of shareholders’ equity.
That doesn’t mean the bottom is in. The trend is still down, and the 50-day moving average is still falling. Timing a bottom is notoriously difficult, and patience will likely be required. But a collapsing share price paired with improving fundamentals looks a lot like maximum pessimism. Much of it appears unjustified.
Risks Worth Watching
The report doesn’t remove every risk. Investors should keep four in view:
Delivery – Horizons 2 through 4 for Microsoft still have to be delivered. Further slippage past contractual grace periods could trigger delay credits.
Texas – The company’s own risk factors flag changes to how the state’s grid operator approves large new electricity loads, along with a state-ordered review of data centers in the interconnection queue.
Funding – About $6 billion of fiscal 2027 spending still needs financing, and more share sales are possible.
Concentration – Microsoft accounts for nearly half of the backlog.
Is IREN Stock a Buy After Earnings?
IREN’s quarter wasn’t a blowout. It didn’t need to be. It answered the question that sent the stock to a 52-week low, and it showed the funding to deliver on its contracts.
Investors who sold on Thursday’s headline sold before hearing the explanation. For those with a long enough time horizon, IREN’s current price may prove to be an opportunity rather than a warning.
Today’s editorial pick for you
McDonald’s Added $239 Million in Profit Despite Weak U.S. Traffic
Posted On Nov 05, 2026 by Grayson Cavern
McDonald’s Corporation (NYSE: MCD) found a way to squeeze substantially more profit out of a business that barely grew its revenue in the quarter. Third-quarter sales increased by just $79 million from a year ago, yet operating income climbed by $239 million. Diluted earnings per share reached $3.51, up 10%, while revenue advanced only 1% to $7.16 billion.
Table of Contents
That gap between revenue and earnings growth gives investors a strong profitability story, although the customer numbers introduce a complication. Global comparable sales increased 1.5%, while U.S. comparable sales slipped 0.2%. McDonald’s generated stronger earnings despite struggling to attract more American customers.
McDonald’s operating income rose from $3.36 billion to $3.60 billion, while total operating costs and expenses declined by approximately $160 million. The company also recorded $139 million in net Other operating income, compared with $37 million a year earlier. That $102 million increase accounted for a substantial portion of the operating-income improvement.
Management identified higher Other operating income and stronger sales-driven franchised margins as the primary drivers. Revenue from franchised restaurants increased 3% to $4.49 billion, while sales from company-operated restaurants declined 3% to $2.48 billion. Franchised restaurant margins increased 3%, compared with a 6% decline in company-operated restaurant margins. Total restaurant margins still grew 2%.
The franchise model allows McDonald’s to collect fees and occupancy payments without bearing the full operating expenses of independently operated restaurants. That structure provides an earnings cushion, but the company-operated business reveals where costs are becoming harder to absorb. Management attributed the U.S. company-operated margin decline primarily to ongoing inflationary pressures.
Fewer Customers Are Walking Through The Door
The third-quarter earnings report becomes less reassuring when we examine customer behavior. U.S. comparable sales declined 0.2% because negative guest-count growth was largely offset by positive check growth. Customers who visited spent more, but fewer comparable visits took place.
International operations provided better support. Comparable sales increased 1.4% in International Operated Markets and 4.2% in International Developmental Licensed Markets. Germany and Australia led the operated markets, while Japan helped drive licensed-market growth. China was a partial drag.
Global systemwide sales increased 4% to more than $38 billion, but the U.S. business still needs stronger traffic. Management expects 2026 systemwide sales to grow approximately 2.5% in constant currencies, below the 4% recorded in Q3.
The broader consumer environment makes that recovery harder. Elevated household expenses can make customers more selective about restaurant visits, while higher beef and labor costs pressure restaurant economics. As such, McDonald‘s must offer enough value to attract more visits without allowing discounts and rising expenses to erode margins. Higher average checks cannot indefinitely replace customer traffic.
Expansion Could Carry Growth Beyond Comparable Sales
McDonald’s has another lever if existing restaurants struggle to produce stronger comparable sales. Management expects approximately 2,500 restaurant openings in 2026, including 700 company-operated locations and 1,800 through developmental licensees and affiliates. It expects another 2,100 openings in 2027, targeting 50,000 restaurants worldwide by year-end.
New locations can expand systemwide sales even when comparable sales remain modest. However, expansion requires investment. Management expects capital expenditures of approximately $3.7 billion in 2026 and free cash flow conversion in the low-to-mid 80% range.
Can MCD Turn Its Earnings Strength Into a Sustained Recovery?
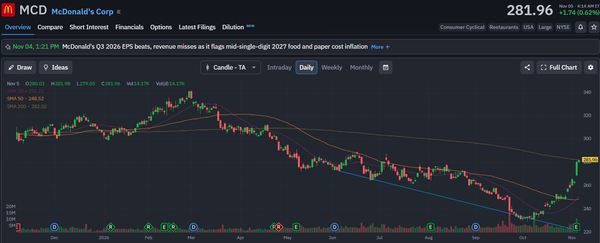
The earnings rally has brought MCD back toward a critical technical level. Shares traded at $281.96 on November 5, above their 20-day moving average of $251.21 and 50-day average of $248.52, but just below the 200-day average at $282.52.
MCD had declined from the low-330s in March toward the low-220s in October. The latest rally has reversed a substantial portion of that decline, but the stock has yet to establish that its longer-term downtrend has ended.
A sustained break above $282.52 would strengthen the recovery. Buyers would then need to defend that level during any pullback. If the breakout fails, the 20-day and 50-day averages around $251 and $249 become the next important support zone.
Calls For Caution
I’d be cautious about chasing the rally before MCD establishes support above its 200-day average. The franchise model is supporting earnings growth, but higher Other operating income contributed substantially to the latest improvement while U.S. guest counts remain weak.
For investors, the next catalyst is evidence that McDonald’s value initiatives can restore traffic without sacrificing restaurant margins. Until comparable guest counts improve and the stock establishes support above its 200-day average, the earnings beat offers a reason to watch the recovery rather than assume the turnaround is complete.


Tidak ada komentar:
Posting Komentar