|
Any content you receive is for information purposes only. Always conduct your own research.
*Sponsored
Cemtrex, Inc. (Nasdaq: CETX) Just Landed Back At The Top Of Our Watchlist
For Tomorrow Morning—Monday, November 16, 2026
Don’t Miss Our Next Update—Get Real-Time Alerts Sent Directly To Your Phone. Up To 10X Faster Than Email.
Get Focused On (CETX) Before Tomorrow Morning…
November 15, 2026
Dear Reader,
A few weeks ago, we put Cemtrex, Inc. (Nasdaq: CETX) at the top of our watchlist.
The next morning, the company reported preliminary fourth quarter results — Q4 revenue of $22.7M, up 22% year-over-year, with $1.4M in operating income, $1.9M in Operating EBITDA, and gross margins expanding to 46.3%.
It was the best quarter of the entire fiscal year.
According to Barchart, (CETX) closed around $1.74 on October 28 — and reached $3.09 the very next day. An approximate 77% move in 24 hours on a name with fewer than 2M shares in the public float.
That was the first chapter.
Here’s why we’re coming back for a second look…
The same potential catalysts that drove our initial coverage haven’t slowed down. If anything, they’ve gotten stronger.
Cemtrex, Inc. (Nasdaq: CETX) subsidiary Vicon Industries recently received orders from a U.S. federal government agency for its video surveillance products and Valerus platform — shipped through an existing channel partner, expected to be fulfilled in the current fiscal quarter.
And Plant Engineering Services, acquired just months earlier, had already picked up five project awards totaling approximately $410K — including work on a 5,000-ton water press restoration for a precision forging manufacturer in California.
These aren’t hypothetical milestones sitting on a roadmap.
These are contracts being executed right now…
And they’re arriving at a moment when the macro backdrop could hardly be more supportive.
The defense budget is expanding.
Reshoring is accelerating.
Infrastructure spending keeps climbing.
And critical-facility security — prisons, government buildings, federal campuses — is seeing sustained modernization demand.
Cemtrex, Inc. (Nasdaq: CETX) sits at the intersection of all three — with three completed acquisitions in 2026, a new Aerospace & Defense segment already generating operating income, and an equity base that has nearly quadrupled since fiscal year-end.
Cemtrex, Inc. (Nasdaq: CETX) will be topping our watchlist tomorrow morning — Monday, November 16, 2026.
Keep in mind, (Nasdaq: CETX) has a float less than 2M shares listed as available to the public—with a float that small, the potential exists for big moves if demand begins to shift.
Three Segments, Three End Markets, One Small Float
The first thing to know about Cemtrex, Inc. (Nasdaq: CETX) is that it operates across several different businesses, not just one product or service.
It's a diversified operating platform running across three segments — Security, Industrial, and Aerospace & Defense — each generating its own revenue, serving its own customer base, and riding its own secular tailwind.
The Security segment operates through Vicon Industries, a decades-old name in video management software, high-performance cameras, and integrated surveillance solutions serving government, corrections, and enterprise customers.
That matters because the demand behind video surveillance is real and accelerating…
According to Grand View Research, the global video surveillance market was estimated at $83.48B in 2025 and is projected to reach $204.68B by 2033 at an 11.7% CAGR.
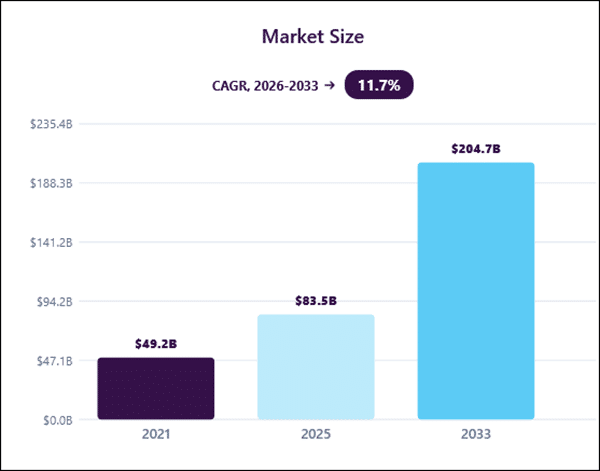
Vicon sits directly in that growth path.
And the orders are landing.
Since May, Vicon has announced approximately $2.9M in corrections-related orders, including a $900K single-facility award covering the complete Vicon platform — cameras, servers, workstations, software — deployed end-to-end through a specialist detention integrator.
Corrections is one of the most demanding end markets in physical security.
Systems run continuously for years in hardened environments, and integrators who concentrate an entire facility on a single vendor do so only when they trust that vendor completely.
That kind of full-platform commitment from a single customer — every camera, every server, every screen on one system — speaks louder than any quarterly guidance.
The Industrial segment, operated through Advanced Industrial Services (AIS), delivers specialized rigging, millwrighting, piping, and equipment installation for manufacturers nationwide.
AIS has grown from approximately $21M to $38M in annual revenue between FY2022 and FY2025.
That's a near-doubling in three years — steady, compounding expansion built on a high-repeat customer base across infrastructure end markets.
With reshoring trends accelerating and domestic manufacturing capacity expanding, AIS sits in the direct path of multi-year capital deployment.
These are the kinds of services — rigging heavy equipment, installing production lines, maintaining complex manufacturing infrastructure — that don't get offshored and don't get automated.
Somebody has to physically put the machines in place.
AIS does that work.
And then there's the segment that could change the math entirely.
The Aerospace & Defense segment, anchored by Invocon, brings a 40-year-plus engineering heritage in mission-critical instrumentation, wireless sensing, and telemetry for space and missile programs.
Invocon counts the Missile Defense Agency and major defense primes among its customers.
In April 2026, the subsidiary was selected for a U.S. Navy SBIR Phase I contract in naval mine warfare.
That's not a press release talking point.
That's the Department of Defense validating a capability — and potentially opening a pipeline of follow-on work in an area where program continuity and institutional trust matter more than the initial contract value.
Phase I work, by design, is meant to demonstrate feasibility before larger Phase II funding follows.
Three Deals Done — And A Fourth On The Way
What separates (CETX) right now is the velocity of its platform expansion.
In calendar 2026 alone, the company has completed three acquisitions…
Invocon closed in January for $7.1M in cash, launching the Aerospace & Defense segment from scratch.
Richland closed in February, extending AIS's geographic footprint into Tennessee and the Southeast.
And in July, Plant Engineering Services (PES) joined the platform — adding the engineering expertise that sits upstream of AIS's installation, rigging, and millwrighting work.
PES specializes in the design, modernization, and relocation of large hydraulic and mechanical press systems for aerospace forging, automotive, defense, and heavy manufacturing.
Founded more than thirty years ago, PES is expected to contribute $4–5M in revenue over the next twelve months.
The combination creates something the two companies couldn't offer on their own…
AIS can now pursue turnkey capital projects — from engineering and design through installation and commissioning — under a single platform.
Chairman and CEO Saagar Govil described the fit directly: "PES brings deep engineering expertise that AIS has never had in-house, and AIS brings the field execution resources that PES has historically sourced externally. Each company is a natural customer of the other."
And perhaps the most telling signal of all…
An additional Industrial Services deal is currently under letter of intent and targeted for the September quarter.
Four completed deals in a single fiscal year would represent a cadence that signals real intent — a management team actively compounding a platform, not just presenting slides about one.
And because all three acquisitions were done with corporate overhead essentially unchanged from FY2025, each new segment's earnings compound against a fixed cost base.
That's the kind of operating structure where scale creates meaningful margin expansion as the platform grows.
The Numbers Tell The Real Story
What makes the timing worth watching is that the most recent results confirm a full year of operational momentum — building quarter after quarter, with Q4 delivering the strongest numbers of fiscal 2026.
Cemtrex, Inc. (Nasdaq: CETX) reported preliminary fourth quarter revenue of $22.7M, up 22% year-over-year and 23% sequentially from Q3.
That’s the highest quarterly revenue figure the company posted all year.
Q4 operating income reached $1.4M, with Operating EBITDA of $1.9M — compared to a loss of $0.6M in Q3 and a loss of $0.8M in the prior-year fourth quarter.
Gross margins expanded to 46.3%, up from 41.7% in Q3 and 38.0% a year ago.
And this didn’t come out of nowhere…
The trajectory had been building all year.
In Q3, revenue was $18.4M, up 9% year-over-year. The Aerospace & Defense segment delivered $2.2M in revenue with $1.0M in segment operating income on 87% gross margins — in only its second quarter of consolidation.
Vicon’s segment operating loss had narrowed to $0.3M from $3.0M in Q1 — a 90% improvement across two quarters, with gross margins climbing to 49%.
Operating cash flow turned positive in Q3 at $0.2M — a meaningful shift from the $5.1M used in operations during the first half…
And then Q4 accelerated every one of those trends.
The balance sheet reflects the same transformation.
Shareholders’ equity stands at $32M, up from $8.7M at fiscal year-end — nearly four times the starting figure.
Cash and marketable securities totaled $11.7M as of June 30, 2026.
These aren’t projections on a slide deck.
These are reported figures showing four consecutive quarters of sequential improvement — culminating in the strongest revenue, the strongest margins, and the first quarter of positive operating income all year.
And here’s what connects the balance sheet to the acquisition strategy…
With $11.7M in cash and securities and a strengthened equity base, the company has the financial capacity to keep compounding — and management has already said it intends to maintain this pace of acquisitions into FY2027 and beyond.
9 Reasons Why We’ll Be Focused On (CETX) Tomorrow Morning
—Monday, November 16, 2026…
1. Small Float: With fewer than 2M shares listed as available to the public, (CETX) has already shown how quickly attention can translate into sharp price movement.
2. Recent Momentum: After closing near $1.74 on October 28, (CETX) reached $3.09 the next day, an approximate 78% move in 24 hours.
3. Record Quarter: Preliminary Q4 results showed (CETX) revenue of $22.7M, up 22% year over year, with $1.4M in operating income and 46.3% gross margins.
4. Federal Orders: Through Vicon Industries, (CETX) recently received multi-facility surveillance orders from a U.S. federal government agency for products expected to ship this fiscal quarter.
5. Defense Segment: The Aerospace & Defense business at (CETX) produced $2.2M in Q3 revenue and $1.0M in segment operating income on 87% gross margins.
6. Acquisition Expansion: Management at (CETX) completed three acquisitions in 2026, adding defense, engineering, and broader industrial capabilities to the platform.
7. New Awards: Plant Engineering Services, acquired by (CETX) in July, secured five project awards totaling about $410K within its first months under the company.
8. Security Momentum: Vicon, a (CETX) subsidiary, has announced about $2.9M in corrections-related orders since May, including a $900K single-facility award.
9. Stronger Financials: Shareholders’ equity at (CETX) rose to $32M from $8.7M at fiscal year-end, while cash and marketable securities totaled $11.7M.
Get Focused On (CETX) Before Tomorrow Morning…
When you stack it all up — a diversified three-segment platform, sequential improvement across the business, new government defense contracts, a compounding acquisition pipeline, and a float under 2M shares — (CETX) presents a profile that deserves a spot on your screen.
And the numbers keep confirming it…
Just a few weeks ago, the company reported preliminary Q4 results showing revenue of $22.7M — up 22% year-over-year — with $1.4M in operating income, $1.9M in Operating EBITDA, and gross margins expanding to 46.3%. It was the strongest quarter of fiscal 2026.
The last time we highlighted (CETX), the name made an approximate 77% move inside of 24 hours — closing around $1.74 on October 28 and reaching $3.09 the following session, according to Barchart.
That kind of reaction on a float under 2M shares is exactly why this name keeps landing at the top of our watchlist.
The company reported $76.5M in revenue last fiscal year…
It’s actively expanding into defense, automotive, and critical infrastructure end markets…
And the Q4 trajectory — revenue up 23% sequentially, operating income turning positive, margins at their highest level all year — suggests the platform is compounding exactly the way management said it would.
Anyone following the industrial and defense space should have this name on their radar.
We’ll be focused on (CETX) tomorrow morning before the bell. Keep an eye out for our next update, it could be coming earlier than usual.
Sincerely,
Jeff Ackerman
Managing Editor
Stock News Trends
StockNewsTrends.com (“StockNewsTrends” or “SNT” ) is owned by TD Media LLC, a single member limited liability company. Data is provided from third-party sources and SNT is not responsible for its accuracy. Make sure to always do your own research and due diligence on any day and swing profile SNT brings to your attention. Any emojis used do not have a specific defined meaning, and may be used inconsistently. We do not provide personalized in-vest-ment advice, are not in-vest-ment advisors, and any profiles we mention are not suitable for all in-vest-ors.
Pursuant to an agreement between TD Media LLC and Interactive Offers LLC, TD Media LLC has been hired for a period beginning on 11/15/2026 and ending on 11/16/2026 to publicly disseminate information about (CETX:US) via digital communications. Under this agreement, Interactive Offers LLC has paid TD Media LLC fifteen thousand USD (“Funds”). To date, including under the previously described agreement, TD Media LLC has been paid two hundred ninety seven thousand USD (“Funds”). These Funds were part of the fifteen thousand USD funds that TD Media LLC received from a third party named Interactive Offers LLC who did receive the Funds directly or indirectly from the Issuer and does not own stock in the Issuer but the reader should assume that the clients of the third party own shares in the Issuer, which they will liquidate at or near the time you receive this communication and has the potential to hurt share prices.
Neither TD Media LLC and their member own shares of (CETX:US).
Please see important disclosure information here: https://lifewatermedia.com/disclosure/cetx-ihveP/#details
|

Tidak ada komentar:
Posting Komentar