
A Message From Profits Run
Here's what changes if you wait to download my "Simple Options Trading For Beginners" book.
The book doesn't. Same pages, same plain-English explanations, same handful of techniques.
The only thing that changes is the price.
Right now, through this temporary link, it costs nothing.
After the link expires, it's $29.97 on my website. That's what it sells for most of the year.
So "I'll grab it later" isn't really a delay. It's a decision to pay $29.97 for something you could have had for nothing.
Not a great trade.
The better one takes a few seconds and happens today.
Download your copy while it's still $0.
Good Trading,
Bill Poulos
P.S. Once it's saved to your computer, the price can't reach it. That only works if you grab it before the link expires.
More Reading from MarketBeat Media
MicroVision Pivots: Mapping New Ground Beyond Auto
Written by Jeffrey Neal Johnson. Date Posted: 11/3/2026.
Key Points
- MicroVision is expanding its FieldAI partnership to pivot from automotive LiDAR toward industrial and government robotics markets with faster deployment timelines.
- The company reported a backlog exceeding $10 million and gross margins improving to about 39%, up from single digits previously.
- Despite trading at roughly half its book value per share, MicroVision faces significant cash burn, heavy short interest, and liquidity challenges.
- Special Report: Insiders quietly moving money as Democrats take over Congress
The LiDAR sector often gets bogged down by the automotive industry's protracted design cycles. Automakers often require years of evaluation before committing to commercial-scale deployments, leaving technology developers burning cash while they wait for revenue to materialize.
MicroVision (NASDAQ: MVIS) is adjusting its approach. By expanding its partnership with FieldAI, MicroVision is refocusing on autonomous robotics for industrial and government applications.
This shift moves the business away from relying solely on automakers and targets markets with much shorter deployment timelines.
For investors, this pivot points to a clearer, more immediate path to commercialization. As MicroVision begins producing sensors for edge AI applications, it is establishing a framework to bridge the gap between research and development and sustained revenue generation.
Steering Away From Automotive Traffic
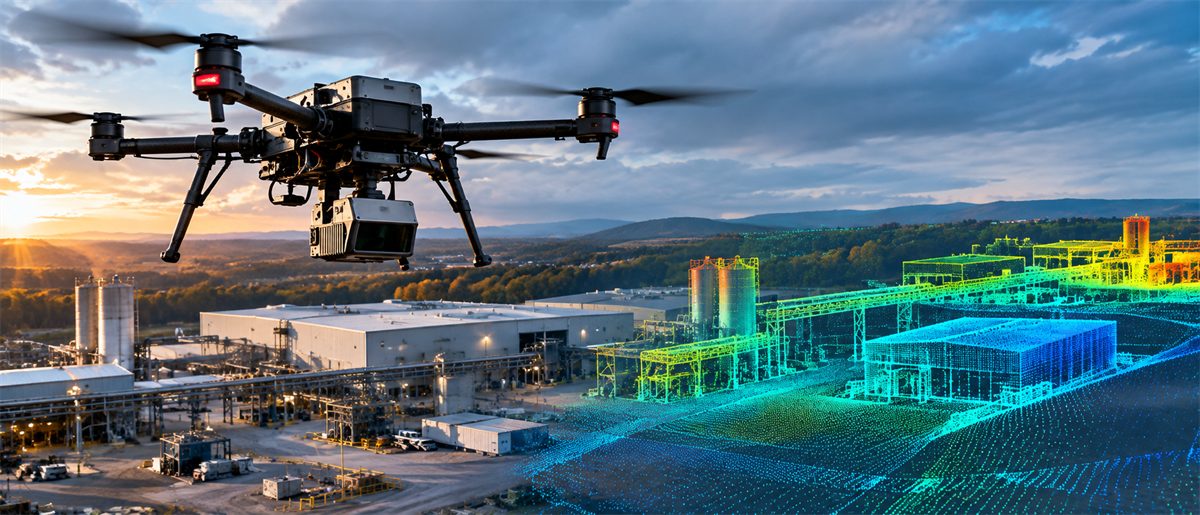
The expanded partnership with FieldAI moves MicroVision's perception technologies from testing into real-world use. FieldAI focuses on integrating advanced autonomy into uncrewed ground vehicles and aerial systems for both industrial and federal applications. The partnership uses MicroVision's IRIS long-range sensor alongside its MOVIA Air Plus system to enable real-time 3D mapping and obstacle detection.
Automotive LiDAR integration typically involves a multiyear gauntlet of safety certifications, platform design phases and rigorous regulatory testing. By contrast, industrial robotics and federal drone programs operate on tighter procurement cycles. These environments require highly capable machines that can navigate unstructured, dynamic settings without human intervention. By focusing on these non-automotive sectors, MicroVision positions itself to capture immediate enterprise demand.
The recent start of commercial production for the MOVIA Pro sensor aligns well with this strategy. This hardware is designed specifically for edge AI and short-range perception, delivering the spatial awareness industrial robotics clients need today. Shifting engineering resources toward products that can be sold and deployed in the current fiscal year allows MicroVision to bypass delays currently slowing the broader autonomous driving market.
Scaling Operations While Expanding Margins
Moving away from a purely research-driven model requires tangible financial execution. Recent updates from MicroVision indicate that this transition is steadily underway. Management highlighted a growing backlog exceeding $10 million during the third quarter of 2026, alongside projections that top-line revenue could potentially double in the upcoming fiscal year. A growing backlog is a critical metric for hardware developers because it represents committed client capital rather than speculative pilot programs.
Revenue growth translates into a sustainable business only if the underlying unit economics make sense. Historically, LiDAR companies have struggled with steep margin compression during early manufacturing stages, often selling hardware at a loss to secure market share. After integrating past acquisitions and pursuing strategic cost-structuring efforts throughout the year, MicroVision has shown notable gross margin improvement.
Margins have expanded from single digits in previous periods to approximately 39%, a significant improvement. As MicroVision scales sensor deliveries for the FieldAI partnership and similar industrial contracts, this improved margin profile suggests new revenue will flow much more efficiently to the bottom line. Achieving higher margins early in commercialization helps offset operational cash burn and reduces long-term reliance on external funding.
A Deep-Value Disconnect
The stock market often discounts companies navigating extended pre-revenue or low-revenue phases. Trading near $1.35 per share, MicroVision has a market capitalization of about $32 million. A closer look at the balance sheet reveals a notable valuation disconnect. MicroVision has a book value of about $2.73 per share, meaning the stock trades at a price-to-book ratio near 0.49.
Technology companies typically trade at multiples well above book value, reflecting expectations for future growth and the value of their intellectual property. The market is valuing MicroVision at roughly half its net asset value, creating a deep-value setup.
This steep discount is accompanied by significant bearish positioning. The stock has high short interest, reflecting broader market skepticism about MicroVision's ability to reach profitability before depleting its cash reserves.
Heavy short positioning creates a unique technical environment. If the expanded industrial order book translates into sequential revenue beats, the underlying fundamentals could force a repricing. In heavily shorted stocks, unexpected commercial success often triggers short covering. As short sellers buy back shares to close their positions, they can add meaningful upward pressure to the stock price, amplifying the market's reaction to positive business developments.
Fueling the Transition With Capital Buffers
While the shift toward industrial robotics offers a compelling narrative, the balance sheet requires careful consideration. Developing and manufacturing advanced optical and semiconductor technology is highly capital-intensive. MicroVision has an annual net loss approaching $95 million and trailing 12-month earnings per share of negative $5.11.
Liquidity remains a central metric for evaluating MicroVision's timeline. The current ratio is approximately 0.68, indicating that near-term liabilities outweigh readily available liquid assets. To buffer its cash burn, management has tapped the capital markets. A $17 million private offering, along with additional stock and warrant issuances earlier in 2026, provided necessary liquidity.
These funding events are crucial to sustaining operations while the FieldAI partnership and other commercial initiatives ramp up. Management's primary challenge is scaling industrial revenue fast enough to outpace ongoing cash burn. The recent capital raises extend the runway, giving MicroVision time to fulfill its growing backlog and work toward a cash-flow-neutral state.
Gauging the Next Steps for the Pivot
The success of this pivot rests entirely on execution. Securing development agreements and pilot programs is a positive first step, but MicroVision's long-term viability depends on converting those agreements into recurring, high-volume hardware sales. The industrial and federal robotics markets offer the accelerated timeline the company needs to bridge the gap between its current cash burn and future profitability.
Investors evaluating the LiDAR space may want to track MicroVision's upcoming quarterly deliveries. Progress on the stated $10 million backlog will be a key indicator of whether the industrial strategy is gaining traction.
If MicroVision can maintain its improved gross margins while fulfilling these new commercial orders, the current discount to book value may present a compelling setup for investors with an appropriate risk tolerance. Monitoring how quickly the FieldAI integration moves from initial evaluation to fleet-wide deployment will provide the clearest view of MicroVision's commercial trajectory.
. |


Tidak ada komentar:
Posting Komentar